The main tag of Gold News Today Articles.
You can use the search box below to find what you need.
[wd_asp id=1]

12 05, 2026

Fair Trade Decaf Coffee Market in the United Kingdom | Report – IndexBox

By |2026-05-12T05:35:04+03:00May 12, 2026|Forex News, News|0 Comments


United Kingdom Fair Trade Decaf Coffee Market 2026 Analysis and Forecast to 2035

Executive Summary

Key Findings

  • The United Kingdom Fair Trade Decaf Coffee market is expanding at a 7–11% compound annual growth rate (2026–2035), outpacing the mainstream coffee market by a factor of three, driven by the confluence of health-motivated caffeine reduction and ethical consumption values.
  • Arabica varieties command a 75–85% share of segment volume, with the premium home-brewing channel acting as the primary growth engine, while Robusta holds ground in cost-sensitive office coffee service blends.
  • The market is entirely import-dependent, with green beans sourced from Latin America and East Africa, processed mainly in Germany and Canada, creating a multi-layered cost structure that is 20–40% higher than conventional roasted coffee.

Market Trends

  • Consumer preference is shifting decisively toward Swiss Water and Carbon Dioxide (CO₂) processed decaf beans, perceived as chemical-free, with these methods accounting for an estimated 55–65% of Fair Trade Decaf retail SKUs in 2026.
  • Direct-to-consumer subscription models offering traceable, freshly roasted Fair Trade Decaf are growing at 15–20% annually, capturing higher margins and displacing some grocery volume in premium urban catchments.
  • Major UK grocery multiples are expanding their private-label Fair Trade Decaf lines, targeting a 25–30% volume share by 2030 as they optimize dual-certified supply chains and compete on price with global branded owners.

Key Challenges

  • The cost premium of maintaining dual certification—Fair Trade and decaffeination—creates a retail price gap of 20–40% versus standard coffee, capping mass-market adoption in a cost-of-living-sensitive environment.
  • Supply bottlenecks persist due to limited availability of certified Fair Trade green beans routed through specialty decaffeination plants, constraining volume growth and leaving roasters competing for contracted processor capacity.
  • Competition from domestic-focused specialty caffeine-free alternatives, including herbal infusions and mushroom-based coffees, is fragmenting the ethical low-caffeine beverage occasion in the premium tier.

Market Overview

The United Kingdom is one of Europe’s largest coffee-consuming nations, with an estimated 98 million cups consumed daily across retail and foodservice channels. Within this mature landscape, the convergence of health-consciousness and ethical spending has carved a distinct growth corridor for Fair Trade Decaf Coffee. This sub-category sits at the intersection of two powerful consumer currents: a structural shift toward reduced caffeine intake among over-35s and millennials, and a willingness to pay a premium for third-party-certified ethical sourcing. Fair Trade Decaf Coffee commands a price point 20–40% higher than conventional roasted coffee, supported by a consumer base that increasingly views purchasing decisions as expressions of personal and environmental responsibility.

The market is structurally dependent on complex global supply chains. High-altitude Arabica farms in Latin America and East Africa supply certified green beans, which are then routed to specialized decaffeination facilities—predominantly in Germany, Canada, and Mexico—before reaching UK-based roasters. This extended value chain creates both cost pressure and an opportunity for brand differentiation based on traceability. The United Kingdom is not a coffee-growing country, so the domestic role is limited to roasting, blending, packing, and distributing. The London coffee exchange historically anchors global pricing, but physical supply flows entirely through imports, making the market sensitive to logistics costs, currency fluctuations between the pound and producer-country currencies, and certification audit cycles.

Market Size and Growth

While the overall United Kingdom coffee market grows at a stable 2–3% per annum, the Fair Trade Decaf segment is expanding at a 7–11% compound rate over the 2026–2035 forecast horizon. Volume growth is being fueled by a 15–20% annual increase in the number of SKUs dedicated to ethically labeled low- and no-caffeine options across grocery, specialty, and online channels. Value growth outpaces volume growth due to the persistent shift toward premium specialty grades—single-origin Arabica, small-batch roasted, and Swiss Water processed—which command higher unit prices and carry thicker retail margins.

The segment’s share of total UK decaf coffee is estimated at 30–40% in 2026, up from roughly 20% five years earlier, reflecting the pace at which ethical certification is becoming an expected attribute rather than a differentiator in the decaf aisle.

Demographic tailwinds are strong. Gen Z and younger millennials, who will represent 45–55% of UK coffee buyers by 2030, show measurably higher willingness to pay for products that combine personal health benefits with verified ethical sourcing. This cohort is driving trial and repeat purchase of Fair Trade Decaf at a rate 1.5–2 times higher than the general coffee-drinking population. Assuming current supply constraints are eased by investments in decaffeination capacity and certification infrastructure in origin countries, market volume could double by 2035, with the premium specialty segment capturing an increasing share of the value pool.

Demand by Segment and End Use

By type, Arabica dominates the United Kingdom Fair Trade Decaf market with a 75–85% volume share, driven by its superior taste profile and its alignment with the at-home brewing rituals of specialty-oriented consumers. Blended products—typically Arabica–Robusta mixes—hold 10–15% share, concentrated in mid-tier office coffee service (OCS) programs where cost control matters. Straight Robusta accounts for the remainder, used almost exclusively in the instant and low-cost pod segments, where the more aggressive flavor profile is partially masked by milk or sweeteners. The Arabica share is expected to increase further as roasters introduce single-origin Fair Trade Decaf offerings from Ethiopia and Colombia, which retail at a 30–50% premium over blended equivalents.

By application, at-home consumption represents 55–65% of segment volume, a share solidified by the hybrid work trend. Home brewing occasions—particularly pour-over, AeroPress, and bean-to-cup machines—favor whole-bean and freshly ground formats. Office and workplace consumption accounts for 20–25% of volume, with a distinct recovery underway as corporate offices restock their coffee programs post-pandemic, often with an explicit mandate to include Fair Trade options. Gifting, particularly around the Christmas season, represents 10–15% of retail value in the segment, featuring whole-bean Fair Trade Decaf packs positioned as ethical premium gifts. Corporate gift buyers are an emerging sub-segment, driving demand for branded, sustainably sourced coffee hampers for employees and clients.

Prices and Cost Drivers

The pricing architecture of Fair Trade Decaf Coffee in the United Kingdom reflects a multi-layered cost stack. At the base sits the global green bean commodity price—benchmarked to the ICE Futures US ‘C’ contract for Arabica—which has shown structural volatility of 20–40% year-on-year due to climate disruptions in Brazil and Colombia. On top of this, the Fair Trade minimum price floor and the additional Fair Trade premium (currently $0.20–0.40 per pound) provide a price buffer for certified producers. Decaffeination adds a significant cost layer, ranging from $0.40 to $1.00 per pound depending on the method: Swiss Water Processing commands the highest premium, followed by CO₂, with sugar-cane-based ethyl acetate methods occupying the lower end. Roasting, packing, and logistics add further margin layers before retail shelf pricing is set.

In the UK retail channel, ground Fair Trade Decaf typically retails for £7–14 per kilogram, compared to £5–9 per kilogram for standard non-organic, non-decaf roasted coffee. Instant Fair Trade Decaf trades at a narrower absolute premium due to higher processing throughput. The primary cost drivers in 2026 are energy prices—roasting is an energy-intensive process—and logistics costs, which have risen 15–25% since 2021 due to container shipping volatility and post-Brexit customs administration. Currency exposure is material: the pound’s purchasing power against the Brazilian real and Colombian peso directly impacts landed green bean costs. Promotional discounting by major grocers periodically compresses retail margins, but the Fair Trade premium floor prevents the cost base from dropping below a sustainable threshold for producers.

Suppliers, Manufacturers and Competition

The competitive landscape in the United Kingdom Fair Trade Decaf market is a dichotomy of global branded owners and agile specialty roasters. Jacobs Douwe Egberts (JDE) and Nestlé are dominant in the mainstream retail and OCS channels, offering Fair Trade-certified lines under brands such as Kenco and Nescafé Azera. These players benefit from vast procurement networks that buffer green bean price volatility and from long-term contracts with large decaffeination plants in Germany. Their scale allows them to price Fair Trade Decaf competitively, often at a 15–20% premium to their conventional ranges, applying margin pressure on smaller rivals.

Specialty roasters such as Union Hand-Roasted, Pact Coffee, and Grind are driving growth in the premium direct-to-consumer segment, emphasizing Swiss Water Processing, direct-trade relationships with specific cooperatives, and origin-specific seasonal offerings. These brands command retail prices 30–60% above mass-market equivalents and enjoy higher customer retention via subscription models. Private-label specialists serving Tesco, Sainsbury’s, and Waitrose are expanding their ranges, capturing value-conscious ethical shoppers who prioritize certification over brand name.

Importing wholesalers such as Beyers Koffie and DRWakefield play a critical upstream role, sourcing certified green beans, managing decaffeination contracts, and supplying both large roasters and small independents. The competitive intensity is high, with shelf-space fights occurring primarily around the “premium everyday” price tier at £8–11 per kilogram.

Domestic Production and Supply

The United Kingdom has no commercial coffee cultivation and is wholly dependent on imports for its Fair Trade Decaf supply. The domestic role in the value chain is concentrated in roasting, blending, grinding, packing, and distribution. Major roasting facilities are located in London, Southampton, and Yorkshire, with a growing cluster of micro-roasters in the Midlands and Scotland serving local subscription and retail accounts. The UK’s historical role as a global coffee trading hub—anchored by the London International Financial Futures and Options Exchange (LIFFE) Robusta futures contract—means that significant financial and logistical infrastructure exists even though physical production is absent.

The supply model is entirely import-driven and relies on a complex logistics network. Green beans arrive at UK ports (Southampton, Felixstowe, Tilbury) in containerized shipments from producer countries. A substantial share of Fair Trade green beans is first shipped to decaffeination plants in Germany (CO₂ process) or Canada (Swiss Water process), then re-exported to the UK as decaffeinated green beans. This routing adds 4–8 weeks to lead times and increases costs by $0.30–0.60 per kilogram for logistics and double customs clearance.

Warehousing capacity for green coffee in the UK is concentrated near port hubs, with London’s Docklands area housing several temperature-controlled facilities. The just-in-time roasting model favored by specialty roasters means inventory buffers are thin, making the supply chain vulnerable to shipping disruptions or phytosanitary delays at borders.

Imports, Exports and Trade

The United Kingdom is a net importer of coffee, and the trade flow for Fair Trade Decaf is particularly complex due to the decaffeination processing step. The primary product classification codes used are HS 090122 (decaffeinated coffee, not roasted) and HS 090121 (decaffeinated coffee, roasted). Green beans classified under HS 090111 and HS 090112 enter the UK from producer countries before being re-exported for decaffeination or, increasingly, processed for decaffeination in continental Europe then re-imported. Germany is the dominant supplier of processed decaf green beans to the UK, with Canada—home to the Swiss Water facility—accounting for a growing share, particularly for the premium specialty segment.

Origin countries for the green beans include Brazil, Colombia, Peru, Ethiopia, and Uganda, collectively supplying 80–90% of the UK’s Fair Trade green coffee volume. Post-Brexit trade documentation, including rules of origin requirements under the UK-EU Trade and Cooperation Agreement, adds administrative overhead for EU-sourced decaf beans, though zero-tariff access generally applies if the beans are sufficiently processed in the EU. Re-exports of roasted Fair Trade Decaf from the UK to other European markets are small but growing, driven by London’s reputation as a specialty coffee hub. Import patterns suggest that roasters are increasingly contracting directly with producer cooperatives rather than relying on the European spot market, a shift that improves traceability but increases procurement lead times and inventory requirements.

Distribution Channels and Buyers

Grocery retail is the largest distribution channel for Fair Trade Decaf Coffee in the United Kingdom, accounting for an estimated 40–50% of the volume sold. Tesco, Sainsbury’s, Waitrose, and Marks & Spencer all dedicate shelf space to the category, with category managers actively curating ranges to meet explicit sustainability mandates. These buyers prioritize suppliers who can guarantee consistent volume, FLOCERT certification documentation, and year-round availability. Pricing negotiations are intense, and private-label penetration is increasing as retailers seek to offer a Fair Trade Decaf option at a lower price point than branded alternatives.

Direct-to-consumer (DTC) subscriptions represent 15–20% of volume but a higher share of revenue, given the premium pricing. Companies such as Pact Coffee and Grind have built loyal subscriber bases by offering freshly roasted beans shipped within days of roasting, often with detailed origin stories and decaf-process documentation. This channel allows for higher margins and direct customer data, but carries higher logistics costs per unit. Office coffee service (OCS) accounts for 20–25% of volume, with corporate procurement managers increasingly requiring Fair Trade certification as part of ESG commitments.

Specialty cafés account for 10–15% of volume, often featuring a single-origin Fair Trade Decaf as a pour-over option to capture the afternoon and early evening caffeine-sensitive occasion. Buyer groups span ethical-conscious consumers, health-motivated caffeine-sensitive individuals, corporate gift buyers, and foodservice procurement teams, each with distinct price sensitivity and certification expectations.

Regulations and Standards

The Fair Trade certification for coffee sold in the United Kingdom is governed by FLOCERT, the global certification body for Fairtrade International (FLO) standards. These standards mandate minimum prices, a Fair Trade premium for community investment, and requirements for democratic producer organizations and environmental protection. The certification applies to the entire supply chain from farm to the point of retail packaging, with annual audits for all certified operators. The United Kingdom’s departure from the European Union has created a separate UK organic certification regime, but Fair Trade standards remain globally harmonized, meaning no additional regulatory divergence has occurred for the ethical certification itself.

Food safety regulations under the UK Food Safety Act 1990 apply stringent residue limits for dichloromethane (DCM), a solvent used in some conventional decaffeination processes. While DCM is permitted at very low residual levels (typically no more than 2 parts per million in roasted coffee), the regulation pushes processors and roasters toward methylene chloride-free methods such as Swiss Water Processing, CO₂ extraction, and ethyl acetate processing.

Country-of-origin labeling and “Fair Trade” as a descriptor are protected terms enforced by the Competition and Markets Authority and the Advertising Standards Authority, ensuring that marketing claims are substantiated by third-party certification. Roasters must maintain full traceability documentation for all certified product batches, a requirement that creates a barrier to entry for smaller operators but protects the integrity of the category as a whole.

Market Forecast to 2035

Looking ahead to 2035, the United Kingdom Fair Trade Decaf Coffee market is poised for robust expansion, with volume projected to increase by 60–80% from 2026 levels. The compound annual growth rate (CAGR) is forecast to settle in the 6–9% range, a deceleration from the torrid 7–11% pace of the early forecast period as the category matures but still well above the mainstream coffee market growth rate. Three structural factors underpin this outlook: the aging of ethically-oriented Gen Z and millennial consumers into their peak coffee-consuming years; the continued expansion of Fair Trade Decaf SKUs in mainstream grocery and foodservice channels; and incremental improvements in decaffeination technology that narrow the taste gap between decaf and caffeinated coffee, reducing a key historical barrier to trial.

Private label is expected to capture a 25–30% volume share by 2035, up from an estimated 15–20% in 2026, as retailers refine their direct sourcing relationships with Fair Trade cooperatives and decaffeination processors. The at-home channel will remain the largest application segment, but office coffee service is forecast to grow at an above-average rate as corporate sustainability mandates expand. The premium specialty segment—single-origin, small-batch roasted, Swiss Water processed—will gain value share, potentially accounting for 40–50% of retail revenue by 2035 even if it represents only 25–35% of volume. Price sensitivity will persist, meaning growth will be steady rather than explosive, but the combination of demographic tailwinds and channel expansion provides a strong foundation for sustained long-term expansion.

Market Opportunities

Process innovation represents one of the highest-value opportunities in the United Kingdom Fair Trade Decaf market. Roasters that exclusively use Swiss Water or CO₂ decaffeination and invest in marketing the process as a feature—highlighting the “chemical-free” aspect—can capture a 15–25% price premium over products that do not specify their decaf method. Consumer awareness of decaffeination processes is rising, and transparency around the method used is becoming a purchase trigger for the ethically-conscious buyer segment. Early movers who secure long-term contracts with limited-capacity Swiss Water and CO₂ processing plants will have a supply advantage that can be leveraged in retail negotiations.

Private-label premiumization offers a significant growth avenue for UK grocery multiples. Major retailers can develop “Taste the Difference” or equivalent premium-tier Fair Trade Decaf lines, sourced directly from a single high-altitude cooperative and processed via CO₂, competing directly with specialty roasters at a lower price point while still achieving higher margins than standard private-label coffee.

Corporate sustainability gifting is an under-penetrated adjacent market: offering Fair Trade Decaf as a branded corporate gift or employee wellness perk aligns with expanding ESG mandates and provides a recurring B2B revenue stream that is less price-sensitive than retail. Finally, functional fortification—infusing Fair Trade Decaf with adaptogens, vitamins, or mushroom extracts—aligns with the United Kingdom’s booming functional FMCG trend, creating a “health-first” coffee occasion that justifies a further premium and differentiates the product from standard decaf offerings in a crowded premium aisle.

High Reach / Scale

Focused / Niche

Value / Mainstream

Premium / Differentiated

Brand examples

Private Label (e.g., Kroger Simple Truth)
Eight O’Clock Coffee

Scale + Value Leadership

Value and Private-Label Specialists
Mass-Market Portfolio Houses

Wins on reach, promo intensity, and shelf scale.

Brand examples

Peet’s Coffee
Lavazza

Scale + Premium Differentiation

Global Brand Owners and Category Leaders
Premium and Innovation-Led Challengers

Converts brand equity into price resilience and mix.

Brand examples

Cafe Altura
Equal Exchange

Focused / Value Niches

DTC and E-Commerce Native Brands
Regional Brand Houses

Plays where local execution or partner-led scale matters.

Brand examples

Counter Culture Coffee
Intelligentsia
Stumptown

Focused / Premium Growth Pockets

Value and Private-Label Specialists
Vertical integrator (farm-to-cup)

Typical white space for challengers and premium extensions.

Grocery Mass

Leading examples

Private Label
Green Mountain Coffee Roasters

The scale channel: volume, distribution, and shelf defense.

Demand Reach

Mass-market scale

Margin Quality

Tight / promo-heavy

Brand Control

Retailer-led

Specialty Grocery/Natural

Leading examples

Equal Exchange
Cafe Altura
Newman’s Own Organics

Wins where expertise, claims, and trust shape conversion.

Demand Reach

Targeted premium

Margin Quality

Higher / curated

Brand Control

Category-managed

Direct-to-Consumer (Online)

Leading examples

Trade Coffee
Atlas Coffee Club

Best for test-and-learn, premium storytelling, and retention.

Demand Reach

High growth / targeted

Margin Quality

Variable / media-led

Brand Control

High data visibility

Club

Leading examples

Kirkland Signature
Member’s Mark

This channel usually matters for controlled launches, message consistency, and premium mix.

Specialty roaster

Wins where expertise, claims, and trust shape conversion.

Demand Reach

Targeted premium

Margin Quality

Higher / curated

Brand Control

Category-managed

This report is an independent strategic category study of the market for fair trade decaf coffee in the United Kingdom. It is designed for brand owners, general managers, category leaders, trade-marketing teams, e-commerce teams, retail partners, distributors, investors, and market entrants that need a clear read on where growth sits, which brands control the category, how pricing and promotion shape demand, and which channels matter most for scale and margin.

The framework is built for packaged food & beverage markets within consumer goods, where performance is driven by need states, shopper missions, brand hierarchies, price-pack architecture, retail execution, promotional intensity, and route-to-market control rather than by a narrow technical specification alone. It defines fair trade decaf coffee as Coffee beans that have been decaffeinated and certified as Fair Trade, meeting standards for equitable pricing, labor conditions, and environmental sustainability for producers and maps the market through category boundaries, consumer segments, usage occasions, channel structure, brand and private-label positions, supply and availability logic, pricing and promotion mechanics, and country-level commercial roles. Historical analysis typically covers 2012 to 2025, with forward-looking scenarios through 2035.

What questions this report answers

This report is designed to answer the questions that matter most to brand, category, channel, and strategy teams in consumer-goods markets.

  1. Where category growth and margin pools really sit: how large the market is, which segments are growing, and which parts of the category carry the strongest commercial upside.
  2. What the category actually includes: where the scope boundary should be drawn relative to adjacent products, substitute baskets, and wider household or personal-care routines.
  3. Which commercial segments matter most: how the category should be cut by format, need state, shopper occasion, price tier, pack architecture, channel, and brand position.
  4. How shoppers enter, repeat, trade up, and switch: which need states and shopping missions create the strongest value pools, and what drives loyalty versus substitution.
  5. Which brands control volume, premium mix, and shelf power: how branded players, challengers, and private label differ in scale, positioning, channel strength, and claims authority.
  6. How pricing and promotion really work: how price ladders, pack-price logic, promotions, and channel margin structures shape revenue quality and competitive intensity.
  7. How supply and route-to-market affect performance: where manufacturing, private label, fulfillment, replenishment, and on-shelf availability create advantage or risk.
  8. Which countries and channels matter most for growth: where to build brand power, where to source or manufacture, and where the next wave of category expansion is likely to come from.
  9. Where the best white-space opportunities are: which segments, countries, channels, and assortment gaps are most attractive for entry, expansion, or portfolio repositioning.

What this report is about

At its core, this report explains how the market for fair trade decaf coffee actually works as a consumer category. It is built to show where demand comes from, which need states and shopper missions matter most, which brands and private-label players shape the category, which channels control visibility and conversion, and where pricing power, repeat purchase, and margin are actually created.

Rather than framing the category through narrow technical attributes, the study breaks it into decision-grade commercial layers: product format, benefit platform, shopper segment, purchase occasion, pack-price architecture, channel environment, promotional intensity, route-to-market control, and company archetype. It is therefore useful both for teams shaping portfolio strategy and for teams executing growth through Ethical-conscious consumers, Health-motivated consumers (caffeine-sensitive), Corporate gift buyers, Grocery category managers, and Specialty food retailers.

The report also clarifies how value pools differ across Home brewing, Office coffee service, and Premium gifting, how premiumization and private label reshape category economics, how retail concentration and route-to-market design affect scale, and which countries matter most for brand building, sourcing, packaging, and channel expansion.

Research methodology and analytical framework

The report is based on an independent market-intelligence methodology that combines category reconstruction, public company evidence, retail and channel mapping, pricing review, and multi-layer triangulation. It is built for consumer categories where no single public dataset captures the real structure of demand, brand power, promotion, and channel control.

The evidence stack typically combines company disclosures, investor materials, brand and retailer product pages, e-commerce assortment checks, packaging and claims analysis, public pricing references, trade statistics where relevant, regulatory and labeling guidance, and observable route-to-market evidence from distributors, retailers, merchandisers, and marketplace ecosystems.

The analytical model then reconstructs the category across the layers that matter commercially: category scope, shopper need states, consumer segments, pack-price ladders, brand and private-label hierarchy, channel power, promotional intensity, route-to-market design, and country role differences.

Special attention is given to Health & wellness (caffeine reduction), Ethical consumption values, Premiumization at home, Brand trust and transparency, and Third-party certification appeal. The objective is not only to size the market, but to explain where value pools sit, which segments drive mix and repeat purchase, which channels shape growth, and how leading brands defend or expand their positions across Ethical-conscious consumers, Health-motivated consumers (caffeine-sensitive), Corporate gift buyers, Grocery category managers, and Specialty food retailers.

The report does not rely on survey-based opinion as its core evidence base. Instead, it uses observable commercial signals and structured public evidence to build a decision-grade view for brand, category, retail, e-commerce, investment, and market-entry teams.

Commercial lenses used in this report

  • Need states, benefit platforms, and usage occasions: Home brewing, Office coffee service, and Premium gifting
  • Shopper segments and category entry points: Consumer household, Corporate procurement, and Hospitality (limited)
  • Channel, retail, and route-to-market structure: Ethical-conscious consumers, Health-motivated consumers (caffeine-sensitive), Corporate gift buyers, Grocery category managers, and Specialty food retailers
  • Demand drivers, repeat-purchase logic, and premiumization signals: Health & wellness (caffeine reduction), Ethical consumption values, Premiumization at home, Brand trust and transparency, and Third-party certification appeal
  • Price ladders, promo mechanics, and pack-price architecture: Commodity green bean price, Fair Trade premium, Decaffeination cost, Roasting & packaging cost, Brand premium, Retail margin, and Promotional discounting
  • Supply, replenishment, and execution watchpoints: Limited supply of certified decaf green beans, Decaffeination plant capacity & certification, Cost premium of ethical sourcing, and Complexity of maintaining dual (Fair Trade + decaf) supply chains

Product scope

This report defines fair trade decaf coffee as Coffee beans that have been decaffeinated and certified as Fair Trade, meeting standards for equitable pricing, labor conditions, and environmental sustainability for producers and treats it as a branded consumer category rather than as a narrow technical product class. The objective is to capture the real commercial market that category, brand, trade-marketing, and channel teams are managing.

Scope is determined by how the category is sold, merchandised, priced, and chosen in market. That means the report follows product formats, claims, price tiers, pack architecture, need states, and retail environments that shape Home brewing, Office coffee service, and Premium gifting.

The study deliberately separates the category from adjacent baskets when they distort the economics or shopper logic of the market being measured. Typical exclusions therefore include Non-decaffeinated Fair Trade coffee, Decaf coffee without Fair Trade certification, Instant decaf coffee (unless specified Fair Trade), Coffee pods/capsules (separate machinery-driven segment), Foodservice/bulk unpackaged sales, Ready-to-drink (RTD) coffee beverages, Specialty caffeinated coffee, Conventional decaf coffee, Tea and other hot beverages, Coffee substitutes (e.g., chicory), and Coffee brewing equipment.

Product-Specific Inclusions

  • Whole bean Fair Trade decaf coffee
  • Ground Fair Trade decaf coffee
  • Single-origin Fair Trade decaf
  • Blended Fair Trade decaf
  • Fair Trade & organic (double-certified) decaf
  • Consumer packaged goods (CPG) retail formats

Product-Specific Exclusions and Boundaries

  • Non-decaffeinated Fair Trade coffee
  • Decaf coffee without Fair Trade certification
  • Instant decaf coffee (unless specified Fair Trade)
  • Coffee pods/capsules (separate machinery-driven segment)
  • Foodservice/bulk unpackaged sales
  • Ready-to-drink (RTD) coffee beverages

Adjacent Products Explicitly Excluded

  • Specialty caffeinated coffee
  • Conventional decaf coffee
  • Tea and other hot beverages
  • Coffee substitutes (e.g., chicory)
  • Coffee brewing equipment

Geographic coverage

The report provides focused coverage of the United Kingdom market and positions United Kingdom within the wider global consumer-goods industry structure.

The geographic analysis explains local consumer demand conditions, brand and private-label balance, retail concentration, pricing tiers, import dependence, and the country’s strategic role in the wider category.

Geographic and Country-Role Logic

  • Origin: Producer countries (e.g., Peru, Colombia, Ethiopia) for certified beans
  • Processing: Countries with decaffeination plants (e.g., Canada, Germany, Mexico)
  • Consumption: High-income markets with ethical consumption trends (e.g., US, UK, Germany, Nordic countries)

Who this report is for

This study is designed for strategic and commercial users across brand-led consumer categories, including:

  • general managers, brand leaders, and portfolio teams evaluating category attractiveness, pricing power, and whitespace;
  • category managers, trade-marketing teams, retail buyers, and e-commerce teams prioritizing assortment, promotion, and channel strategy;
  • insights, shopper-marketing, and innovation teams tracking need states, occasions, pack-price ladders, claims, and competitive messaging;
  • private-label and contract-manufacturing strategists assessing entry options, retailer leverage, and supply-side positioning;
  • distributors and route-to-market teams evaluating country and channel expansion priorities;
  • investors and strategy teams benchmarking competitive structure, premiumization, revenue quality, and margin logic.

Why this approach matters in consumer categories

In many brand-driven, channel-sensitive, and consumer-demand-led markets, official trade and production statistics are not sufficient on their own to describe the true market. Product boundaries may cut across multiple tariff codes, several product categories may be bundled into the same official classification, and a meaningful share of activity may take place through customized services, captive supply, platform relationships, or technically specialized channels that are not directly visible in standard statistical datasets.

For this reason, the report is designed as a modeled strategic market study. It uses official and public evidence wherever it is reliable and scope-compatible, but it does not force the market into a purely statistical framework when doing so would reduce analytical quality. Instead, it reconstructs the market through the logic of demand, supply, technology, country roles, and company behavior.

This makes the report particularly well suited to products that are innovation-intensive, technically differentiated, capacity-constrained, platform-dependent, or commercially structured around specialized buyer-supplier relationships rather than standardized commodity trade.

Typical outputs and analytical coverage

The report typically includes:

  • historical and forecast market size;
  • consumer-demand, shopper-mission, and need-state analysis;
  • category segmentation by format, benefit platform, channel, price tier, and pack architecture;
  • brand hierarchy, private-label pressure, and competitive-structure analysis;
  • route-to-market, retail, e-commerce, and availability logic;
  • pricing, promotion, trade-spend, and revenue-quality interpretation;
  • country role mapping for brand building, sourcing, and expansion;
  • major-brand and company archetypes;
  • strategic implications for brand owners, retailers, distributors, and investors.


Source link

12 05, 2026

Silver Price Forecast: XAG/USD Rallies as Strong US Jobs Report Weakens the Dollar

By |2026-05-12T01:33:55+03:00May 12, 2026|Forex News, News|0 Comments


BitcoinWorld

Silver Price Forecast: XAG/USD Rallies as Strong US Jobs Report Weakens the Dollar

The silver market experienced a notable rally this week, with XAG/USD climbing sharply as a stronger-than-expected US jobs report paradoxically weakened the US Dollar. The move caught many traders off guard, as strong employment data typically strengthens the Dollar and pressures precious metals. However, a deeper reading of the report suggests that wage growth and labor participation rates may be signaling a shift in Federal Reserve policy expectations, prompting a rotation into safe-haven assets like silver.

What Drove the Silver Rally?

The US Bureau of Labor Statistics reported that non-farm payrolls increased by 228,000 in the previous month, well above the consensus estimate of 180,000. The unemployment rate held steady at 3.9%, while average hourly earnings rose 0.4% month-over-month, slightly above forecasts. Normally, such data would boost the Dollar as it suggests the economy can handle higher interest rates. Yet the Dollar Index (DXY) fell 0.6% on the day, its largest single-session drop in three weeks.

Analysts attribute the Dollar’s decline to a reassessment of the Fed’s rate path. While the headline jobs number was strong, the details revealed a softening in temporary hiring and a decline in average weekly hours worked — both early indicators of cooling demand. Markets interpreted this as a signal that the Fed may pause rate hikes sooner than previously expected, reducing the opportunity cost of holding non-yielding assets like silver.

Silver, often more volatile than gold due to its dual role as a monetary metal and industrial commodity, surged 2.8% to trade near $24.90 per ounce. The rally was supported by a drop in US Treasury yields, with the 10-year note falling 8 basis points to 4.12%.

Technical Outlook for XAG/USD

From a technical perspective, silver broke above its 50-day moving average at $24.50, a level that had acted as resistance for the past two weeks. The next key resistance zone lies between $25.20 and $25.50, the latter being the 200-day moving average. A sustained move above $25.50 could open the door to $26.00, a psychological level that has not been tested since early February.

On the downside, support is now established at $24.20, with stronger support at $23.80. The Relative Strength Index (RSI) on the daily chart moved to 62, indicating bullish momentum without entering overbought territory, leaving room for further upside.

What This Means for Investors

For precious metals investors, the current setup presents a mixed picture. The Dollar’s weakness provides a tailwind, but silver’s industrial demand component remains sensitive to global growth concerns. China’s manufacturing PMI data, released earlier this week, showed a slight contraction, which could cap silver’s gains if the industrial outlook deteriorates further.

However, if the Fed signals a more dovish stance at its next meeting, silver could benefit from both monetary policy expectations and renewed investor interest in hard assets. The market is now pricing in a 65% probability of a rate hold in June, up from 50% before the jobs report.

Conclusion

The silver rally following the US jobs report underscores the complexity of current market dynamics. While strong employment data typically supports the Dollar, the nuanced details of the report shifted focus toward a potential Fed pause, benefiting precious metals. Traders will watch for further economic data, particularly inflation figures and retail sales, to confirm the trend. For now, silver appears well-supported, but the path forward depends on whether the Dollar’s weakness proves temporary or signals a broader shift in investor sentiment.

FAQs

Q1: Why did silver rally on a strong jobs report?
A: While the headline jobs number was strong, details such as declining temporary hiring and reduced average weekly hours suggested a cooling labor market. This led markets to anticipate a potential Fed pause on rate hikes, weakening the Dollar and boosting silver.

Q2: What are the key resistance levels for silver?
A: The next key resistance is at $25.20 to $25.50, with the 200-day moving average near $25.50. A break above $25.50 could target $26.00.

Q3: Is silver a good investment right now?
A: Silver benefits from a weaker Dollar and potential Fed dovishness, but industrial demand risks from global growth slowdowns remain. Investors should consider their risk tolerance and monitor upcoming economic data for confirmation of the trend.

This post Silver Price Forecast: XAG/USD Rallies as Strong US Jobs Report Weakens the Dollar first appeared on BitcoinWorld.


Source link

11 05, 2026

Forecast update for EURUSD -11-05-2026.

By |2026-05-11T21:32:50+03:00May 11, 2026|Forex News, News|0 Comments


Natural gas price continued providing weak sideways trading due to the contradiction of the main indicators, to keep delaying the negative trend due to the stability above the extra support at $2.620.


Stochastic surpass to 50 level might push the price to form some temporary bullish waves, attempting to reach $3.000 level, to retest $3.200, while breaking the previously mentioned support and holding below it will force it to suffer extra losses by reaching $2.390 followed by the next main target at $2.250.


The expected trading range for today is between $2.700 and $2.950


Trend forecast: Fluctuating


Source link

11 05, 2026

Platinum price without any news– Forecast today – 11-5-2026

By |2026-05-11T17:32:23+03:00May 11, 2026|Forex News, News|0 Comments


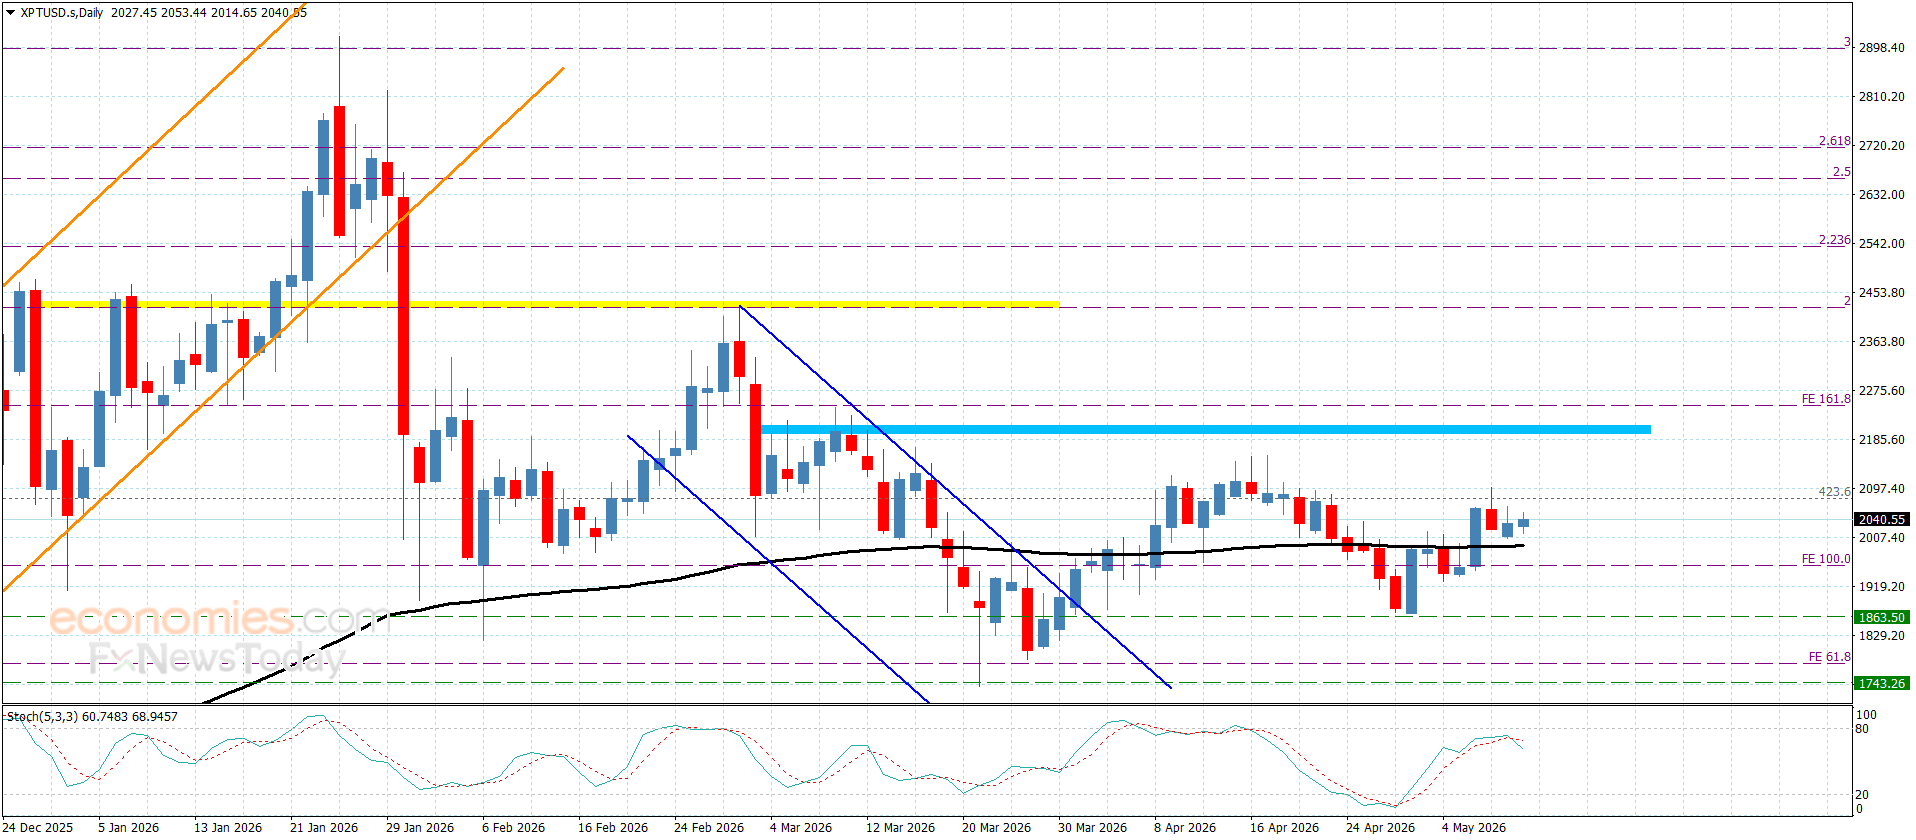
Platinum price is forced to provide weak sideways trading, affected by the stability of $2080.00 barrier, which obstructs the chances of resuming the bullish attempts, to fluctuate near $2035.00, attempting to lean above the moving average 55.


Note that the stability above the main support at $1865.00, the continuation of the attempt of forming extra support at $1950.00 level, these factors make us keep the bullish scenario, to keep waiting for surpassing the mentioned barrier, to begin recording extra gains by its rally towards $2125.00 and $2190.00.


The expected trading range for today is between $1975.00 and $2080.00


Trend forecast: Sideways


Source link

11 05, 2026

Coffee prices today 11. 5: Slight decrease

By |2026-05-11T13:29:52+03:00May 11, 2026|Forex News, News|0 Comments


Source link

11 05, 2026

Current price of oil as of May 8, 2026

By |2026-05-11T05:28:21+03:00May 11, 2026|Forex News, News|0 Comments


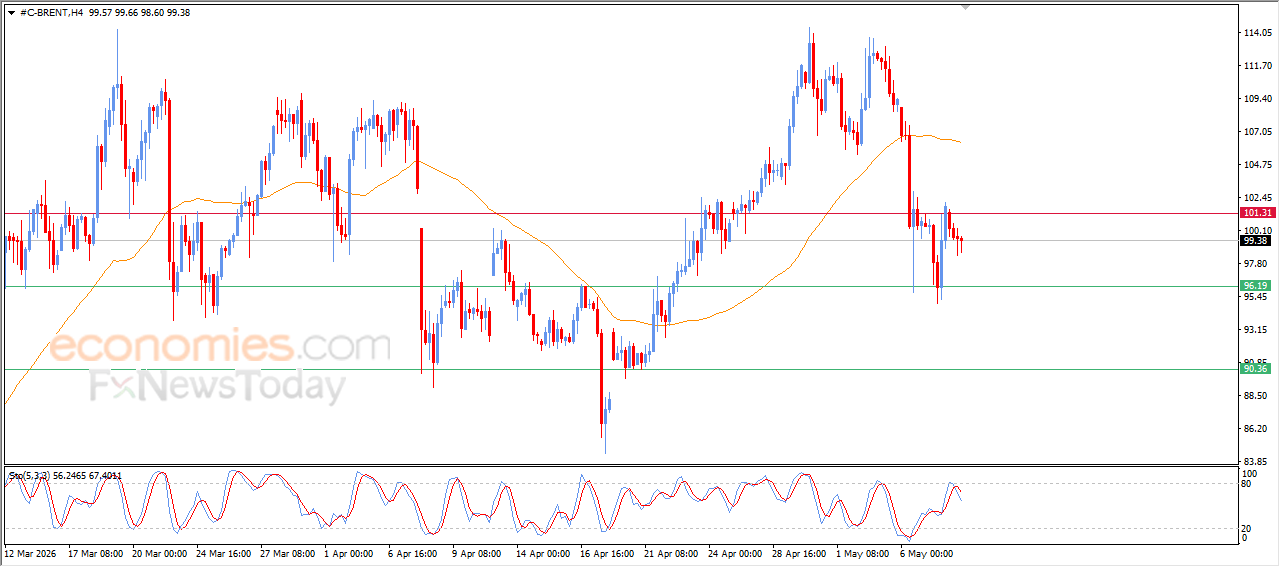
At 9 a.m. Eastern Time today, oil was priced at $104.07 per barrel with Brent serving as the benchmark (we’ll explain different benchmarks later in this article). That’s a gain of $3.62 compared with yesterday morning and around $40 higher than the price one year ago.

Oil price per barrel % Change
Price of oil yesterday $100.45 +3.60%
Price of oil 1 month ago $105.84 -1.67%
Price of oil 1 year ago $63.74 -63.27%
Price of oil yesterday
Oil price per barrel $100.45
% Change +3.60%
Price of oil 1 month ago
Oil price per barrel $105.84
% Change -1.67%
Price of oil 1 year ago
Oil price per barrel $63.74
% Change -63.27%

Will oil prices go up?

It’s impossible to forecast oil prices with detailed precision. Many different elements affect the market, but ultimately it boils down to supply and demand. When worries about economic recession, war, and other large-scale disruptions increase, oil’s path can shift fast.

How oil prices translate to gas pump prices

Gas prices at the pump don’t only track crude oil. They also include what it takes to refine and move that fuel, the taxes layered on top, and the extra markup your local station adds to stay in business.

Since crude oil generally makes up a majority of the per-gallon cost, changes in its price have an outsized impact. When oil surges, gas prices typically rise in tandem. But when oil retreats, gas prices often lag on the way down, a trend sometimes described as “rockets and feathers.”

The role of the U.S. Strategic Petroleum Reserve

In case of emergency, the U.S. has a store of crude oil known as the Strategic Petroleum Reserve. Its primary purpose is energy security in case of disaster (think sanctions, severe storm damage, even war). But it can also go a long way toward softening crippling price hikes during supply shocks.

It’s not a long-term answer and is more meant to provide temporary relief, assisting consumers and keeping critical parts of the economy running, like key industries, emergency services, public transportation, etc.

How oil and natural gas prices are linked

Both oil and natural gas are key sources of the energy we use every day. Because of this, a big change in oil prices can affect natural gas. For example, if oil prices increase, some industries may swap natural gas for some segments of their operations where possible, which increases demand for natural gas.

Historical performance of oil

To gauge oil’s performance, we often turn to two benchmarks:

  • Brent crude oil, the main global oil benchmark.
  • West Texas Intermediate (WTI), the main benchmark of North America

Between these two, Brent better represents global oil performance because it prices much of the world’s traded crude. And, it’s often the best way to track historical oil performance. In fact, even the U.S. Energy Information Administration now uses Brent as its primary reference in its Annual Energy Outlook.

Looking at the Brent benchmark across several decades, oil has been anything but steady. It’s seen spikes due to factors such as wars and supply cuts, and it’s also seen crashes from global recessions and an oversupply (called a “glut”). For example:

  • The early 1970s brought the first big oil shock when the Middle East cut exports and imposed an embargo on the U.S. and others during the Yom Kippur War.
  • Prices dropped in the mid-1980s for reasons such as lower demand and more non-OPEC oil producers entering the industry.
  • Prices spiked again in 2008 with increased global demand, but it soon plummeted alongside the global financial crisis.
  • During the 2020 COVID lockdown, oil demand collapsed like never before—bringing prices below $20 per barrel.

All to say, oil’s historical performance has been anything but smooth. Again, it’s hugely affected by wars, recessions, OPEC whims, evolving energy initiatives and policies, and much more.

Energy coverage from Fortune

Looking to stay up-to-date regarding the latest energy developments? Check out our recent coverage:

Frequently asked questions

How is the current price of oil per barrel actually determined?

The current price of oil per barrel depends largely on supply and demand, including news about potential future supply and demand (geopolitics, decisions made by OPEC+, etc.). In the U.S., prices also move based on how friendly an administration is to drilling, as it can affect future supply. For example, 2025 saw the Trump administration move to reopen more than 1.5 million acres in the Coastal Plain of the Arctic National Wildlife Refuge for oil and gas leasing, reversing the Biden administration’s policy of limiting oil drilling in the Arctic.

How often does the price of oil change during the day?

The price of oil updates constantly when the “futures” markets are open. A futures market is effectively an auction where people agree to buy or sell oil in the future. As long as people and companies are trading contracts, the oil price is changing.

How does U.S. shale oil production affect the current price of oil?

In short, shale is rock that contains oil and natural gas. Think of shale as energy yet to be tapped. The more shale the U.S. accesses, the more energy we’ll have—and the more easily oil prices can keep from spiking as much thanks to a greater supply.

How does the current price of oil impact inflation and the broader economy?

When oil is expensive, it tends to make everyday items cost more. This can be related to energy (your heating, gas utilities, etc.), but it’s also due to the logistics involved with making those items accessible to you. Shipping, for example, can affect the price of things at the grocery store, as it’s more expensive to get those products from warehouses and farms onto the shelf.


Source link

11 05, 2026

Silver Price Forecast: XAG/USD rallies on strong US jobs, weak Dollar

By |2026-05-11T01:27:16+03:00May 11, 2026|Forex News, News|0 Comments


Silver (XAG/USD) trades around $80.70 on Friday at the time of writing, up 2.98% on the day, supported by a weaker US Dollar (USD) and persistent demand for safe-haven assets amid heightened geopolitical tensions.

The United States (US) Bureau of Labor Statistics (BLS) reported that Nonfarm Payrolls (NFP) increased by 115K in April, beating market expectations of 62K. March’s figure was also revised higher to 185K from 178K previously reported. The Unemployment Rate remained steady at 4.3%, while annual wage growth accelerated to 3.6%, although it came in below expectations of 3.8%.

Despite the stronger-than-expected labor market data, the US Dollar weakens as markets focus on optimism surrounding a potential agreement between Washington and Tehran and improving risk sentiment across Equity markets.

At the same time, investors remain focused on developments in the Middle East after reports of new military strikes near the Strait of Hormuz. According to US and Iranian media outlets, explosions were heard in the region as exchanges of fire between the US and Iran continue to fuel fears of a broader escalation.

This backdrop continues to support precious metals, with Silver benefiting both from its safe-haven appeal and from the weakness of the US Dollar, which increases the attractiveness of USD-denominated commodities for international buyers.

Silver FAQs

Silver is a precious metal highly traded among investors. It has been historically used as a store of value and a medium of exchange. Although less popular than Gold, traders may turn to Silver to diversify their investment portfolio, for its intrinsic value or as a potential hedge during high-inflation periods. Investors can buy physical Silver, in coins or in bars, or trade it through vehicles such as Exchange Traded Funds, which track its price on international markets.

Silver prices can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can make Silver price escalate due to its safe-haven status, although to a lesser extent than Gold’s. As a yieldless asset, Silver tends to rise with lower interest rates. Its moves also depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAG/USD). A strong Dollar tends to keep the price of Silver at bay, whereas a weaker Dollar is likely to propel prices up. Other factors such as investment demand, mining supply – Silver is much more abundant than Gold – and recycling rates can also affect prices.

Silver is widely used in industry, particularly in sectors such as electronics or solar energy, as it has one of the highest electric conductivity of all metals – more than Copper and Gold. A surge in demand can increase prices, while a decline tends to lower them. Dynamics in the US, Chinese and Indian economies can also contribute to price swings: for the US and particularly China, their big industrial sectors use Silver in various processes; in India, consumers’ demand for the precious metal for jewellery also plays a key role in setting prices.

Silver prices tend to follow Gold’s moves. When Gold prices rise, Silver typically follows suit, as their status as safe-haven assets is similar. The Gold/Silver ratio, which shows the number of ounces of Silver needed to equal the value of one ounce of Gold, may help to determine the relative valuation between both metals. Some investors may consider a high ratio as an indicator that Silver is undervalued, or Gold is overvalued. On the contrary, a low ratio might suggest that Gold is undervalued relative to Silver.


Source link

10 05, 2026

Forecast update for Brent -08-05-2026

By |2026-05-10T21:25:58+03:00May 10, 2026|Forex News, News|0 Comments


Meta Platforms, Inc. (META) stock price advanced in its latest intraday trading, as the stock attempts through this rise to recover part of its previous losses, while also trying to relieve some of its clear oversold condition on the Stochastic indicators, especially with the emergence of positive signals from them, before encountering resistance at its 50-day SMA, amid the dominance of a medium-term corrective bearish trend.


Therefore we expect the stock price to decline in its upcoming trading, as long as it remains below the $653.85 resistance level, targeting the first support level at $575.20.


Today’s price forecast: Neutral


Source link

10 05, 2026

German THE Natural Gas Daily Financial Futures (ICIS) (01 Jun 2026) Trade Ideas — ICEENDEX:TGN01M2026 — TradingView

By |2026-05-10T17:24:45+03:00May 10, 2026|Forex News, News|0 Comments


Source link

10 05, 2026

Fair Trade Decaf Coffee Market in Brazil | Report – IndexBox

By |2026-05-10T13:23:42+03:00May 10, 2026|Forex News, News|0 Comments


Brazil Fair Trade Decaf Coffee Market 2026 Analysis and Forecast to 2035

Executive Summary

Key Findings

  • High-Growth Premium Niche: The Brazil Fair Trade Decaf Coffee market is expanding at an estimated compound annual growth rate (CAGR) of 9% to 14% through 2035, significantly outpacing the broader domestic coffee category. This growth is fueled by converging health-conscious and ethical consumption trends among Brazil’s urban upper-middle class, though the segment represents less than 5% of total specialty coffee volume.
  • Structural Import Dependence for Processing: Despite Brazil being the world’s largest green coffee producer, the market for processed Fair Trade Decaf is structurally dependent on international decaffeination supply chains, primarily in Canada and Germany. This re-import model creates a cost premium of 25% to 40% over conventional Fair Trade coffee, limiting mass-market accessibility.
  • Arabica Dominance in Premium Channels: Arabica beans command an estimated 85% to 90% share of the certified decaf segment, prized for superior flavor retention post-processing. Robusta and Blended variants are largely confined to private-label and office coffee service (OCS) channels, where cost sensitivity is higher and flavor profiles are less demanding.

Market Trends

  • Premium Home Brewing Ecosystem: The post-pandemic normalization of hybrid work has cemented a “home barista” culture in major urban centers like São Paulo and Rio de Janeiro. This has driven demand for single-origin Fair Trade Decaf beans specifically marketed for pour-over, espresso, and AeroPress methods, demanding higher clarity and acidity retention from the decaffeination process.
  • CO2 and Swiss Water Process Preference: A clear segmentation is emerging around decaffeination methods. The Carbon Dioxide (CO2) and Swiss Water Processes are perceived as “chemical-free” and superior in flavor preservation, capturing an estimated 20% to 25% of the premium ethical decaf segment. This trend mirrors the global shift toward minimally processed, label-friendly food and beverage products.
  • Direct-Trade Vertical Integration: A growing number of specialty roasters are bypassing traditional importers to establish direct-trade agreements with Fair Trade cooperatives in origin countries. This allows roasters to secure traceable, high-grade lots specifically designated for decaffeination, ensuring supply chain transparency and stronger narratives for brand differentiation in a crowded premium space.

Key Challenges

  • Cost Complexity and Price Sensitivity: The additive cost of Fair Trade certification premiums, international decaffeination fees, and specialty logistics creates a retail price point for roasted beans that is 60% to 80% higher than conventional specialty coffee. This severely restricts market penetration in a price-conscious domestic market and creates a high barrier to trial for curious consumers.
  • Global Decaffeination Capacity Bottlenecks: The market is constrained by limited global capacity at certified decaffeination plants. Securing processing slots requires long lead times (6 to 12 months) and significant advance planning. This lack of agility creates inventory management challenges for Brazilian roasters and importers, often leading to out-of-stock situations for high-demand SKUs.
  • Certification Proliferation and Consumer Confusion: The ethical consumption space in Brazil is increasingly crowded with certifications, including Rainforest Alliance, Organic (USDA/EU), B-Corp, and various local sustainability seals. This proliferation dilutes the distinct “Fair Trade” value proposition, requiring roasters to invest heavily in educational marketing to justify the premium associated with the FLO label specifically.

Market Overview

Brazil’s Fair Trade Decaf Coffee market operates at the intersection of the country’s deep-rooted coffee culture and the globalized supply chain for specialty processed goods. While Brazil is a powerhouse of coffee production, the specific sub-market for Fair Trade Decaf is a paradox: it relies heavily on international logistics to transform locally grown green beans into a premium finished product. The market serves a distinct consumer archetype who is both health-motivated (caffeine-sensitive) and ethically engaged.

This buyer is typically an educated, high-income urbanite who views their coffee purchase as a statement of personal and environmental values. The product itself is a tangible high-end grocery item, often sold in sophisticated packaging that emphasizes its certification logos, origin story, and decaffeination method. The category is characterized by high price elasticity at the retail shelf, strong brand loyalty driven by trust in certification, and a supply chain that is unusually complex for a domestic coffee product, involving international partners for processing.

This complexity creates a natural barrier to entry for small players but offers significant differentiation opportunities for brands that can master the logistics and storytelling involved.

Market Size and Growth

Quantifying the exact volume of the Brazil Fair Trade Decaf Coffee market is challenging due to its niche status within the broader coffee import and processing data, but industry proxies point to robust expansion. The segment is growing at a pace three to four times that of the mainstream domestic coffee market, with a projected CAGR in the range of 9% to 14% between 2026 and 2035. This growth is driven primarily by value, as rising certification and energy costs push prices upward, but volume is also expanding steadily.

By the end of the forecast horizon in 2035, the market volume is likely to double or even triple compared to its 2026 base, contingent on the expansion of global decaffeination capacity and continued economic stability in Brazil’s consumer class. The market’s value is disproportionately concentrated in the premium home-consumption segment, which generates the highest revenue per kilogram. The B2B office and corporate gifting segments, while smaller, offer the fastest growth rates due to corporate sustainability commitments and wellness programs.

Despite this rapid expansion, the category will likely retain its niche status, penetrating perhaps 4% to 6% of Brazilian households by 2035, up from less than 2% currently.

Demand by Segment and End Use

By Bean Type: Arabica beans overwhelmingly dominate the Fair Trade Decaf segment, accounting for an estimated 85% to 90% of retail and foodservice volume. The superior flavor complexity of Arabica, particularly when subjected to gentle decaffeination processes, justifies the premium price. Blended products (Arabica/Robusta) represent a smaller, value-oriented segment (5% to 10%), often used in pre-ground “house blend” formats for office coffee services. Pure Robusta Fair Trade Decaf constitutes less than 5% of the market, typically utilized in instant coffee mixes or high-caffeine espresso shots for the corporate market where cost and caffeine kick are prioritized over flavor.

By End Use: At-home consumption is the largest and most lucrative end-use segment, capturing 60% to 70% of total volume. This channel is driven by the “home barista” trend and the desire for ritual. Office and workplace coffee service (OCS) constitutes 20% to 25% of volume, driven by corporate policies aimed at employee wellness and ESG (Environmental, Social, and Governance) targets. Premium gifting is a strategically vital segment, representing 10% to 15% of volume but a comparably higher share of value (20% to 25%) due to premium packaging and higher margins. Gift buyers are highly receptive to the narrative of ethical sourcing and health benefits, making this a key entry point for new consumers.

By Value Chain: Specialty roasters are the primary market makers, holding an estimated 50% to 60% share of the branded segment. Certified importer/brand owners capture 25% to 30%, while private-label retail brands are a growing force, holding 10% to 20% as supermarket chains seek to offer exclusive ethical product lines.

Prices and Cost Drivers

The pricing structure for Fair Trade Decaf Coffee in Brazil is multi-layered and reflects a significant “premium-on-premium” dynamic. The foundation is the commodity green bean price, which is highly volatile. On top of this, the Fair Trade premium (typically $0.20 to $0.40 per lb FOB) guarantees a minimum price to producers. The largest cost differentiator is the decaffeination process itself. The Swiss Water Process and CO2 Process add a substantial $0.80 to $1.50 per lb to the cost of green beans, reflecting the technology and logistics involved.

Roasting, packaging, and brand storytelling add another 100% to 150% markup over the landed cost of processed green beans. At the retail shelf, this complex cost chain results in a price point of R$60 to R$100 for a standardized 250g bag of whole-bean Fair Trade Decaf. This compares to R$25 to R$40 for a comparable bag of non-certified specialty coffee. Macro drivers include energy costs for roasting, international freight rates, and the BRL-USD exchange rate, which directly impacts the cost of imported decaf beans and re-imported Brazilian beans.

Promotional discounting is minimal and tactical due to tight margins, with roasters instead relying on subscription models to stabilize demand and reduce churn.

Suppliers, Manufacturers and Competition

The competitive landscape is a fragmented mix of global FMCG brand owners, agile local specialty roasters, and niche importers. Global brand owners participate in the category through dedicated premium SKUs, leveraging their extensive distribution networks to place Fair Trade Decaf in mainstream grocery channels. Their scale allows them to negotiate better terms on decaffeination processing slots. The heart of the market, however, lies with the specialty roaster segment. These companies compete fiercely on flavor profile, the transparency of their supply chain, and the specific certifications they hold (e.g., USDA Organic + Fair Trade).

They often rely on importers who specialize in ethical and certified green beans to navigate the complexity of sourcing from multiple origin countries. Private-label specialists are an emerging force, producing for supermarket chains and online retailers seeking to capture the ethical consumer with an exclusive brand. Competition is not primarily price-based; it revolves around trust, origin storytelling, and the quality of the cup post-decaffeination.

Wholesalers and distributors act as critical intermediaries, particularly for the B2B office coffee service (OCS) segment, where they bundle Fair Trade Decaf with conventional offerings to create a comprehensive portfolio for corporate clients.

Domestic Production and Supply

Brazil’s role in the Fair Trade Decaf supply chain is deeply paradoxical: it is the world’s largest producer of green coffee, yet its domestic production of the final processed product is minimal. The bottleneck is decaffeination infrastructure. While Brazil has some capacity for Ethyl Acetate (EA) decaffeination, a process often derived from sugar cane, the higher-quality Swiss Water Process and CO2 Process facilities are located overseas, primarily in Canada, Germany, and Mexico.

Most Brazilian roasters depend on a “send-and-receive” model: exporting high-grade Fair Trade certified green beans to these international processors for decaffeination, then re-importing the processed beans. This creates a supply chain that is geographically stretched, capital-intensive, and subject to long lead times. A small but growing portion of the market utilizes imported processed green beans from other origins like Colombia or Ethiopia to offer variety.

The lack of advanced domestic decaffeination capacity is a structural weakness of the market, keeping prices high and limiting the agility of local suppliers to respond to sudden demand spikes. Investment in a local, high-capacity, multi-process decaffeination plant would be a transformative event for the Brazilian market.

Imports, Exports and Trade

The trade flows for Brazil Fair Trade Decaf Coffee involve a complex re-import loop that distinguishes it from conventional coffee trade. Brazil exports massive volumes of green coffee (HS 0901.11) globally. A small, specialized fraction of these exports are high-grade, Fair Trade certified beans destined for decaffeination plants. These beans are processed in Canada, Germany, or Mexico using the Swiss Water or CO2 methods. The resulting decaffeinated green beans are then re-imported into Brazil under HS code 0901.22 (Roasted, Decaffeinated) or 0901.12 (Green, Decaffeinated).

This circular trade is costly but necessary to access preferred processing technology. In addition to re-imports, Brazil imports smaller volumes of ready-processed Fair Trade Decaf beans from other origin countries to diversify its product offering. The “Fair Trade” component is invisible in standard customs data, which tracks only the physical coffee and process, not the certification status. This makes the market opaque to conventional trade analysis, but industry sourcing patterns and certification audits confirm the dominance of the re-import supply model.

Brazil’s strong trade surplus in green coffee is slightly offset by these targeted imports of processed decaf beans.

Distribution Channels and Buyers

Retail: The primary physical retail channels for Fair Trade Decaf in Brazil are high-end supermarket chains (e.g., St. Marché, Zaffari) and specialty gourmet food stores. These physical stores offer high visibility and the opportunity for in-person education about certifications and flavor profiles. E-commerce and Direct-to-Consumer (DTC) channels are the fastest-growing segment, capturing an estimated 25% to 30% of premium sales. DTC allows roasters to offer subscription models, detailed origin stories, and higher margins by bypassing the retailer.

B2B and Foodservice: Office Coffee Service (OCS) distributors are key buyers in this channel, procuring Fair Trade Decaf for corporate break rooms. Corporate procurement managers are a distinct buyer group, motivated by employee satisfaction, wellness initiatives, and ESG reporting. Hospitality (hotels, high-end restaurants) represents a limited but high-margin end-use sector, typically requiring specific packaging formats (e.g., Nespresso-compatible pods, drip bags).

Buyer Groups: The primary consumer buyer groups are ethical-conscious consumers and health-motivated individuals (caffeine-sensitive). These groups overlap significantly. Another influential buyer group is grocery category managers at premium retailers, who see Fair Trade Decaf as a key differentiator for their store brand or specialty aisle.

Regulations and Standards

The market is heavily governed by certification standards and food safety regulations. Fair Trade International (FLO) standards set the baseline for the certification label, imposing minimum pricing, a social premium for producer cooperatives, and specific labor and environmental standards. Operators in Brazil must maintain certified supply chain traceability from the cooperative to the final packager. ANVISA (Brazilian Health Regulatory Agency) regulates the product category, enforcing labeling laws that require clear declaration of ingredients, origin, and caffeine content.

By law, decaf coffee delivered to the consumer must have a caffeine content less than 0.1% on a dry basis. Many Fair Trade Decaf products in Brazil also carry USDA Organic or EU Organic certifications, as the overlap between organic and fair-trade farming practices is significant. This dual certification adds further cost but also enhances the product’s credibility. Country-of-origin labeling regulations require clear distinction between a product grown in Brazil and one that was only processed there, which is a critical factor for the “re-import” supply chain.

Labeling of the decaffeination method (e.g., Swiss Water, CO2) is voluntary but increasingly used as a premium differentiator.

Market Forecast to 2035

Looking ahead to 2035, the Brazil Fair Trade Decaf Coffee market is expected to maintain a healthy growth trajectory, though it will likely remain a high-value niche rather than transitioning into a mass-market segment. Volume growth is forecast to compound at 8% to 10% annually, while value growth is projected to run slightly higher, in the range of 10% to 13% annually, driven by persistent inflation in certification and energy costs, as well as ongoing product premiumization. A key variable influencing the forecast is the potential investment in domestic decaffeination capacity.

If a major Swiss Water or CO2 facility were established in Brazil, the reduction in logistics costs could lower retail prices by 15% to 25%, potentially doubling the addressable market by 2035. Conversely, continued reliance on overseas processing will maintain high price barriers, keeping household penetration below 6%. The competitive landscape will likely see consolidation, with larger roasters and brand owners acquiring smaller ethical brands to stabilize their supply chains and capture the growing segment.

The consumer base will broaden slightly, moving from the top 5% income bracket to the top 15% as “conscious consumption” becomes more mainstream.

Market Opportunities

Domestic Decaffeination Infrastructure: The single greatest opportunity lies in building a state-of-the-art, multi-process decaffeination plant within Brazil. This would bypass the costly and time-consuming re-import loop, allowing Brazilian roasters to offer a “Brazilian Origin” Fair Trade Decaf at a significantly lower price point, dramatically expanding the potential consumer base.

Subscription and DTC Model Optimization: The DTC channel is still under-penetrated relative to its potential. Sophisticated subscription models that offer blending customization, flavor profiling based on brewing method, and educational content about the Fair Trade impact can build high customer lifetime value and stabilize forecasting, directly addressing the supply chain problem of long lead times.

Innovative Product Formats: There is a clear gap in the market for high-quality, single-serve Fair Trade Decaf capsules compatible with the popular Nespresso and Dolce Gusto systems. Developing a certified, compostable pod format for the at-home office market could unlock a large volume of demand among busy professionals seeking convenience without compromising their ethical or health values.

High Reach / Scale

Focused / Niche

Value / Mainstream

Premium / Differentiated

Brand examples

Private Label (e.g., Kroger Simple Truth)
Eight O’Clock Coffee

Scale + Value Leadership

Value and Private-Label Specialists
Mass-Market Portfolio Houses

Wins on reach, promo intensity, and shelf scale.

Brand examples

Peet’s Coffee
Lavazza

Scale + Premium Differentiation

Global Brand Owners and Category Leaders
Premium and Innovation-Led Challengers

Converts brand equity into price resilience and mix.

Brand examples

Cafe Altura
Equal Exchange

Focused / Value Niches

DTC and E-Commerce Native Brands
Regional Brand Houses

Plays where local execution or partner-led scale matters.

Brand examples

Counter Culture Coffee
Intelligentsia
Stumptown

Focused / Premium Growth Pockets

Value and Private-Label Specialists
Vertical integrator (farm-to-cup)

Typical white space for challengers and premium extensions.

Grocery Mass

Leading examples

Private Label
Green Mountain Coffee Roasters

The scale channel: volume, distribution, and shelf defense.

Demand Reach

Mass-market scale

Margin Quality

Tight / promo-heavy

Brand Control

Retailer-led

Specialty Grocery/Natural

Leading examples

Equal Exchange
Cafe Altura
Newman’s Own Organics

Wins where expertise, claims, and trust shape conversion.

Demand Reach

Targeted premium

Margin Quality

Higher / curated

Brand Control

Category-managed

Direct-to-Consumer (Online)

Leading examples

Trade Coffee
Atlas Coffee Club

Best for test-and-learn, premium storytelling, and retention.

Demand Reach

High growth / targeted

Margin Quality

Variable / media-led

Brand Control

High data visibility

Club

Leading examples

Kirkland Signature
Member’s Mark

This channel usually matters for controlled launches, message consistency, and premium mix.

Specialty roaster

Wins where expertise, claims, and trust shape conversion.

Demand Reach

Targeted premium

Margin Quality

Higher / curated

Brand Control

Category-managed

This report is an independent strategic category study of the market for fair trade decaf coffee in Brazil. It is designed for brand owners, general managers, category leaders, trade-marketing teams, e-commerce teams, retail partners, distributors, investors, and market entrants that need a clear read on where growth sits, which brands control the category, how pricing and promotion shape demand, and which channels matter most for scale and margin.

The framework is built for packaged food & beverage markets within consumer goods, where performance is driven by need states, shopper missions, brand hierarchies, price-pack architecture, retail execution, promotional intensity, and route-to-market control rather than by a narrow technical specification alone. It defines fair trade decaf coffee as Coffee beans that have been decaffeinated and certified as Fair Trade, meeting standards for equitable pricing, labor conditions, and environmental sustainability for producers and maps the market through category boundaries, consumer segments, usage occasions, channel structure, brand and private-label positions, supply and availability logic, pricing and promotion mechanics, and country-level commercial roles. Historical analysis typically covers 2012 to 2025, with forward-looking scenarios through 2035.

What questions this report answers

This report is designed to answer the questions that matter most to brand, category, channel, and strategy teams in consumer-goods markets.

  1. Where category growth and margin pools really sit: how large the market is, which segments are growing, and which parts of the category carry the strongest commercial upside.
  2. What the category actually includes: where the scope boundary should be drawn relative to adjacent products, substitute baskets, and wider household or personal-care routines.
  3. Which commercial segments matter most: how the category should be cut by format, need state, shopper occasion, price tier, pack architecture, channel, and brand position.
  4. How shoppers enter, repeat, trade up, and switch: which need states and shopping missions create the strongest value pools, and what drives loyalty versus substitution.
  5. Which brands control volume, premium mix, and shelf power: how branded players, challengers, and private label differ in scale, positioning, channel strength, and claims authority.
  6. How pricing and promotion really work: how price ladders, pack-price logic, promotions, and channel margin structures shape revenue quality and competitive intensity.
  7. How supply and route-to-market affect performance: where manufacturing, private label, fulfillment, replenishment, and on-shelf availability create advantage or risk.
  8. Which countries and channels matter most for growth: where to build brand power, where to source or manufacture, and where the next wave of category expansion is likely to come from.
  9. Where the best white-space opportunities are: which segments, countries, channels, and assortment gaps are most attractive for entry, expansion, or portfolio repositioning.

What this report is about

At its core, this report explains how the market for fair trade decaf coffee actually works as a consumer category. It is built to show where demand comes from, which need states and shopper missions matter most, which brands and private-label players shape the category, which channels control visibility and conversion, and where pricing power, repeat purchase, and margin are actually created.

Rather than framing the category through narrow technical attributes, the study breaks it into decision-grade commercial layers: product format, benefit platform, shopper segment, purchase occasion, pack-price architecture, channel environment, promotional intensity, route-to-market control, and company archetype. It is therefore useful both for teams shaping portfolio strategy and for teams executing growth through Ethical-conscious consumers, Health-motivated consumers (caffeine-sensitive), Corporate gift buyers, Grocery category managers, and Specialty food retailers.

The report also clarifies how value pools differ across Home brewing, Office coffee service, and Premium gifting, how premiumization and private label reshape category economics, how retail concentration and route-to-market design affect scale, and which countries matter most for brand building, sourcing, packaging, and channel expansion.

Research methodology and analytical framework

The report is based on an independent market-intelligence methodology that combines category reconstruction, public company evidence, retail and channel mapping, pricing review, and multi-layer triangulation. It is built for consumer categories where no single public dataset captures the real structure of demand, brand power, promotion, and channel control.

The evidence stack typically combines company disclosures, investor materials, brand and retailer product pages, e-commerce assortment checks, packaging and claims analysis, public pricing references, trade statistics where relevant, regulatory and labeling guidance, and observable route-to-market evidence from distributors, retailers, merchandisers, and marketplace ecosystems.

The analytical model then reconstructs the category across the layers that matter commercially: category scope, shopper need states, consumer segments, pack-price ladders, brand and private-label hierarchy, channel power, promotional intensity, route-to-market design, and country role differences.

Special attention is given to Health & wellness (caffeine reduction), Ethical consumption values, Premiumization at home, Brand trust and transparency, and Third-party certification appeal. The objective is not only to size the market, but to explain where value pools sit, which segments drive mix and repeat purchase, which channels shape growth, and how leading brands defend or expand their positions across Ethical-conscious consumers, Health-motivated consumers (caffeine-sensitive), Corporate gift buyers, Grocery category managers, and Specialty food retailers.

The report does not rely on survey-based opinion as its core evidence base. Instead, it uses observable commercial signals and structured public evidence to build a decision-grade view for brand, category, retail, e-commerce, investment, and market-entry teams.

Commercial lenses used in this report

  • Need states, benefit platforms, and usage occasions: Home brewing, Office coffee service, and Premium gifting
  • Shopper segments and category entry points: Consumer household, Corporate procurement, and Hospitality (limited)
  • Channel, retail, and route-to-market structure: Ethical-conscious consumers, Health-motivated consumers (caffeine-sensitive), Corporate gift buyers, Grocery category managers, and Specialty food retailers
  • Demand drivers, repeat-purchase logic, and premiumization signals: Health & wellness (caffeine reduction), Ethical consumption values, Premiumization at home, Brand trust and transparency, and Third-party certification appeal
  • Price ladders, promo mechanics, and pack-price architecture: Commodity green bean price, Fair Trade premium, Decaffeination cost, Roasting & packaging cost, Brand premium, Retail margin, and Promotional discounting
  • Supply, replenishment, and execution watchpoints: Limited supply of certified decaf green beans, Decaffeination plant capacity & certification, Cost premium of ethical sourcing, and Complexity of maintaining dual (Fair Trade + decaf) supply chains

Product scope

This report defines fair trade decaf coffee as Coffee beans that have been decaffeinated and certified as Fair Trade, meeting standards for equitable pricing, labor conditions, and environmental sustainability for producers and treats it as a branded consumer category rather than as a narrow technical product class. The objective is to capture the real commercial market that category, brand, trade-marketing, and channel teams are managing.

Scope is determined by how the category is sold, merchandised, priced, and chosen in market. That means the report follows product formats, claims, price tiers, pack architecture, need states, and retail environments that shape Home brewing, Office coffee service, and Premium gifting.

The study deliberately separates the category from adjacent baskets when they distort the economics or shopper logic of the market being measured. Typical exclusions therefore include Non-decaffeinated Fair Trade coffee, Decaf coffee without Fair Trade certification, Instant decaf coffee (unless specified Fair Trade), Coffee pods/capsules (separate machinery-driven segment), Foodservice/bulk unpackaged sales, Ready-to-drink (RTD) coffee beverages, Specialty caffeinated coffee, Conventional decaf coffee, Tea and other hot beverages, Coffee substitutes (e.g., chicory), and Coffee brewing equipment.

Product-Specific Inclusions

  • Whole bean Fair Trade decaf coffee
  • Ground Fair Trade decaf coffee
  • Single-origin Fair Trade decaf
  • Blended Fair Trade decaf
  • Fair Trade & organic (double-certified) decaf
  • Consumer packaged goods (CPG) retail formats

Product-Specific Exclusions and Boundaries

  • Non-decaffeinated Fair Trade coffee
  • Decaf coffee without Fair Trade certification
  • Instant decaf coffee (unless specified Fair Trade)
  • Coffee pods/capsules (separate machinery-driven segment)
  • Foodservice/bulk unpackaged sales
  • Ready-to-drink (RTD) coffee beverages

Adjacent Products Explicitly Excluded

  • Specialty caffeinated coffee
  • Conventional decaf coffee
  • Tea and other hot beverages
  • Coffee substitutes (e.g., chicory)
  • Coffee brewing equipment

Geographic coverage

The report provides focused coverage of the Brazil market and positions Brazil within the wider global consumer-goods industry structure.

The geographic analysis explains local consumer demand conditions, brand and private-label balance, retail concentration, pricing tiers, import dependence, and the country’s strategic role in the wider category.

Geographic and Country-Role Logic

  • Origin: Producer countries (e.g., Peru, Colombia, Ethiopia) for certified beans
  • Processing: Countries with decaffeination plants (e.g., Canada, Germany, Mexico)
  • Consumption: High-income markets with ethical consumption trends (e.g., US, UK, Germany, Nordic countries)

Who this report is for

This study is designed for strategic and commercial users across brand-led consumer categories, including:

  • general managers, brand leaders, and portfolio teams evaluating category attractiveness, pricing power, and whitespace;
  • category managers, trade-marketing teams, retail buyers, and e-commerce teams prioritizing assortment, promotion, and channel strategy;
  • insights, shopper-marketing, and innovation teams tracking need states, occasions, pack-price ladders, claims, and competitive messaging;
  • private-label and contract-manufacturing strategists assessing entry options, retailer leverage, and supply-side positioning;
  • distributors and route-to-market teams evaluating country and channel expansion priorities;
  • investors and strategy teams benchmarking competitive structure, premiumization, revenue quality, and margin logic.

Why this approach matters in consumer categories

In many brand-driven, channel-sensitive, and consumer-demand-led markets, official trade and production statistics are not sufficient on their own to describe the true market. Product boundaries may cut across multiple tariff codes, several product categories may be bundled into the same official classification, and a meaningful share of activity may take place through customized services, captive supply, platform relationships, or technically specialized channels that are not directly visible in standard statistical datasets.

For this reason, the report is designed as a modeled strategic market study. It uses official and public evidence wherever it is reliable and scope-compatible, but it does not force the market into a purely statistical framework when doing so would reduce analytical quality. Instead, it reconstructs the market through the logic of demand, supply, technology, country roles, and company behavior.

This makes the report particularly well suited to products that are innovation-intensive, technically differentiated, capacity-constrained, platform-dependent, or commercially structured around specialized buyer-supplier relationships rather than standardized commodity trade.

Typical outputs and analytical coverage

The report typically includes:

  • historical and forecast market size;
  • consumer-demand, shopper-mission, and need-state analysis;
  • category segmentation by format, benefit platform, channel, price tier, and pack architecture;
  • brand hierarchy, private-label pressure, and competitive-structure analysis;
  • route-to-market, retail, e-commerce, and availability logic;
  • pricing, promotion, trade-spend, and revenue-quality interpretation;
  • country role mapping for brand building, sourcing, and expansion;
  • major-brand and company archetypes;
  • strategic implications for brand owners, retailers, distributors, and investors.
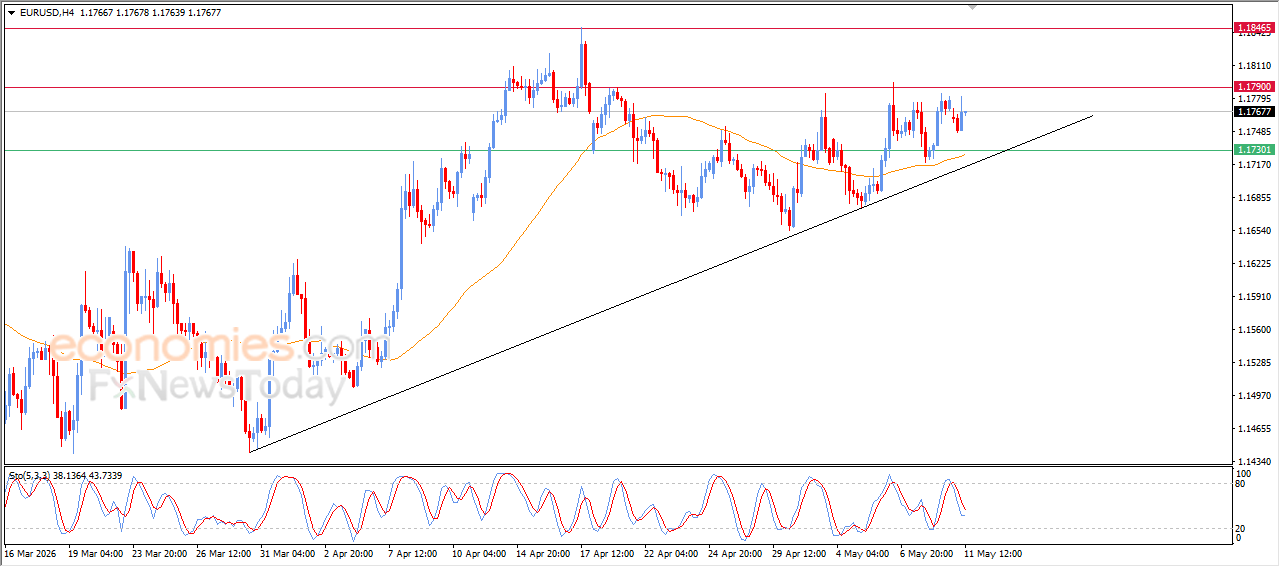


Source link

Go to Top