The main tag of GoldPrice Articles.
You can use the search box below to find what you need.
[wd_asp id=1]
The main tag of GoldPrice Articles.
You can use the search box below to find what you need.
[wd_asp id=1]
More oil leaving the Gulf does not necessarily mean the region is producing more crude, a distinction that helps explain why Goldman Sachs still expects supply risks to keep Brent expensive even as prices retreat.
The bank’s latest outlook retains $90 a barrel for December 2026, following its previously announced increase from $85.
Brent was quoted near $105.37 on Thursday afternoon, down 0.28% from the previous close, leaving the December projection well below the market despite the upgrade.
“More crude reaching international markets does not necessarily mean more oil is being produced,” says Saxo Bank analyst Ole Hansen.
“Some of the recovery reflects a redistribution of available barrels, including volumes that would otherwise have supplied regional refineries.”
Diverting crude to export markets can ease the shortage facing overseas buyers while leaving fewer barrels for local fuel production.
It therefore offers less reassurance than a sustained increase in output, particularly while shipping routes and energy infrastructure remain vulnerable to attack.
The latest decline also reflects a broader move away from riskier assets, rather than clear evidence that the supply problem has been resolved.
Deutsche Bank recorded an overnight reversal in oil after Wednesday’s rise as the technology-share sell-off spread across global markets.
The bank noted: “Moreover, that’s despite Ukrainian President Zelenskyy saying to the FT that Ukraine would resume its strikes on Russian refineries.”
Renewed refinery disruption matters for crude and refined products in different ways.
A refinery processing less oil can reduce demand for its raw material, while its lost diesel or petrol output leaves customers competing for fewer finished fuels.
That can produce falling crude prices alongside expensive fuel, making a single Brent quote an incomplete measure of the pressure on energy users.
Goldman’s December view builds on the forecast revision examined in our earlier analysis of recovering Gulf exports and persistent disruption premiums.
The bank’s latest quarterly projections also point towards an easing market, with Brent at $87 for Q1 2027.
That quarterly figure is a different horizon from the December call, rather than a second price expected on the same date.
Governments can respond to product shortages without waiting for crude production and refinery operations to recover fully.
The International Energy Agency has urged members to consider accelerating previously pledged stock releases, prioritising diesel, and to assess whether additional releases are warranted.
Its statement sets out possible action rather than confirming a new agreed release volume.
The inflation consequences of continued disruption were visible in Thursday’s US producer-price figures, which showed diesel prices for processed intermediate demand rising 21% in September.
That is an upstream US price measure, not an increase at British filling stations, but it illustrates how pressure can persist further along the supply chain.
Goldman’s analysts continue to watch both sides of the energy balance: “The situation in the Middle East remains fluid and we will be closely watching how the region’s energy exports as well as demand for its energy from key consumers like China continue to evolve.”
What is Goldman’s December Brent forecast?
Goldman Sachs retains $90 a barrel for December 2026 after previously raising the forecast from $85.
Why do recovering exports not guarantee more oil supply?
Some exported crude may be diverted from regional refineries rather than coming from additional production.
Can diesel stay expensive while Brent falls?
Yes: refinery disruption can restrict finished-fuel supply even when crude prices retreat.
Silver price (XAG/USD) extends its gains for the second consecutive day, trading around $57.80 per troy ounce during Asian hours on Friday. Silver prices advanced as a sharp selloff in equity markets triggered renewed safe-haven demand for precious metals. This capital flight into safer assets drove bond yields significantly lower, reducing the opportunity cost of holding non-yielding assets like Silver and offering broad support to the metal.
TMGM Analysis: Financial Market News, Economic Calendar & Market Insights
Adding to the bullish momentum, investors digested intensifying geopolitical risks in the Middle East. Tensions flared following escalating hostilities between Saudi Arabia and Iran-backed Houthi forces in Yemen, alongside an incident earlier in the week where an Iranian projectile struck and sank a Singapore-flagged container ship in the Strait of Hormuz.
Meanwhile, market participants continued to assess the Federal Reserve’s (Fed) monetary policy path, as recent robust US economic data bolstered expectations of tighter borrowing conditions. According to the CME FedWatch Tool, markets are currently pricing in a roughly 72% chance that the Fed will hold interest rates steady this month, while expectations for a rate increase in December have risen to 92%.
According to TD Securities, “CTAs are extremely active cross-asset today,” with “notable short-covering across the board in the rates complex.” This shift in positioning is “helping CTAs to reverse course on yesterday’s large-scale gold selling,” while “silver, platinum and palladium are also all seeing CTA short covering,” easing some of the systematic pressure that has weighed on the precious metals space.
In the daily chart, XAG/USD trades at $57.80, extending its decline below both the short-term and medium-term trend metrics, which keeps the near-term bias bearish. The price is currently under the nine- and 50-day Exponential Moving Averages (EMAs), suggesting that rebounds remain capped while the broader downswing persists. The 14-day Relative Strength Index (RSI) at 38.85 stays in low-neutral territory, hinting at lingering downside pressure but not yet extreme oversold conditions, while the latest FXS Fed Sentiment Index reading at 127.51 reinforces the idea that macro policy expectations still lean against precious metals.
On the topside, immediate resistance aligns with the nine-day EMA at $58.81, where any recovery would likely stall initially, followed by a more solid barrier at the 50-day EMA near $62.46 that defines the upper boundary of the current corrective phase. With no clear nearby support levels derived from the available indicators, traders may look to recent lows and psychological round figures as provisional floors, while the bearish bias is expected to hold as long as XAG/USD trades below the clustered moving average resistance.

(The technical analysis of this story was written with the help of an AI tool. Know more.)
Silver is a precious metal highly traded among investors. It has been historically used as a store of value and a medium of exchange. Although less popular than Gold, traders may turn to Silver to diversify their investment portfolio, for its intrinsic value or as a potential hedge during high-inflation periods. Investors can buy physical Silver, in coins or in bars, or trade it through vehicles such as Exchange Traded Funds, which track its price on international markets.
Silver prices can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can make Silver price escalate due to its safe-haven status, although to a lesser extent than Gold’s. As a yieldless asset, Silver tends to rise with lower interest rates. Its moves also depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAG/USD). A strong Dollar tends to keep the price of Silver at bay, whereas a weaker Dollar is likely to propel prices up. Other factors such as investment demand, mining supply – Silver is much more abundant than Gold – and recycling rates can also affect prices.
Silver is widely used in industry, particularly in sectors such as electronics or solar energy, as it has one of the highest electric conductivity of all metals – more than Copper and Gold. A surge in demand can increase prices, while a decline tends to lower them. Dynamics in the US, Chinese and Indian economies can also contribute to price swings: for the US and particularly China, their big industrial sectors use Silver in various processes; in India, consumers’ demand for the precious metal for jewellery also plays a key role in setting prices.
Silver prices tend to follow Gold’s moves. When Gold prices rise, Silver typically follows suit, as their status as safe-haven assets is similar. The Gold/Silver ratio, which shows the number of ounces of Silver needed to equal the value of one ounce of Gold, may help to determine the relative valuation between both metals. Some investors may consider a high ratio as an indicator that Silver is undervalued, or Gold is overvalued. On the contrary, a low ratio might suggest that Gold is undervalued relative to Silver.
A move above the 20-day moving average would provide an initial sign of strength and could attract additional bullish momentum. However, a decisive advance above the recent lower swing high of $4,226 is needed to trigger a bullish reversal signal in the daily trend structure. Another earlier sign of strength would be seen on a rise above this week’s high of $4,217, as a rise above it would signal renewed strength in the weekly advance. A sustained move above the relevant swing high would also reinforce the potential for a new advance from the $4,066 support area, following the initial recovery from the early-August consolidation low.
An upside breakout would open the way toward a measured-move target near $4,821 (D), projected by the rising ABCD pattern on the chart. Price symmetry for the two upswings converges at that level, making it a potential resistance zone. A decisive breakout above this target, however, would signal continued strength and expose the next upside resistance zone. Until gold clears those near-term resistance levels, the ability to hold support above $4,066 remains central to the potential recovery.
Iran continues to attack vessels in the Strait of Hormuz. The country is not ready for serious discussions on its nuclear program, which was the key reason for the military operation against Iran. In turn, the U.S. is not ready for concessions and continues to put maximum economic pressure on Iran, using sanctions and naval blockade.
It looks that both sides of the conflict see escalation as a way out of the current situation. I’d note that Iran may strike oil facilities in the region in case the U.S. resumes the military operation, which is the key threat for oil markets.
Warsh said broader economic conditions were in line with expectations set at the Fed’s September rate increase. He acknowledged persistent price pressure and higher global prices, but he did not give traders a signal on the October 28 meeting.
That changed the short-term rate trade. The probability of an October increase fell from around 27% to roughly 15% after his remarks. The U.S. dollar slipped against a basket of major currencies, while S&P 500 futures moved higher.
Gold got a lift from that shift because a weaker dollar makes bullion cheaper for overseas buyers. But Warsh did not remove the Fed from the trade. He only refused to make October the decision.
At 05:54 GMT, Spot Gold is trading $4,173.76, up $3.06 or +0.07%. December Comex Gold is trading $4,194.40, up $24.30 or +0.58%.
The EIA’s October 6 Short-Term Energy Outlook supplies a separate winter baseline. It projects end-of-October inventories around 3,850 billion cubic feet, roughly 2% above the 5-year average. This model assumes winter heating degree days near last winter’s national level, and inputs were closed October 1. Later weather and operational developments therefore require further assessment.
Supply growth and export demand remain a competing structural influence, with the EIA forecasting U.S. dry production averaging 112.2 billion cubic feet daily in 2026 and 116.3 billion cubic feet daily in 2027, while LNG exports average 17.6 and 18.6 billion cubic feet daily. These are annual projections, not current daily production or terminal feed gas measurements. Sustained production growth would create more room to accommodate exports and domestic demand. However, a forecast of additional supply is less useful for near-term pricing than evidence that gas is actually being produced or delivered. The distinction applies to LNG capacity, capability, and realized demand on the pipeline system; they are different issues.
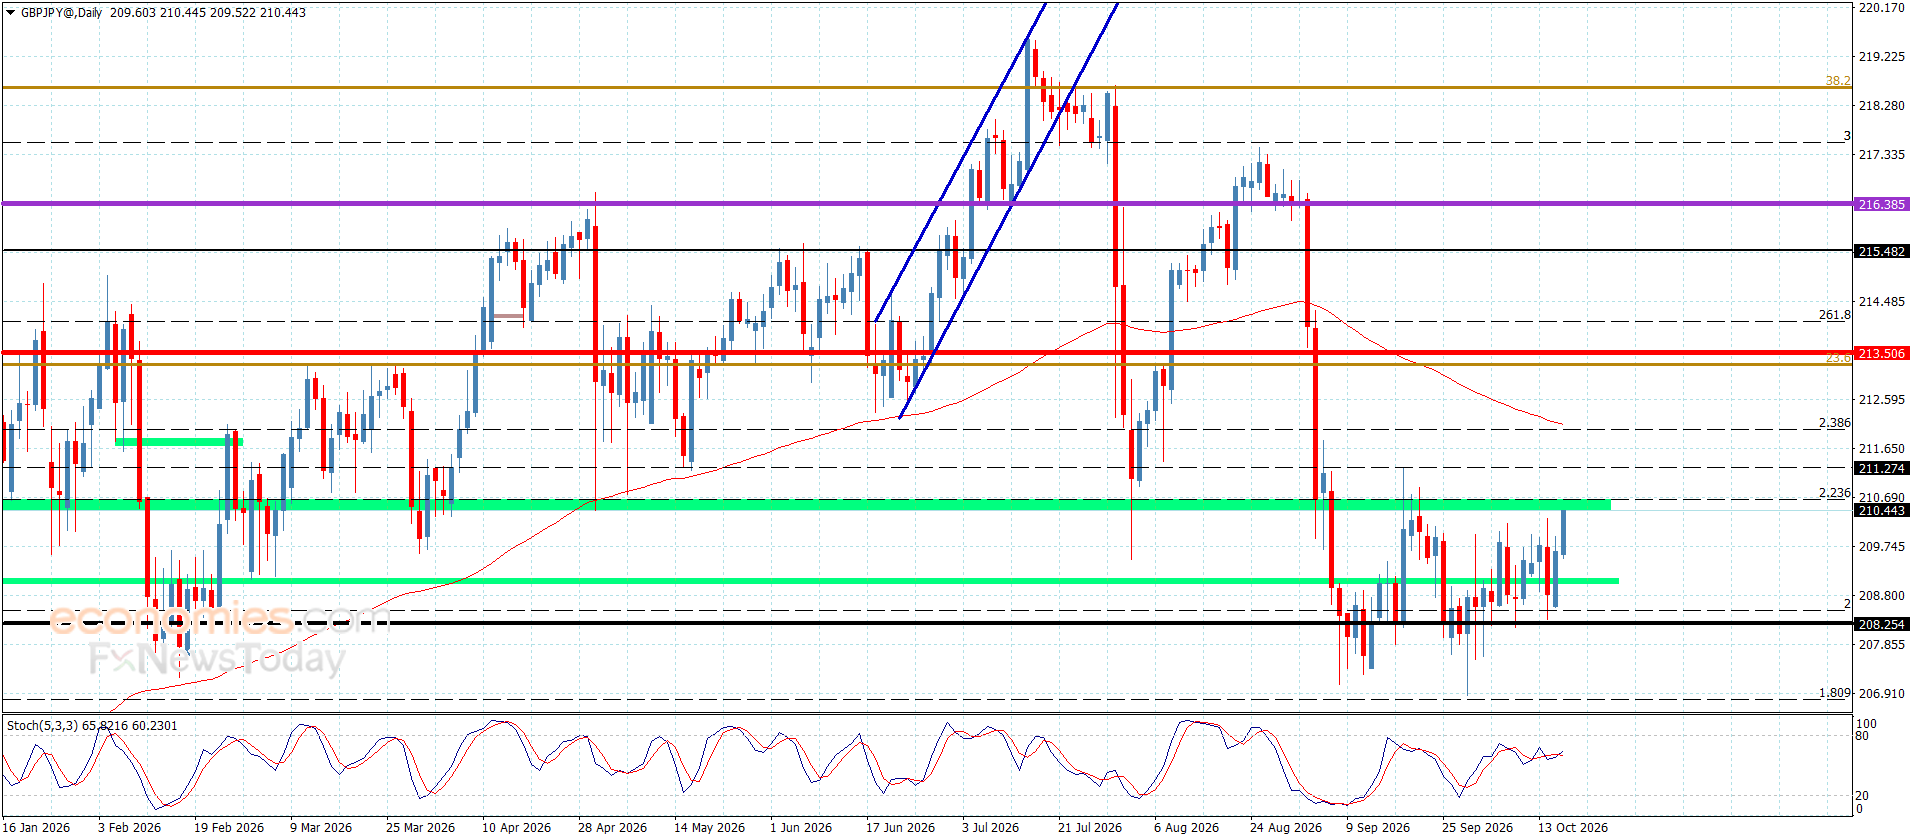
The GBPJPY pair renewed its bullish corrective attempts, taking advantage of its repeated stability above the additional support level at 208.10, alongside the positive momentum provided by the Stochastic indicator. The pair is currently trading near its previously anticipated target at 210.40.
Note that the current divergence among the main indicators may push the price into mixed sideways trading, with a possibility of forming bearish waves that could target 209.60 and 209.00. However, a successful break above 210.40 and stability above this level would enable the pair to resume its corrective advance and attempt to test the main resistance barrier near 211.20.
The expected trading range for today is between 209.00 and 210.55.
Trend forecast: Sideways
Higher-than-expected PPI report did not have any impact on the Treasury market today as traders rushed to buy safe-haven bonds amid AI uncertainty. PPI increased by +1.3% month-over-month in September, highlighting growing inflationary pressure.
FedWatch Tool indicates that the probability for a rate hike at the next Fed meeting in October declined to 29.3%. Traders believe that Fed will not raise rates despite inflation data. The falling probability of a rate hike provided additional support to gold markets.
U.S. dollar pulled back against a broad basket of currencies as traders reacted to the rally in U.S. bond markets. Weaker dollar served as an additional positive catalyst for gold.
Currently, gold is trying to settle back above the resistance level at $4160 – $4180. In case gold manages to settle above the $4180 level, it will head towards the resistance, which is located in the $4300 – $4320 range. RSI is in the moderate territory, so there is plenty of room to gain momentum in case the right catalysts emerge.
For now, a confirmed breakout above $3.396 and then $3.41, could see the 127.2% Fibonacci ABCD projection reached at $3.548. But the first more significance level is defined by the 127.2% Fibonacci extension of the prior decline near $3.61. A key concern now will be the characteristics of further consolidation or weakness before a new high breakout signals, if that is what occurs.
If you’d like to know more about how to trade natural gas, please visit our educational area.
Gold (XAU/USD) is currently trading at $4,133.61, after a bounce from the $4,073.63 area on the 2-hour time frame. I like to draw your attention to the fact that the price bounce has taken gold above the $4,107-$4,128 area, but is still below a descending trend line and a resistance area formed by the moving averages. Thus, the overall bearish trend is still intact, despite the current bounce.The first area of interest on the upside is at $4,161.46, above which $4,181.44 and $4,216.96 would come into play. On the other hand, the first support comes in at $4,127.56, below which $4,107.28, $4,088.10, and $4,073.63 would come into focus.