The main category of Forex News.
You can use the search box below to find what you need.
[wd_asp id=1]
The main category of Forex News.
You can use the search box below to find what you need.
[wd_asp id=1]
The Euro to Pound (EUR/GBP) exchange rate has stabilised near six-week lows after Sterling’s strong spring rally, but Rabobank believes the balance of risks is now shifting back in favour of the Euro as expectations for aggressive Bank of England tightening continue to unwind.
According to Rabobank, Sterling’s impressive performance during March and April was driven primarily by a dramatic repricing of UK interest-rate expectations following the outbreak of the Iran conflict.
At one stage markets were pricing almost four Bank of England rate hikes this year as investors feared a prolonged inflation shock.
That view has softened considerably following weaker UK labour market and inflation releases this month.
“The combination of this week’s release of softer than expected UK labour and CPI inflation data have calmed market nerves regarding the extent of potential BoE rate hikes.”
Markets currently price around 45 basis points of tightening over the next six months, but Rabobank believes investors remain too hawkish.
“In Rabo’s view, the BoE is likely to hike only once this year to ensure that inflation expectations remain well anchored.”
The bank argues that spare capacity is continuing to build in the labour market, reducing the risk of the wage-price spiral that emerged following the 2022 energy crisis.
“The current weakness of the UK labour market contrasts markedly with its position after the 2022 energy crisis.”
Rabobank believes any further scaling back of rate-hike expectations would remove an important source of support for Sterling.
Alongside changing monetary-policy expectations, Rabobank believes UK politics could become a renewed source of volatility for the Pound during the summer months.
Recent reassurance from potential Labour leadership contender Andy Burnham regarding adherence to current fiscal rules has helped stabilise both gilt markets and Sterling.
However, uncertainty surrounding Labour’s future leadership remains an important risk factor.
“If Labour candidate Burnham wins, he would be expected to launch a leadership contest which could result in a move to the soft left for the Labour party.”
Rabobank expects both gilts and Sterling to remain sensitive to political headlines in the run-up to any potential leadership challenge.
“UK political development will remain influential in the weeks ahead.”
While Sterling has recovered from its weakest levels earlier this month, Rabobank does not expect a sustained move lower in EUR/GBP.
Instead, the bank sees a period of volatile range trading before the pair gradually trends higher later this year.
“We see scope for further choppy range trading in EUR/GBP around current levels and maintain a 6-month target of 0.88.”
That forecast would imply roughly a 2% rise from current levels and broadly aligns with the majority of major bank forecasts.
Among recent EUR to GBP rate projections, ING, Citi, SEB and Scotiabank all forecast EUR/GBP rising towards 0.89-0.90 over coming quarters, while MUFG projects 0.88 and Danske Bank expects a move towards 0.89.
Goldman Sachs remains one of the more constructive houses on Sterling in the near term but still sees EUR/GBP reaching 0.88 later this year.
Rabobank’s view is that slowing UK growth, fading Bank of England tightening expectations and lingering political uncertainty will ultimately outweigh the support Sterling has received from higher gilt yields.
Rabobank expects EUR/GBP to remain volatile in the near term but believes the broader trend points higher, with fading expectations for aggressive Bank of England tightening leaving scope for a move towards 0.88 over the next six months.
While the Pound benefited from soaring rate-hike expectations earlier this year, Rabobank argues that softer inflation data, a weakening labour market and growing political uncertainty mean that support is beginning to fade.
Unless UK economic data reaccelerates significantly, the bank expects investors to continue reducing expectations for future BoE tightening, creating a more favourable backdrop for EUR/GBP gains into the second half of 2026.
Silver continues to be very noisy on Friday as we have pulled back a bit despite the fact that interest rates have dropped.
The 50-day EMA just above continues to offer a little bit of resistance and therefore I think it does make a certain amount of sense that we just hang out in this region.
Quite frankly, I believe this is a market that given enough time probably has to make a bigger decision, but as we head into the weekend it’s difficult to get overly aggressive with anything, let alone a market that is extraordinarily volatile like silver.

The XAG/USD market pulling back from here could open up the possibility of a test of the $70.00 level. The 200-day EMA sits just below there, and I think it opens up the possibility of even more support. To the upside, we have the $80.00 level, which of course is above the 50-day EMA.
The $80.00 level is essentially fair value from the longer-term consolidation range, which extends all the way to the $90.00 level. That $90.00 level I think is a target eventually, but it’s going to take a while to get there. If we were to break out above there, then I think you start to see silver behave extraordinarily bullish.
There is a lot of demand out there for the little bit of supply that we have for silver, but as long as interest rates remain relatively high, I think a lot of people are going to be very hesitant to buy a lot of silver. Furthermore, as we head into the weekend, we don’t know what the headlines will be, and therefore it makes sense that we have somewhat of a lackluster end.
Ready to trade our daily forex analysis and predictions? Here are the best Silver trading brokers to choose from.
Christopher Lewis has been trading Forex and has over 20 years experience in financial markets. Chris has been a regular contributor to Daily Forex since the early days of the site. He writes about Forex for several online publications, including FX Empire, Investing.com, and his own site, aptly named The Trader Guy. Chris favours technical analysis methods to identify his trades and likes to trade equity indices and commodities as well as Forex. He favours a longer-term trading style, and his trades often last for days or weeks.
As seen on: Pairs Of Aces Podcast,The Trader Guy, FXEmpire
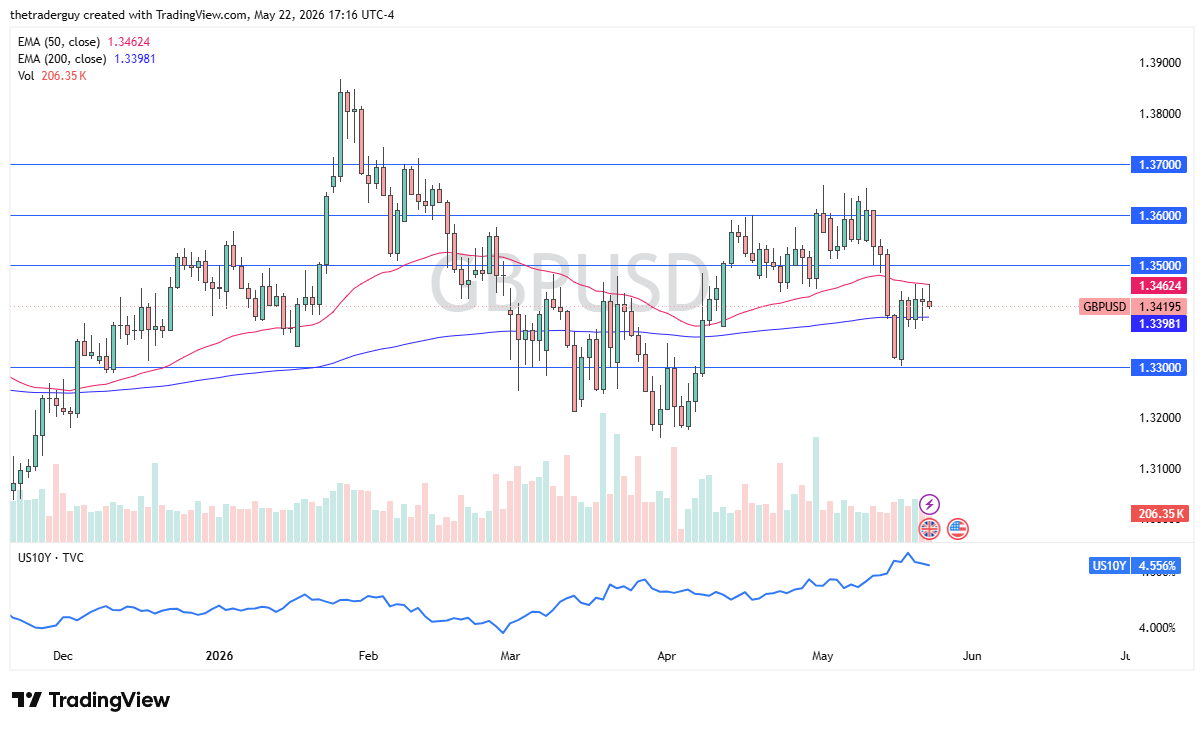
The British pound initially rallied during the trading session on Friday but gave back gains as we tested the 50-day EMA.
Ultimately, this is a market that I think is going to continue to be very noisy, but if we can break above that 50-day EMA, it is possible that we could go looking to the 1.35 level.
The 1.35 level is an area that will remain a bit of a psychological barrier, I think.
We will see whether or not we are going to give you an opportunity here to break out above there and start shorting the dollar. The interest rate differential is, of course, going to be in favor of the British pound—not by a lot, but enough that it keeps the British pound a little bit more resilient against the dollar than many other currencies. If we fall from here, the 200-day EMA is going to offer support underneath. Breaking that opens up a drop down to the 1.33 level.
All things being equal, this is a market that I think will remain very noisy and very volatile. The British pound is a currency that is kind of similar to the dollar in the sense that the central bank may have to stay tighter for longer, and because of that, I expect to see a lot of compression, a lot of sideways action.
In fact, if you are a short-term day trader, this is probably your currency market. Otherwise, you are going to be hard-pressed to find a reason to get overly aggressive. At least not until we get out of this 200-pip range, which, by the way, we are right at the middle. So, this is no man’s land.
Ready to trade our daily GBP/USD Forex forecast? Here’s some of the best forex broker UK reviews to check out.
Christopher Lewis has been trading Forex and has over 20 years experience in financial markets. Chris has been a regular contributor to Daily Forex since the early days of the site. He writes about Forex for several online publications, including FX Empire, Investing.com, and his own site, aptly named The Trader Guy. Chris favours technical analysis methods to identify his trades and likes to trade equity indices and commodities as well as Forex. He favours a longer-term trading style, and his trades often last for days or weeks.
As seen on: Pairs Of Aces Podcast,The Trader Guy, FXEmpire
The light sweet crude oil market has gone back and forth to show signs of hesitation, but at this point in time, we are sitting just below the $100 level.
We did bounce from the 50-day EMA and that does matter.
I think ultimately you have got a situation where if we can break above the $100 level, then $105 could be very real. Breaking below the 50-day EMA opens up a drop to the 50% Fibonacci retracement level of the bigger move going back several months, possibly even opening up a drop down to the 61.8% Fibonacci retracement level near the $86 level. The $105 level has proven to be very difficult, and if we can break above there, the $110 level is, in fact, where we go longer term.
All things being equal, I expect a lot of choppy behavior out of oil because, quite frankly, we have got a bunch of people in the news throwing headlines around to move the markets and not really anything fundamentally driven other than the fact that there is going to be a shortage, no matter what people think or want.
A move above the $110 level opens up the possibility of a move to the $120 level before it is all said and done, but I do not see that happening yet. All things being equal, I do think that we are trying to find some type of summer range from which to trade in, and with that, I look at this as a market that, quite frankly, if we get an opportunity to buy the dip, you probably want to.
I just would not look for huge gains. I think finding a little bit of value in oil makes a certain amount of sense this time of year, but again, remember, this could be moved by the latest tweet or press conference, you just do not know.
Ready to trade daily crude oil price analysis? We’ve shortlisted the best Forex Oil trading brokers in the industry for you.
Christopher Lewis has been trading Forex and has over 20 years experience in financial markets. Chris has been a regular contributor to Daily Forex since the early days of the site. He writes about Forex for several online publications, including FX Empire, Investing.com, and his own site, aptly named The Trader Guy. Chris favours technical analysis methods to identify his trades and likes to trade equity indices and commodities as well as Forex. He favours a longer-term trading style, and his trades often last for days or weeks.
As seen on: Pairs Of Aces Podcast,The Trader Guy, FXEmpire
The EUR/USD pair opens with a bullish gap at the start of a new week as renewed optimism over a potential US-Iran peace deal weighs heavily on the safe-haven US Dollar (USD). Spot prices climb back closer to mid-1.1600s during the Asian session, though the broader setup warrants some caution before positioning for an extension of a modest recovery from the lowest level since April 7, around the 1.1575 region, touched last Thursday.
From a technical perspective, the EUR/USD pair is holding above the 23.6% Fibonacci retracement of the April-May downfall. Adding to this, the Relative Strength Index (RSI) is around 58 and a slightly positive Moving Average Convergence Divergence (MACD) reading hints at improving momentum. This, in turn, backs the case for a further intraday appreciating move, though hawkish US Federal Reserve (Fed) bets could limit USD losses and cap spot prices.
Hence, any subsequent move up is more likely to confront an immediate hurdle near the 38.2% Fibo. level, around the 1.1675-1.1680 region. This is followed by the 1.1710 confluence, comprising the 200-period Simple Moving Average (SMA) on the 4-hour chart and the 50% retracement. The said area should keep the near-term bias capped, above which the EUR/USD pair could target the 61.8% level around 1.1740 and the 78.6% retracement at 1.1785 en route to the cycle high at 1.1842.
On the downside, immediate support is located at the 23.6% retracement at 1.1638, with a deeper floor at the Fibonacci structural anchor around 1.1574, where a break would reopen the broader bearish phase.
(The technical analysis of this story was written with the help of an AI tool.)
The table below shows the percentage change of US Dollar (USD) against listed major currencies today. US Dollar was the strongest against the Canadian Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.32% | -0.37% | -0.25% | -0.16% | -0.57% | -0.46% | -0.35% | |
| EUR | 0.32% | -0.06% | 0.07% | 0.14% | -0.26% | -0.15% | -0.03% | |
| GBP | 0.37% | 0.06% | 0.13% | 0.20% | -0.21% | -0.08% | 0.02% | |
| JPY | 0.25% | -0.07% | -0.13% | 0.08% | -0.36% | -0.26% | -0.15% | |
| CAD | 0.16% | -0.14% | -0.20% | -0.08% | -0.42% | -0.32% | -0.21% | |
| AUD | 0.57% | 0.26% | 0.21% | 0.36% | 0.42% | 0.11% | 0.22% | |
| NZD | 0.46% | 0.15% | 0.08% | 0.26% | 0.32% | -0.11% | 0.10% | |
| CHF | 0.35% | 0.03% | -0.02% | 0.15% | 0.21% | -0.22% | -0.10% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the US Dollar from the left column and move along the horizontal line to the Japanese Yen, the percentage change displayed in the box will represent USD (base)/JPY (quote).
Domestic coffee prices today
Opening the first trading session of the new week on May 25, 2026, the domestic coffee market did not maintain the excitement of the previous weekend. According to survey data, the purchase price of soybean kernels has simultaneously cooled down, losing from 300 to 400 VND/kg.
Dak Nong (old): Reduced by 400 VND, retreating to 87,700 VND/kg, but still continues to lead in purchasing prices throughout the region.
Dak Lak: Reduced by 400 VND, currently trading at the threshold of 87,600 VND/kg.
Gia Lai: Recorded a slight decrease of 300 VND, listed at the same level as Dak Lak at 87,600 VND/kg.
Lam Dong: Reduced by 400 VND, pushing the purchase price down to the lowest level in the region at 87,000 VND/kg.
Notably, pepper today also recorded a decrease of 1,000 VND, falling to the level of 141,000 VND/kg. Conversely, the USD/VND exchange rate at Vietcombank slightly increased by 2 VND, currently listed at 26,132 VND/USD.
World coffee prices
Due to time zone differences, as of noon today (Vietnam time), both ICE London and New York futures exchanges have not yet entered the official order matching session of Monday. Electronic boards are currently temporarily frozen, maintaining the opposite closing level of last Friday:
London Stock Exchange (Robusta): July futures (RMN26) anchored at a high of $3,456/ton (maintaining the breakthrough +57 USD from the end of the week).
New York Stock Exchange (Arabica): July futures (KCN26) sideways at 272.35 cents/lb (currently in the lowest price range in 1.5 years).
Coffee market outlook
The coffee market is currently caught between two opposing macroeconomic information flows, creating a fierce tug-of-war in investor sentiment:
The current high price of Robusta is greatly supported by the drought in Vietnam. According to the weather forecasting agency, rainfall in the Central Highlands in the past time is still very scattered and scarce, directly threatening the development of young coffee fruit trees. Severe drought has caused ponds and lakes in Gia Lai and many Central Highlands regions to dry up to the bottom, thousands of hectares of coffee and pepper fell into a state of thirst.
In addition, the “Super El Niño” specter (with a 67% probability of occurring according to NOAA) is raising concerns that the rainy season in Brazil will be delayed to September and October, with the risk of devastating the 2026/27 crop. Arabica inventories hitting a 3-month low (449,567 bags) is also a safe buffer zone to prevent prices from falling freely.
Although the weather is very risky, the actual crop season of Brazil is being assessed as extremely good. “Big players” such as Marex and StoneX continuously emphasize the production figure of 75.3 – 75.9 million bags, pushing the global surplus in 2026 to a record level of 10 million bags. At the same time, Vietnam’s export data increased sharply by 15.8% (reaching 810,000 tons in the first 4 months of the year) along with the fact that Robusta inventories on the London exchange have just recovered to a 6-week high (3,968 lots) are burdens hindering price increases.
The slight downward correction at the beginning of the week in the domestic market shows the caution of traders ahead of the new South American crop line pouring into the market.
EUR/JPY extends its gains for the second successive day, trading around 184.90 during the Asian hours on Monday. The pair is holding a mild bullish bias as it consolidates above both the nine-day and 50-day Exponential Moving Averages (EMAs), which cluster just below price around the mid-184s and reinforce a nearby demand zone.
Moreover, the 14-day Relative Strength Index (RSI) sits close to the 50 line, hinting at neutral but stabilizing momentum that could allow the cross to extend gains while it remains supported by these short- and medium-term trend gauges.
However, the technical analysis of the daily chart indicates the EUR/JPY cross is still moving sideways within a descending channel pattern, indicating an ongoing bearish bias. A sustained break above the channel would offer a bearish confirmation.
The immediate resistance lies at the upper boundary of the channel around 185.10. Further advances would support the EUR/JPY cross to explore the region around the all-time high of 187.95, which was recorded on April 17.
The immediate support lies at the 50-day EMA of 184.85, followed by the nine-day EMA at 184.79. A break below these moving averages would put downward pressure on the EUR/JPY cross to navigate the region around the three-month low of 181.87, recorded on March 16, followed by a five-month low of 180.81, which was reached on February 12.
(The technical analysis of this story was written with the help of an AI tool.)
The table below shows the percentage change of Euro (EUR) against listed major currencies today. Euro was the strongest against the US Dollar.
| USD | EUR | GBP | JPY | CAD | AUD | NZD | CHF | |
|---|---|---|---|---|---|---|---|---|
| USD | -0.35% | -0.40% | -0.27% | -0.17% | -0.59% | -0.51% | -0.36% | |
| EUR | 0.35% | -0.06% | 0.07% | 0.16% | -0.27% | -0.17% | -0.03% | |
| GBP | 0.40% | 0.06% | 0.15% | 0.22% | -0.20% | -0.11% | 0.02% | |
| JPY | 0.27% | -0.07% | -0.15% | 0.09% | -0.37% | -0.29% | -0.16% | |
| CAD | 0.17% | -0.16% | -0.22% | -0.09% | -0.43% | -0.35% | -0.23% | |
| AUD | 0.59% | 0.27% | 0.20% | 0.37% | 0.43% | 0.08% | 0.21% | |
| NZD | 0.51% | 0.17% | 0.11% | 0.29% | 0.35% | -0.08% | 0.12% | |
| CHF | 0.36% | 0.03% | -0.02% | 0.16% | 0.23% | -0.21% | -0.12% |
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Euro from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent EUR (base)/USD (quote).
Gold (XAU/USD) trades lower for the second consecutive day on Friday, but remains contained within previous ranges, with downside attempts limited above the $4,500 line for now. Market volatility remains subdued on Friday, with traders awaiting developments from the US-Iran war to make investment decisions.
The confusing situation in the Middle East is providing moderate support to the safe-haven US Dollar, keeping the US Dollar Index (DXY) steady near six-week highs and Gold bulls in check.
The latest news reports that Tehran is reviewing a peace proposal submitted by the US, with both parties far apart on Iran’s nuclear activities and control of the Strait of Hormuz. US Secretary of State Marco Rubio, however, said on Thursday that there was “some progress” in the talks with Tehran, which is feeding a moderate optimism
XAU/USD trades at $4,522, holding a capped tone, with price action nearing the tip of a small triangle pattern. The Relative Strength Index (RSI) hovers around 45, hinting at consolidative, yet slightly negative momentum, while the Moving Average Convergence Divergence (MACD) stays in positive territory but has started to ease, suggesting that recent upside attempts are losing traction
Triangles are considered continuation patterns; thus, in this case, a bearish outcome is favoured. The base of the triangle is now at $4,500, but the key support area is the May 20 low near $4,450. A break of this level exposes late March lows at $4,350 and $4,306.
A confirmation above $4,580 (May 18 highs), on the other hand, would negate the bearish view and shift to the May 11 and 12 lows around the $4,650 ahead of May’s top in the $4,770 area.
(The technical analysis of this story was written with the help of an AI tool.)
Gold has played a key role in human’s history as it has been widely used as a store of value and medium of exchange. Currently, apart from its shine and usage for jewelry, the precious metal is widely seen as a safe-haven asset, meaning that it is considered a good investment during turbulent times. Gold is also widely seen as a hedge against inflation and against depreciating currencies as it doesn’t rely on any specific issuer or government.
Central banks are the biggest Gold holders. In their aim to support their currencies in turbulent times, central banks tend to diversify their reserves and buy Gold to improve the perceived strength of the economy and the currency. High Gold reserves can be a source of trust for a country’s solvency. Central banks added 1,136 tonnes of Gold worth around $70 billion to their reserves in 2022, according to data from the World Gold Council. This is the highest yearly purchase since records began. Central banks from emerging economies such as China, India and Turkey are quickly increasing their Gold reserves.
Gold has an inverse correlation with the US Dollar and US Treasuries, which are both major reserve and safe-haven assets. When the Dollar depreciates, Gold tends to rise, enabling investors and central banks to diversify their assets in turbulent times. Gold is also inversely correlated with risk assets. A rally in the stock market tends to weaken Gold price, while sell-offs in riskier markets tend to favor the precious metal.
The price can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can quickly make Gold price escalate due to its safe-haven status. As a yield-less asset, Gold tends to rise with lower interest rates, while higher cost of money usually weighs down on the yellow metal. Still, most moves depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAU/USD). A strong Dollar tends to keep the price of Gold controlled, whereas a weaker Dollar is likely to push Gold prices up.
GBPUSD also relies on rate expectations, but the U.K. has an issue with the rate outlook. The 30-year gilt yield has jumped to 5.85% that shows strong pressure in the long end of the bond market.
When yields are higher, they can support strong growth or higher return. But they can hurt the currency when they face fiscal risk. In the U.K., investors may be concerned that rising debt burden will put pressure on government finances and slow growth.
This makes sterling vulnerable. If inflation is likely to stay high, there is limited scope for the Bank of England to reduce interest rates further. However, it is not possible to overlook the economic effects of high interest rates. The equilibrium can create uncertainty for GBPUSD.
The outlook is mixed and uncertain. GBPUSD could benefit from the Bank of England’s cautious move on inflation. But a positive U.S. yield and U.K. fiscal issues could limit the gains. However, a better bullish environment would have to form lower U.S. yields, steady gilts and better U.K. growth data.
The chart below shows that the GPPUSD trades within the 1.30 and 1.3780. A break of this range is required to take the pair in any direction.
Indonesia’s decaf coffee variety pack market sits at the intersection of two powerful consumer trends: rising specialty coffee culture and a growing desire to reduce daily caffeine intake. While Indonesia is a major global producer of arabica and robusta green beans, its domestic decaffeination processing infrastructure is negligible, meaning nearly all decaf coffee products consumed domestically rely on imported roasted or pre-blended decaf stock. The variety pack format—offering multiple origins, roast profiles, or brew methods (whole bean, ground, single-serve pods) in a single retail unit—is particularly suited to exploration-oriented consumers and gift-buying occasions.
The product is defined as a tangible consumer packaged good sold through modern grocery, specialty food stores, e‑commerce platforms, and direct-to-consumer subscription channels. Key decaffeination methods represented in the Indonesian market include Swiss Water Process, CO₂ decaffeination, and direct solvent processes, though chemical-free claims are increasingly used as a premium positioning tool. The market is heavily influenced by import dynamics, branding strategies, and the degree of consumer education about decaf quality, rather than by upstream agricultural factors. Demand is concentrated in Java, Bali, and Sumatra’s urban centres, with Jakarta alone accounting for an estimated 30–40% of national decaf variety pack sales.
The overall Indonesia coffee retail market was valued in the range of USD 2.5–3.5 billion in 2025, with decaf coffee occupying a low-single-digit share. Decaf variety packs represent a subset of that decaf category, accounting for roughly 15–20% of decaf coffee sales by value, the rest being single-origin decaf bags or regular decaf blends. On a volume basis, the variety pack segment is estimated to have sold between 250 and 400 tonnes of decaf coffee equivalent in 2025, growing at a 12–15% compound rate over the prior three years, compared to 6–8% for the overall packaged coffee market.
From 2026 to 2035, demand is expected to maintain a trajectory of 9–13% annual growth in volume terms, driven by urbanisation, rising disposable incomes, and the mainstreaming of evening coffee consumption. The value growth rate will likely be higher, in the 11–16% range, as the mix shifts toward premium-process decaf and multi-format variety packs. By 2035, the segment could roughly triple in volume compared to 2026, though it will remain a niche—probably still below 3% of total coffee consumption in Indonesia—due to the strong cultural preference for traditional caffeinated coffee and the price premium of decaf.
Three format segments dominate the Indonesia decaf variety pack market. Ground decaf packs hold the largest share, approximately 40–45% of sales by volume, driven by compatibility with standard drip brewers and pour-over devices used in Indonesian households. Whole bean decaf packs account for 25–30%, favoured by specialty coffee enthusiasts who grind at home, while single-serve pod/capsule packs capture 18–22% and are the fastest-growing format, benefiting from the proliferation of Nespresso‑compatible and Dolce Gusto‑compatible systems in urban homes. Mixed-format discovery packs—containing a combination of whole bean, ground, and pods—represent less than 10% but carry the highest average selling price per gram and are heavily used in subscription and gift channels.
In terms of application, at-home consumption is the dominant end-use, accounting for 55–65% of variety pack sales. Office and workplace consumption (15–20%) is growing as corporate gifting programmes adopt decaf variety packs for wellness-focused employee incentives. Subscription/discovery services (10–15%) are the fastest channel, with monthly recurring deliveries of rotating decaf origins and methods. Hospitality and foodservice trial sizing (5–10%) remains small but strategically important for brand-building; hotels and upscale cafes use single-serve decaf packs as a guest amenity or tasting menu component.
Buyer groups span end consumers (direct-to-consumer e‑commerce and store purchases), grocery buyers managing category resets, specialty food store buyers, corporate procurement officers for gifting, and hotel food and beverage managers.
Retail pricing for decaf variety packs in Indonesia exhibits a wide range, from approximately IDR 45,000–60,000 per 250 g for a basic private‑label ground variety pack to IDR 120,000–200,000 per 250 g for a premium Swiss Water Process single‑origin whole bean discovery pack. The key cost drivers cascade from green bean commodity prices (arabica at approximately USD 2.50–4.00 per kg FOB origin), to the decaffeination premium (USD 1.00–2.50 per kg of green bean, depending on method and certification), to roasting, packaging, and branding margins. Variety packs incur additional costs from smaller batch sizes, multi‑origin sourcing, and custom packaging inserts.
The decaffeination premium is the single largest factor separating decaf from regular coffee prices. Chemical-free processes (Swiss Water, CO₂) command a 40–60% premium over conventional solvent decaf, and this differential is passed through to the retail level. Indonesian importers also face 5–10% import duties on finished roasted decaf coffee under HS codes 090121 and 090122, plus logistics costs from processing hubs in Switzerland, Germany, Canada, or the United States. As a result, decaf variety packs are priced 35–50% above equivalent regular coffee variety packs in Indonesian retail, which constrains adoption in lower‑income demographics but reinforces the premium “health and specialist” positioning that drives the higher‑margin segment.
The competitive landscape in Indonesia’s decaf variety pack market consists of three archetypes. Global brand owners and category leaders—such as Nestlé (Nescafé Gold Decaf, Dolce Gusto Decaf capsules), JAB Holding (Jacobs, Douwe Egberts), and illy—leverage established distribution networks and brand trust, offering decaf variety packs primarily through modern trade and e‑commerce platforms. Their market share is estimated at 40–50% by value, driven by strong shelf presence and promotional spending.
Specialty coffee roasters and direct-to-consumer brands account for 25–35% of the market. These include Indonesian roasters such as Anomali Coffee, Tanamera Coffee, and Common Grounds, which source decaffeinated green beans from overseas, roast in‑country, and assemble variety packs for their own cafes and online stores. They compete on origin storytelling and process transparency. Private‑label and retailer‑brand decaf variety packs (10–15% share) are offered by major grocery chains and discounters, typically sourced from contract roasters in Singapore or Malaysia.
Online‑first subscription boxes, both local (e.g., Kopi Pack, Month & Co.) and international (Bean Box, Trade Coffee), represent the fastest-growing competitive segment, though still small in absolute share (5–10%). Competition is intensifying, with price promotions and free‑shipping offers being the primary tools to drive trial in a category where repeat purchase is still being established.
Indonesia has no commercially significant domestic decaffeination plants. The country is a major producer of green coffee beans (ranked third or fourth globally), but virtually all beans destined for the domestic decaf market must be shipped to decaffeination facilities in Switzerland, Germany, Canada, or the United States for processing, then re‑imported as decaffeinated green beans or already roasted decaf coffee. A few specialty roasters, such as Tanamera Coffee, have experimented with small‑lot contract decaffeination runs in Europe and then bring the processed beans back to Indonesia for roasting and packaging.
The supply model is therefore import‑led. Monthly containerised shipments of decaffeinated green beans (typically 18–20 metric tonnes per container) arrive at Tanjung Priok (Jakarta) and Tanjung Perak (Surabaya) ports. Roasters in‑country perform the roasting, blending, grinding, and packaging functions required to assemble variety packs. Lead times from order of green decaf beans to finished packs on shelf range from 8 to 16 weeks, depending on shipping schedules and customs clearance. This structure makes the market vulnerable to global logistics disruptions and to capacity constraints at preferred decaffeination facilities, which often allocate capacity to larger Western buyers first. Domestic supply availability is thus a function of foreign processing capacity, not local agricultural output.
Indonesia is a net importer of decaffeinated coffee products. Customs data under HS codes 090121 (roasted, not decaffeinated) and 090122 (roasted, decaffeinated) indicate that over 90% of decaffeinated roasted coffee entering Indonesia comes from Switzerland, Germany, and the United States—countries that host the major decaffeination plants. Decaf variety packs, as manufactured consumer goods, are imported either as finished retail products (with branding and packaging already applied) or as bulk decaf roasted beans that are then packed locally. The latter route is preferred by domestic roasters because it allows customisation of the variety pack assortment and avoids higher duties on finished retail goods.
Trade flows are further complicated by the lack of preferential trade agreements between Indonesia and most decaffeination hubs, resulting in import duties of 5–10% on roasted decaf coffee plus 10% VAT. Re‑export of decaf coffee from Indonesia is negligible—the country’s role is that of a consumer market, not a processing hub. A small amount of decaf variety packs may be re‑exported to neighbouring countries (Singapore, Malaysia) as part of regional e‑commerce fulfilment, but this volume is below 2% of total imports. The trade structure underscores the market’s dependency on the efficiency and cost competitiveness of global decaffeination supply chains.
Modern grocery retailers (hypermarkets, supermarkets, and convenience stores) are the primary distribution channel for decaf variety packs in Indonesia, accounting for 50–55% of sales. Chains such as Transmart, Hypermart, Superindo, and Ranch Market stock both branded and private‑label decaf variety packs in dedicated coffee aisles and health‑food sections. Specialty food stores and coffee shops (15–20%) serve as discovery channels where consumers first encounter premium decaf variety packs, often through in‑cafe retail displays. E‑commerce platforms, led by Tokopedia, Shopee, and Lazada, together capture 20–25% of sales, with the share rising 3–5 percentage points per year as online grocery adoption deepens in urban areas.
Direct‑to‑consumer subscription models represent the smallest but most dynamic channel (5–10%). These buyers are typically middle‑ to high‑income urban consumers aged 25–45, purchasing out of interest in wellness and coffee exploration rather than daily necessity. Business buyers include corporate procurement managers (for gifting), hotel F&B directors, and office coffee service operators. Each buyer group has distinct purchasing criteria: grocery category managers focus on rotation speed and margin, while corporate buyers prioritise packaging aesthetics and delivery reliability. The distribution landscape is fragmenting as DTC brands bypass traditional retail margins, pressuring established brand owners to invest in their own e‑commerce storefronts and subscription offerings.
The primary regulatory framework for decaf coffee variety packs in Indonesia is the National Agency for Drug and Food Control (BPOM) regulation on processed food registration and labelling. All decaf coffee products must be registered with BPOM and bear a distribution permit number (MD/ML). Labelling requirements include a list of ingredients, nutrition information, net weight, and the declaration of “decaffeinated” if the caffeine content is below 0.1% on a dry‑weight basis. The use of specific decaffeination process claims (e.g., “Swiss Water Process”, “CO₂ decaffeinated”, “chemically free”) is permitted only if substantiated by a certificate of analysis from the processing facility. Misleading claims can result in permit suspension.
Additional voluntary certifications—Organic (SNI 6729 or international equivalents), Fair Trade, and Rainforest Alliance—are increasingly used as differentiators in the variety pack market, particularly by specialty roasters and DTC brands. The Indonesian National Standard (SNI) for coffee (SNI 01‑3542) sets limits on maximum allowable caffeine content for decaf (0.1% m/m), though enforcement in the variety pack segment relies on batch testing. E‑commerce regulations under Government Regulation No. 80/2019 require online sellers of processed foods to display BPOM registration numbers prominently.
As the category grows, BPOM is expected to issue more specific guidance on the labelling of variety packs that contain multiple roast profiles or origins, particularly regarding allergen cross‑contact and lot traceability across the pack’s components.
Over the 2026–2035 forecast horizon, the Indonesia decaf coffee variety pack market is projected to grow at a compound annual rate of 10–14% in value terms, outpacing both the regular coffee market (6–8%) and the broader packaged food segment. By 2035, the segment’s volume could double to 2.5–3 times the 2026 level, driven by three structural factors: the expansion of the health‑conscious middle class, the maturation of coffee culture in secondary cities (Bandung, Surabaya, Medan, Makassar), and the normalisation of evening coffee occasions as part of Indonesian social life.
Premium sub‑segments—single‑origin decaf packs with chemical‑free process claims, subscription discovery boxes, and limited‑edition variety packs—will gain share from entry‑level private‑label products, potentially accounting for 55–65% of segment value by 2035. Single‑serve pod variety packs will grow at the fastest rate (15–18% CAGR), while whole bean and ground formats see steady 8–11% growth. The market will remain import‑dependent, but a moderate increase in local roasting and packing of decaf beans (sourced from foreign decaffeination plants) could reduce landed costs by 5–10% relative to fully imported finished packs. Competitive intensity will rise as global brand owners deepen local distribution and small roasters scale their DTC operations, leading to margin compression in the mid‑priced tier.
The most significant opportunity lies in consumer education and trial conversion. With decaf variety pack penetration still under 2% of coffee‑drinking households, investments in experiential marketing—pop‑up tasting kiosks, workplace samplers, and influencer‑led brewing tutorials—can unlock a substantial latent demand. The evening and after‑dinner coffee occasion is virtually untapped in Indonesia; positioning decaf variety packs as the “perfect night‑cap coffee” could create a new daily usage ritual. Subscription models, in particular, offer a recurring revenue stream and a data loop to understand flavour preferences across regions and roast profiles.
A second opportunity is in the premium gifting segment. The variety pack format, with its visual differentiation and sampling value, is ideally suited for corporate gifts, festive hampers, and wedding favours. Brands that develop elegant, customisable packaging with local design cues can command wholesale prices 40–60% above standard retail. Furthermore, as the foodservice sector recovers and expands, hotels and cafes looking to differentiate their amenity programmes will seek out exclusive decaf variety packs tailored to their brand identity.
Finally, there is a structural opening for a domestic decaffeination facility—potentially in Java near major ports—to reduce import lead times and costs, although the capital investment (USD 10–20 million for a moderate‑scale plant) and reliance on specialty‑grade green bean supply remain significant barriers. For now, the most accessible opportunities are in branding, distribution, and direct consumer engagement, rather than upstream processing.
This report is an independent strategic category study of the market for decaf coffee variety pack in Indonesia. It is designed for brand owners, general managers, category leaders, trade-marketing teams, e-commerce teams, retail partners, distributors, investors, and market entrants that need a clear read on where growth sits, which brands control the category, how pricing and promotion shape demand, and which channels matter most for scale and margin.
The framework is built for Packaged Coffee & Beverages markets within consumer goods, where performance is driven by need states, shopper missions, brand hierarchies, price-pack architecture, retail execution, promotional intensity, and route-to-market control rather than by a narrow technical specification alone. It defines decaf coffee variety pack as A curated assortment of decaffeinated coffee products, typically including multiple roast profiles, origins, or brewing formats, sold as a single SKU for consumer trial, convenience, or subscription and maps the market through category boundaries, consumer segments, usage occasions, channel structure, brand and private-label positions, supply and availability logic, pricing and promotion mechanics, and country-level commercial roles. Historical analysis typically covers 2012 to 2025, with forward-looking scenarios through 2035.
This report is designed to answer the questions that matter most to brand, category, channel, and strategy teams in consumer-goods markets.
At its core, this report explains how the market for decaf coffee variety pack actually works as a consumer category. It is built to show where demand comes from, which need states and shopper missions matter most, which brands and private-label players shape the category, which channels control visibility and conversion, and where pricing power, repeat purchase, and margin are actually created.
Rather than framing the category through narrow technical attributes, the study breaks it into decision-grade commercial layers: product format, benefit platform, shopper segment, purchase occasion, pack-price architecture, channel environment, promotional intensity, route-to-market control, and company archetype. It is therefore useful both for teams shaping portfolio strategy and for teams executing growth through End Consumer (DTC), Grocery Retailer (Category Manager), Specialty Food Store Buyer, Corporate Procurement (Gifting), and Hospitality/Foodservice Buyer.
The report also clarifies how value pools differ across Daily caffeine-free consumption, Evening coffee occasion, Health-conscious & sensitive consumer routines, and Gifting & trial for new decaf drinkers, how premiumization and private label reshape category economics, how retail concentration and route-to-market design affect scale, and which countries matter most for brand building, sourcing, packaging, and channel expansion.
The report is based on an independent market-intelligence methodology that combines category reconstruction, public company evidence, retail and channel mapping, pricing review, and multi-layer triangulation. It is built for consumer categories where no single public dataset captures the real structure of demand, brand power, promotion, and channel control.
The evidence stack typically combines company disclosures, investor materials, brand and retailer product pages, e-commerce assortment checks, packaging and claims analysis, public pricing references, trade statistics where relevant, regulatory and labeling guidance, and observable route-to-market evidence from distributors, retailers, merchandisers, and marketplace ecosystems.
The analytical model then reconstructs the category across the layers that matter commercially: category scope, shopper need states, consumer segments, pack-price ladders, brand and private-label hierarchy, channel power, promotional intensity, route-to-market design, and country role differences.
Special attention is given to Health & wellness trends reducing caffeine intake, Evening/afternoon coffee occasion growth, Aging population & caffeine sensitivity, Premiumization & exploration in decaf segment, and Subscription & discovery box popularity. The objective is not only to size the market, but to explain where value pools sit, which segments drive mix and repeat purchase, which channels shape growth, and how leading brands defend or expand their positions across End Consumer (DTC), Grocery Retailer (Category Manager), Specialty Food Store Buyer, Corporate Procurement (Gifting), and Hospitality/Foodservice Buyer.
The report does not rely on survey-based opinion as its core evidence base. Instead, it uses observable commercial signals and structured public evidence to build a decision-grade view for brand, category, retail, e-commerce, investment, and market-entry teams.
This report defines decaf coffee variety pack as A curated assortment of decaffeinated coffee products, typically including multiple roast profiles, origins, or brewing formats, sold as a single SKU for consumer trial, convenience, or subscription and treats it as a branded consumer category rather than as a narrow technical product class. The objective is to capture the real commercial market that category, brand, trade-marketing, and channel teams are managing.
Scope is determined by how the category is sold, merchandised, priced, and chosen in market. That means the report follows product formats, claims, price tiers, pack architecture, need states, and retail environments that shape Daily caffeine-free consumption, Evening coffee occasion, Health-conscious & sensitive consumer routines, and Gifting & trial for new decaf drinkers.
The study deliberately separates the category from adjacent baskets when they distort the economics or shopper logic of the market being measured. Typical exclusions therefore include Single-variety decaf coffee bags, Caffeinated coffee variety packs, Instant decaf coffee jars, Ready-to-drink (RTD) decaf coffee beverages, Decaf tea or other caffeine-free products, Coffee equipment & brewers, Coffee syrups & flavorings, Caffeinated coffee subscriptions, Specialty tea samplers, and Functional beverage packs.
The report provides focused coverage of the Indonesia market and positions Indonesia within the wider global consumer-goods industry structure.
The geographic analysis explains local consumer demand conditions, brand and private-label balance, retail concentration, pricing tiers, import dependence, and the country’s strategic role in the wider category.
This study is designed for strategic and commercial users across brand-led consumer categories, including:
In many brand-driven, channel-sensitive, and consumer-demand-led markets, official trade and production statistics are not sufficient on their own to describe the true market. Product boundaries may cut across multiple tariff codes, several product categories may be bundled into the same official classification, and a meaningful share of activity may take place through customized services, captive supply, platform relationships, or technically specialized channels that are not directly visible in standard statistical datasets.
For this reason, the report is designed as a modeled strategic market study. It uses official and public evidence wherever it is reliable and scope-compatible, but it does not force the market into a purely statistical framework when doing so would reduce analytical quality. Instead, it reconstructs the market through the logic of demand, supply, technology, country roles, and company behavior.
This makes the report particularly well suited to products that are innovation-intensive, technically differentiated, capacity-constrained, platform-dependent, or commercially structured around specialized buyer-supplier relationships rather than standardized commodity trade.
The report typically includes: