The main tag of Gold Price Articles.
You can use the search box below to find what you need.
[wd_asp id=1]
The main tag of Gold Price Articles.
You can use the search box below to find what you need.
[wd_asp id=1]
The OPEC+ group may not have any options left to counter the extreme bearishness in oil markets by further restricting supply. Bullish sentiment is likely to re-emerge if there is good news on the demand front.
For now, good news about oil demand looks a distant prospect, especially after the end of the peak summer driving season. Concerns about the Chinese economy and the country’s oil demand add to worries about slowing economic growth in the developed economies to depress markets. These concerns have prompted analysts and investment banks to lower their oil price forecasts for the end of the year.
OPEC Starts Trimming Demand Growth Forecasts
Following the recent slide in oil toward the low $70s per barrel, the OPEC+ alliance delayed the beginning of the unwinding of 2.2 million barrels per day (bpd) of cuts by two months until December 2024.
The decision did little to lift oil prices—the market was half expecting a delay, especially after OPEC cut in August its global oil demand growth view citing weakness in China.
Related: Oil Prices Rise on Jumbo Fed Rate Cut
In its monthly report for September, OPEC further trimmed its demand growth outlook and further weighed on oil prices and market sentiment.
In just two months, demand worries have flipped the bullish view of traders and speculators to the most bearish positioning in petroleum futures in recorded history since 2011.
Money managers seem to have concluded that OPEC+ can’t or won’t announce additional production cuts to prop up prices, energy analyst John Kemp writes in his blog.
Most Bearish Positioning Ever
Signs of weak demand and weakening refining margins have weighed on oil prices and market sentiment, prompting speculators and money managers to slash their bullish bet on oil futures to the lowest on record dating back to 2011.
In the week ended September 10, money managers held a net short position in Brent for the first time in recorded history, since 2011.
The net length—the difference between bullish and bearish bets—flipped to a net short in the reporting week to September 10, as speculators and traders remained concerned about lower-than-expected global oil demand growth. Weakness in Chinese economic indicators and falling refining margins exacerbated the bearish sentiment on oil in the first two weeks of September.
Moreover, persistent weakness across the refined fuel market helped drive an increase in the net short position in the European and U.S. diesel futures.
“Combining the five major crude and fuel contracts, the net long of these fell to the lowest level since 2011, when the ICE Exchange started to collect Brent and gas oil data,” Ole Hansen, Head of Commodity Strategy at Saxo Bank, wrote this week, commenting on the latest commitment of traders (COT) report.
Ripe for Rally?
Of course, the exceptionally bearish positioning in oil lays the foundations for a rally in which traders will look to cover their shorts. However, the market will need a flip in the narrative in demand for a rebound.
Right now, there aren’t signs that demand is accelerating while supply continues to be steady. If the three OPEC+ overproducers, Iraq, Russia, and Kazakhstan, stick to their compensation schedules, some supply would come off the market in the coming months.
But will this be enough to prevent an oversupply next year?
Many banks say no.
Weaker-than-expected demand is set to tip the oil market into a surplus over the next five quarters, Macquarie said last week as it lowered its Brent and WTI oil forecasts for the rest of the year.
“As we enter shoulder and turnaround season, the ‘last hurrah’ for oil in the form of Q3 tightness is quickly fading as our balances contemplate heavy oversupply across the next five quarters,” Macquarie analysts wrote in a note.
Just two weeks after lowering its Brent estimate to $80 per barrel for the fourth quarter, Morgan Stanley cut its forecast again, now expecting the international benchmark to average $75 a barrel in the last quarter of the year. Analysts at Morgan Stanley see rising headwinds on the demand side, which has been their key reason for cutting their Q4 oil price forecast.
Weaker Chinese oil demand, high inventories, and rising U.S. shale production have prompted Goldman Sachs to reduce its expected range for Brent oil prices by $5 to $70-$85 per barrel.
Citi expects oil at $60 per barrel in 2025 if OPEC+ doesn’t implement additional cuts to its production.
So far, the group has not signaled any intention to deepen the output cuts.
Analysts assume that OPEC+ will begin unwinding some of the current cuts early next year. Combined with rising non-OPEC+ supply, this will tip the market into oversupply for most of 2025, according to banks and analysts.
A rebound in demand would be most welcome by oil bulls, but as-is, no signs have emerged in recent weeks about positive demand figures. Refining margins are falling and leading to reduced refinery run rates in Asia and Europe.
By Tsveana Paraskova for Oilprice.com
The time of year is typically bullish, not only due to the end of hurricane season, but the fact that colder temperatures are coming to the northeastern part of the United States. That of course drives up demand and therefore price. Keep in mind that the CFD that you are trading in the natural gas markets are based on futures contracts. And therefore, you’re actually thinking about winter at this point.
Short-term pullbacks, I do think find plenty of support near the $2.80 level, and then again at the $2.65 level. On the upside, I think that the $3.15 level will continue to be a little bit resistive, but I think we’re basically just digesting a lot of the gains that we’ve recently seen, and when you look at the action over the last two weeks or so, we have seen a shot higher, but it does look a little limp, so I think it wouldn’t take too much to cause the pullback to occur, which of course I think only ends up offering value.
For a look at all of today’s economic events, check out our economic calendar.
Silver (XAG/USD) struggles to capitalize on the overnight bounce from the vicinity of the $30.00 psychological mark, or a three-week low and trades with a negative bias for the third successive day on Wednesday. The white metal is currently placed just above the mid-$30.00s and seems vulnerable to prolonging its retracement slide from the highest level since December 2012 touched last week.
From a technical perspective, the recent repeated failures to find acceptance above the $32.00 mark constitute the formation of a bearish multiple-tops pattern on the daily chart. Moreover, oscillators on the daily chart have started gaining negative traction and validate the near-term bearish outlook for the XAG/USD. Hence, a subsequent slide below the $30.00 mark, towards testing the next relevant support near the $29.75-$29.60 confluence, looks like a distinct possibility.
The latter comprises the 100-day Simple Moving Average (SMA) and the 50-day SMA, which if broken decisively should pave the way for a further near-term depreciating move. The XAG/USD might then accelerate the fall towards the $29.00 mark and eventually drop to the $28.60-$28.50 support zone.
On the flip side, any attempted recovery might now confront immediate resistance and remain capped near the $31.00 mark. That said, a sustained move beyond could trigger a short-covering move and lift the XAG/USD to the $31.55 hurdle en route to the $31.75-$31.80 region and the $32.00 mark. This is followed by the $32.25 supply zone, above which the white metal could aim to challenge the multi-year peak and make a fresh attempt to conquer the $33.00 round figure.
Silver is a precious metal highly traded among investors. It has been historically used as a store of value and a medium of exchange. Although less popular than Gold, traders may turn to Silver to diversify their investment portfolio, for its intrinsic value or as a potential hedge during high-inflation periods. Investors can buy physical Silver, in coins or in bars, or trade it through vehicles such as Exchange Traded Funds, which track its price on international markets.
Silver prices can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can make Silver price escalate due to its safe-haven status, although to a lesser extent than Gold’s. As a yieldless asset, Silver tends to rise with lower interest rates. Its moves also depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAG/USD). A strong Dollar tends to keep the price of Silver at bay, whereas a weaker Dollar is likely to propel prices up. Other factors such as investment demand, mining supply – Silver is much more abundant than Gold – and recycling rates can also affect prices.
Silver is widely used in industry, particularly in sectors such as electronics or solar energy, as it has one of the highest electric conductivity of all metals – more than Copper and Gold. A surge in demand can increase prices, while a decline tends to lower them. Dynamics in the US, Chinese and Indian economies can also contribute to price swings: for the US and particularly China, their big industrial sectors use Silver in various processes; in India, consumers’ demand for the precious metal for jewellery also plays a key role in setting prices.
Silver prices tend to follow Gold’s moves. When Gold prices rise, Silver typically follows suit, as their status as safe-haven assets is similar. The Gold/Silver ratio, which shows the number of ounces of Silver needed to equal the value of one ounce of Gold, may help to determine the relative valuation between both metals. Some investors may consider a high ratio as an indicator that Silver is undervalued, or Gold is overvalued. On the contrary, a low ratio might suggest that Gold is undervalued relative to Silver.
Tata Coffee Share Price Target The National Stock Exchange (NSE) and the Bombay Stock Exchange (BSE) both list Tata Coffee Ltd. as a firm. We will examine the TATACOFFEE share price target for 2024, 2025, 2026, and up to 2030 in this in-depth essay. various technical analysis techniques to predict objectives through 2030 for long-term forecasts.
We will employ a machine learning technique, where the predicted data is based on historical performance, to project the price of TATACOFFEE through 2030. Over the years, Tata Coffee Ltd., which is well-known for its substantial position in the Indian share market, has demonstrated a number of patterns. This section covers the market position that TATACOFFEE now holds, its projected growth trajectory, and potential external market influences on its pricing performance through 2030. If you are a day trader, though, you can look up TATACOFFEE’s price goal for tomorrow.
In 2023, the majority of Indian stocks, including TATACOFFEE, saw an amazing bull run. The market’s optimistic outlook is expected to persist in the first quarter of 2024, despite the first months of consolidation. Technical research indicates that TATACOFFEE’s minimum share price objective for 2024 is anticipated to be ₹366.12, while the highest price target is anticipated to be ₹456.76.
| Month | Target |
|---|---|
| April 2024 target for TATACOFFEE | ₹366.12 |
| May 2024 target for TATACOFFEE | ₹377.45 |
| June 2024 target for TATACOFFEE | ₹388.78 |
| July 2024 target for TATACOFFEE | ₹400.11 |
| August 2024 target for TATACOFFEE | ₹411.44 |
| September 2024 target for TATACOFFEE | ₹422.77 |
| October 2024 target for TATACOFFEE | ₹434.1 |
| November 2024 target for TATACOFFEE | ₹445.43 |
| December 2024 target for TATACOFFEE | ₹456.76 |
By January 2025, the share price of TATACOFFEE is anticipate to have increase to Rs. 466. By December 2025, if the industry trend and macro and microeconomic factors continue to support them, the target price of Tata Coffee Ltd. might rise to Rs 523.
| Month | Target |
|---|---|
| January 2025 target for TATACOFFEE | ₹466 |
| February 2025 target for TATACOFFEE | ₹475 |
| March 2025 target for TATACOFFEE | ₹485 |
| April 2025 target for TATACOFFEE | ₹469 |
| May 2025 target for TATACOFFEE | ₹453 |
| June 2025 target for TATACOFFEE | ₹438 |
| July 2025 target for TATACOFFEE | ₹456 |
| August 2025 target for TATACOFFEE | ₹474 |
| September 2025 target for TATACOFFEE | ₹493 |
| October 2025 target for TATACOFFEE | ₹503 |
| November 2025 target for TATACOFFEE | ₹513 |
| December 2025 target for TATACOFFEE | ₹523 |
Zomato Share Price Target 2024
Adani Green Energy Share Price Target 2024
Technical analysis indicates that TATACOFFEE’s minimum share price objective is anticipated to reach Rs. 533, while the maximum value that TATACOFFEE shares can achieve is Rs. 600.
| Month | Target |
|---|---|
| January 2026 target for TATACOFFEE | ₹533 |
| February 2026 target for TATACOFFEE | ₹544 |
| March 2026 target for TATACOFFEE | ₹555 |
| April 2026 target for TATACOFFEE | ₹537 |
| May 2026 target for TATACOFFEE | ₹519 |
| June 2026 target for TATACOFFEE | ₹502 |
| July 2026 target for TATACOFFEE | ₹522 |
| August 2026 target for TATACOFFEE | ₹543 |
| September 2026 target for TATACOFFEE | ₹565 |
| October 2026 target for TATACOFFEE | ₹576 |
| November 2026 target for TATACOFFEE | ₹588 |
| December 2026 target for TATACOFFEE | ₹600 |
Based on Fibonacci estimates, Tata Coffee Ltd. (TATACOFFEE) is expect to trade between ₹612 and ₹575 in the first half of 2027. The price of a TATACOFFEE share could hit ₹686 by the second half of 2027.
| Month | Target |
|---|---|
| January 2027 target for TATACOFFEE | ₹612 |
| February 2027 target for TATACOFFEE | ₹624 |
| March 2027 target for TATACOFFEE | ₹636 |
| April 2027 target for TATACOFFEE | ₹615 |
| May 2027 target for TATACOFFEE | ₹595 |
| June 2027 target for TATACOFFEE | ₹575 |
| July 2027 target for TATACOFFEE | ₹598 |
| August 2027 target for TATACOFFEE | ₹622 |
| September 2027 target for TATACOFFEE | ₹647 |
| October 2027 target for TATACOFFEE | ₹660 |
| November 2027 target for TATACOFFEE | ₹673 |
| December 2027 target for TATACOFFEE | ₹686 |
| Month | Target |
|---|---|
| January 2028 target for TATACOFFEE | ₹700 |
| February 2028 target for TATACOFFEE | ₹714 |
| March 2028 target for TATACOFFEE | ₹728 |
| April 2028 target for TATACOFFEE | ₹704 |
| May 2028 target for TATACOFFEE | ₹681 |
| June 2028 target for TATACOFFEE | ₹658 |
| July 2028 target for TATACOFFEE | ₹684 |
| August 2028 target for TATACOFFEE | ₹711 |
| September 2028 target for TATACOFFEE | ₹739 |
| October 2028 target for TATACOFFEE | ₹754 |
| November 2028 target for TATACOFFEE | ₹769 |
| December 2028 target for TATACOFFEE | ₹784 |
| Month | Target |
|---|---|
| January 2029 target for TATACOFFEE | ₹800 |
| February 2029 target for TATACOFFEE | ₹816 |
| March 2029 target for TATACOFFEE | ₹832 |
| April 2029 target for TATACOFFEE | ₹804 |
| May 2029 target for TATACOFFEE | ₹777 |
| June 2029 target for TATACOFFEE | ₹751 |
| July 2029 target for TATACOFFEE | ₹781 |
| August 2029 target for TATACOFFEE | ₹812 |
| September 2029 target for TATACOFFEE | ₹844 |
| October 2029 target for TATACOFFEE | ₹861 |
| November 2029 target for TATACOFFEE | ₹878 |
| December 2029 target for TATACOFFEE | ₹896 |
RPOWER Share Price Target 2024
| Year | Initial Target | Mid-Year Target | Year-End Target |
|---|---|---|---|
| 2024 | ₹366.12 | ₹422.77 | ₹456.76 |
| 2025 | ₹466 | ₹438 | ₹523 |
| 2026 | ₹533 | ₹502 | ₹600 |
| 2027 | ₹612 | ₹575 | ₹686 |
| 2028 | ₹700 | ₹658 | ₹784 |
| 2029 | ₹800 | ₹751 | ₹896 |
| 2030 | ₹914 | ₹858 | ₹1024 |
Tata Power Share Price Target 2024
To sum up, using the most recent trade data and algorithms. We have produced the TATACOFFEE share price target for 2024, 2025, 2026, and up to 2030. For the upcoming years, these goals represent possible levels of support and resistance.
It’s important to remember that although technical analysis forms the basis of these price estimates. News and other market factors may also have an impact on the stock’s performance. Thus, rather than serving as financial advice. These fictitious aims should be used as guides. Make sure you do your own research before investing in anything.
Gold price is taking a breather in the lead-up to the release of the Minutes of the US Federal Reserve (Fed) September policy meeting due later on Wednesday.
In Wednesday’s Asian trading, Gold price is attempting a tepid bounce, snapping a five-day downtrend. Gold traders eagerly await the Fed Minutes to assess the scale of the next interest rate cut, especially after Friday’s strong US Nonfarm Payrolls data took bets for a 50 basis points (bps) rate reduction off the table.
The Fed Minutes of the September meeting will likely show discussions about the labor market and inflation outlook, as well as, on the way forward on the interest rates. Lately, Fed policymakers continued to deliver dovish messages at their respective appearances, although maintaining a non-committal stance on the size of the next rate cut.
Bets for a smaller Fed rate cut have already weighed on Gold price so far this week, as buyers now seem to lack a bullish conviction due to mounting Chinese economic concerns on the lack of further stimulus announced by China. The Dragon Nation is the world’s top yellow metal consumer, and hence, rising economic worries could weigh over the physical demand for Gold from Chinese consumers.
The safe-haven Gold price, however, continues to find a ‘dip-buying’ demand, as escalating tensions between Israel and Iran raise risks of the conflict turning into a wider regional war.
Reuters reported early Wednesday, Israel Prime Minister Benjamin Netanyahu said Israeli airstrikes had killed two successors to Hezbollah’s slain leader, as Israel expanded its ground offensive against the Iran-backed group with a fourth army division deployed into south Lebanon.”
Ahead of the Fed Minutes, Gold price could find some trading incentives from speeches by Fed Vice Chair Philip Jefferson and San Francisco Fed President Mary Daly. Fed official Jerfferson said earlier on, the decision for a 50 bps rate cut in September “was timely and consistent” with the Fed’s two mandates of attaining 2% inflation and maximum employment.
Gold price outlook remains constructive from a short-term technical perspective even though sellers cracked the key static support of $2,630 on a daily closing basis.
The 14-day Relative Strength Index (RSI) is in a recovery mode while holding above the midline, currently near 56. This suggests that a Gold price rebound could be in the offing.
On the downside, the 21-day Simple Moving Average (SMA) at $2,619 must be defended to revive the upward trajectory to record highs.
A failure to do so will recall sellers, triggering a fresh sell-off in Gold price toward the $2,600 threshold. Additional downside pressure could target the September 20 low of $2,585.
On the flip side, Gold price needs a daily candlestick closing above the $2,650 psychological barrier to take on the lifetime high of $2,686 again.
Ahead of that, the strong resistance near $2,670 will come into play.
(This story was corrected on October 9 at 06:30 GMT to say that “Gold price outlook remains constructive from a short-term technical perspective even though sellers cracked the key static support,” not buyers.)
FOMC stands for The Federal Open Market Committee that organizes 8 meetings in a year and reviews economic and financial conditions, determines the appropriate stance of monetary policy and assesses the risks to its long-run goals of price stability and sustainable economic growth. FOMC Minutes are released by the Board of Governors of the Federal Reserve and are a clear guide to the future US interest rate policy.
Next release: Wed Oct 09, 2024 18:00
Frequency: Irregular
Consensus: –
Previous: –
Source: Federal Reserve
Silver (XAG/USD) struggles to capitalize on the overnight bounce from the vicinity of the $30.00 psychological mark, or a three-week low and trades with a negative bias for the third successive day on Wednesday. The white metal is currently placed just above the mid-$30.00s and seems vulnerable to prolonging its retracement slide from the highest level since December 2012 touched last week.
From a technical perspective, the recent repeated failures to find acceptance above the $32.00 mark constitute the formation of a bearish multiple-tops pattern on the daily chart. Moreover, oscillators on the daily chart have started gaining negative traction and validate the near-term bearish outlook for the XAG/USD. Hence, a subsequent slide below the $30.00 mark, towards testing the next relevant support near the $29.75-$29.60 confluence, looks like a distinct possibility.
The latter comprises the 100-day Simple Moving Average (SMA) and the 50-day SMA, which if broken decisively should pave the way for a further near-term depreciating move. The XAG/USD might then accelerate the fall towards the $29.00 mark and eventually drop to the $28.60-$28.50 support zone.
On the flip side, any attempted recovery might now confront immediate resistance and remain capped near the $31.00 mark. That said, a sustained move beyond could trigger a short-covering move and lift the XAG/USD to the $31.55 hurdle en route to the $31.75-$31.80 region and the $32.00 mark. This is followed by the $32.25 supply zone, above which the white metal could aim to challenge the multi-year peak and make a fresh attempt to conquer the $33.00 round figure.
Silver is a precious metal highly traded among investors. It has been historically used as a store of value and a medium of exchange. Although less popular than Gold, traders may turn to Silver to diversify their investment portfolio, for its intrinsic value or as a potential hedge during high-inflation periods. Investors can buy physical Silver, in coins or in bars, or trade it through vehicles such as Exchange Traded Funds, which track its price on international markets.
Silver prices can move due to a wide range of factors. Geopolitical instability or fears of a deep recession can make Silver price escalate due to its safe-haven status, although to a lesser extent than Gold’s. As a yieldless asset, Silver tends to rise with lower interest rates. Its moves also depend on how the US Dollar (USD) behaves as the asset is priced in dollars (XAG/USD). A strong Dollar tends to keep the price of Silver at bay, whereas a weaker Dollar is likely to propel prices up. Other factors such as investment demand, mining supply – Silver is much more abundant than Gold – and recycling rates can also affect prices.
Silver is widely used in industry, particularly in sectors such as electronics or solar energy, as it has one of the highest electric conductivity of all metals – more than Copper and Gold. A surge in demand can increase prices, while a decline tends to lower them. Dynamics in the US, Chinese and Indian economies can also contribute to price swings: for the US and particularly China, their big industrial sectors use Silver in various processes; in India, consumers’ demand for the precious metal for jewellery also plays a key role in setting prices.
Silver prices tend to follow Gold’s moves. When Gold prices rise, Silver typically follows suit, as their status as safe-haven assets is similar. The Gold/Silver ratio, which shows the number of ounces of Silver needed to equal the value of one ounce of Gold, may help to determine the relative valuation between both metals. Some investors may consider a high ratio as an indicator that Silver is undervalued, or Gold is overvalued. On the contrary, a low ratio might suggest that Gold is undervalued relative to Silver.
Morgan Stanley has bumped its forecast for Brent crude oil in the final quarter of 2024 to $80 / Barrel
MS cite heightened geopolitical risk.
MS are wary though, saying demand is weaker than expected and supply has been robust. And thus warn of a widening surplus in the market into next year.
—
Oil update, dipped back from its recent high on Wednesday:
Most Read: USD/CHF Technical Outlook: Confluence Area Hints at Bullish Breakout
Gold prices tumbled in today’s US session having enjoyed a positive European session to say the least. The precious metal rallied from a low of 2628 in the European session to trade at a high of 2652 before the US open.
The US session however brought some renewed US Dollar strength, as Gold’s appeal appears to be waning. This was also the first US trading session since the National Development and Reform commission in China provided a briefing on the recent stimulus measures. The address today however failed to deliver any new measures and concern still lingers among many market participants.
China, the largest global consumer of metals, has dampened metals demand for over two years. Despite the Peoples Bank of China buying significant amounts of Gold there have been growing concerns of a widespread economic slowdown, especially the property sector crisis, has pressured copper and other industrial metals. Despite numerous property support measures this year, they have yet to significantly boost metals demand.
This renewed concern around China could not have come at a worse time for Gold Bulls. The aggressive repricing of rate cuts over the last few days coupled with the lack of response to the Iranian missile attack has formed the perfect cocktail for a pullback in Gold prices.
The question is whether this is the end of the bullish rally?
That is a very nuanced question given the various factors at play. For one though, the Middle East crisis is far from being resolved and the chance of escalation is certainly higher following the Iranian missile attack last week. There is bound to be an Israeli response which Iran has vowed will be met by a new attack as well.
These dynamics mean the Middle East situation could still blowover reigniting the safe haven appeal of Gold. Looking even further down the line, the World Gold Council September report was released today.
According to the latest World Gold Council (WGC) report, net ETF inflows increased again in September. ETF flow levels are often seen as a strong indicator of future demand trends. Gold-backed ETFs added 18 tonnes of gold in September, bringing total holdings to 3,200 tonnes. This led to cumulative inflows of $1.4 billion for the month, marking the fifth consecutive month of inflows.
This data follows similar trends in August, when Gold ETFs saw $2.1 billion in inflows, and July, which recorded $3.7 billion—the highest since April 2022.
Source: WGC Report (click to enlarge)
This coupled with the World Gold Council survey of Central Banks earlier this year hint that Gold demand is to remain strong in the medium to longer term. This would suggest that support for Gold remains and thus the current pullback could just be another false dawn. Either way i am intrigued to see how far today’s pullback may run.
FOMC minutes will be released tomorrow in what I expect to be a non-event following the jobs data release last week. The Fed meeting on September 18 would likely have been dominated by concern around an ailing labor market which last week’s jobs report put to bed for the time being.
US CPI on Thursday is likely to be the next major market moving event, however tomorrow’s list of Fed Speakers may also contribute to some volatility.

For all market-moving economic releases and events, see the MarketPulse Economic Calendar. (click to enlarge)
From a technical analysis standpoint, Gold had been caught in a tight range of around $30 since the start of October. There were brief tests below the 2640 handle in recent days but the four-hour candle always closed back inside the range low at 2640.
The breakout today has been quite aggressive with Gold reaching a low around the 2604 handle before bouncing to trade around 2614 at the time of writing. As mentioned technically Gold is due for a deeper pullback but the fundamental risks continue to underpin prices and keep selling pressure at bay.
If the selloff continues tomorrow, immediate support rests around 2600 before the 2574 handle comes into focus. 2574 could prove a tough hurdle to clear as just below it rests the 200-day MA making this a key area of confluence that could find some buying pressure.
Alternatively, a recovery from here may face a challenge at 2624 before the 100-day MA at 2630 becomes key. Beyond that and the previous H4 range low at 2640 could be key for bulls to regain control of the narrative moving forward.
GOLD (XAU/USD) Four-Hour (H4) Chart, October 8, 2024

Source: TradingView (click to enlarge)
Support
Resistance
Follow Zain on Twitter/X for Additional Market News and Insights @zvawda
Content is for general information purposes only. It is not investment advice or a solution to buy or sell securities. Opinions are the authors; not necessarily that of OANDA Business Information & Services, Inc. or any of its affiliates, subsidiaries, officers or directors. If you would like to reproduce or redistribute any of the content found on MarketPulse, an award winning forex, commodities and global indices analysis and news site service produced by OANDA Business Information & Services, Inc., please access the RSS feed or contact us at info@marketpulse.com. Visit https://www.marketpulse.com/ to find out more about the beat of the global markets. © 2023 OANDA Business Information & Services Inc.

He has spent the last 3 years in an analyst role honing his skills across various financial domains, including technical analysis, economic data interpretation, price action strategies, and analyzing the geopolitical impacts on global markets. Currently, Zain is advancing in obtaining his Capital Markets & Security Analyst (CMSA) designation through the Corporate Finance Institute (CFI), where he has completed modules in fixed income fundamentals, portfolio management fundamentals, equity market fundamentals, introduction to capital markets, and derivative fundamentals.
He is also a regular guest on radio and television programs in South Africa, providing insight into global markets and the economy. Additionally, he has contributed to the development of a financial markets course approved by BankSeta (Banking Sector Education and Training Authority) at NQF level 6 in South Africa.

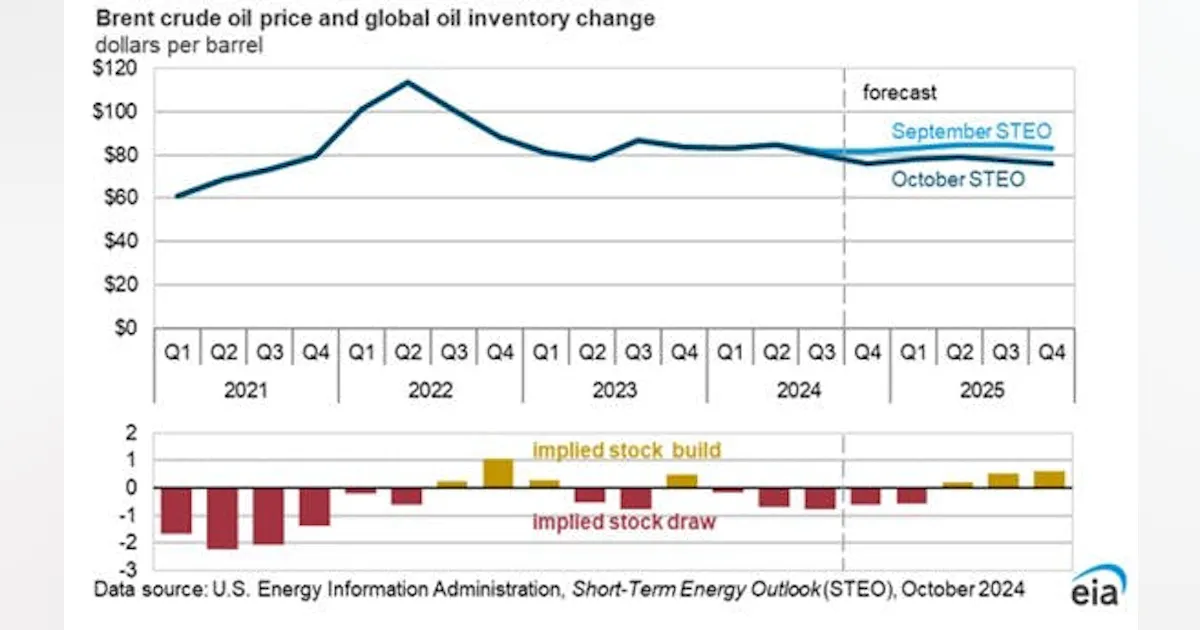
In the October Short-Term Energy Outlook (STEO), the US Energy Information Administration (EIA) lowered its Brent crude oil spot price forecast through end-2025.
The latest outlook predicts an average Brent price of $78/bbl in 2025, $7/bbl less than last month’s forecast. Lower crude oil prices largely reflect a reduction for global oil demand growth in 2025, according to EIA.
“We forecast that global consumption of liquid fuels will increase by 900,000 b/d in 2024 and 1.3 million b/d in 2025. Our 2024 forecast is down from last month due to downward revisions to demand in China and our 2025 forecast is down primarily because of downward revisions to demand in OECD countries,” EIA said.
“We reduced our forecast for China’s liquid fuels consumption in 2024 because of continued declines in the country’s crude oil imports and refinery runs in third quarter 2024. Although the Chinese government recently announced monetary stimulus measures that could result in higher economic growth and petroleum consumption in 2025, we have kept our forecast 2025 growth rate largely unchanged. We forecast China’s petroleum and liquid fuels consumption will grow by about 100,000 b/d in 2024 and 300,000 b/d in 2025,” the report continued.
“We reduced our forecast of total OECD oil consumption by 200,000 b/d in 2025 compared with last month’s STEO as a result of weaker expectations for industrial production and manufacturing growth in the US and Canada.”
Most of EIA’s expected global liquid fuels demand growth is from non-OECD countries where liquid fuels consumption increases by 1 million b/d in 2024 and 1.2 million b/d in 2025, in contrast to consumption in OECD countries, which falls by 100,000 b/d in 2024 before increasing by a similar amount in 2025.
“Although we reduced our crude oil price forecast, crude oil prices have risen in recent days because of escalating conflict in the Middle East, raising the possibility of oil supply disruptions and further crude oil price increases,” EIA noted.
The Brent crude oil spot price averaged $74/bbl in September, a decrease of $6/bbl from August. Prices dropped as concerns over global oil demand growth outweighed reductions in oil inventories and OPEC+ members’ decision to delay production increases until December 2024. However, after recent military actions involving Israel, Lebanon, and Iran, the Brent spot price increased to $79/bbl on Oct. 4, up 11% from the previous week.
“The potential for further escalation– such as an Israeli response to Iran’s missile attack on October 1– have injected significant uncertainty and volatility into oil markets in recent days. Following the September drop in prices and our expectation that oil demand growth will be lower next year than we had previously forecast, we have lowered our forecast for crude oil prices despite increasing oil prices in early October. We now expect Brent will average $78/b in 2025, $7/bbl less than our forecast from last month,” EIA said.
EIA anticipates that production growth outside of OPEC+ will remain strong over the forecast period, and as a result OPEC+ producers will likely keep production less than their recently announced targets for much of next year.
EIA expects that global production of petroleum and other liquid fuels will increase by 2 million b/d in 2025, up from growth of just 500,000 b/d this year. Countries outside of OPEC+ are expected to increase production by 1.4 million b/d next year, while OPEC+ production will increase by 700,000 b/d, after the voluntary cuts reduced OPEC+ production by 1.3 million b/d this year.
“In addition to voluntary cuts to OPEC+ production, a force majeure in Libya in August and September reduced oil production. We estimate Libya’s crude oil production fell to 400,000 b/d in September 2024 from nearly 1.2 million b/d in July 2024 before the disruptions began,” EIA said.
“As of early October, it appears the cause of the disruption has come to a resolution, with affected production potentially restarting in October. We assume Libya’s oil production will average 600,000 b/d for the rest of this year.”
EIA also revised its estimate of Iraq’s crude oil production, including historical production, up by an average of 200,000 b/d in 2024 to account for assessment that more crude oil is being used in new refining capacity in Iraq than the agency had previously determined.
“Although we raised our assessment of Iraq’s oil production, we still estimate that Iraq cut its crude oil production by 300,000 b/d from July through September 2024 to comply with OPEC+ production quotas.”
In this month’s outlook, EIA educed its 2025 forecast for US Lower 48 states (L48) crude oil production from last month by 1% to 11.3 million b/d. This reduction reflects a downward revision to EIA’s West Texas Intermediate (WTI) crude oil price forecast.
EIA now expects WTI will average $72/bbl in fourth-quarter 2024, about $6/bbl lower than last month’s forecast. Because there is about a 6-month lag between price changes and producer activity, the recent price declines will begin reducing US crude oil production in mid-2025. By December 2025, US L48 crude oil production will be 11.4 million b/d, 2% lower than EIA’s September STEO forecast.
The Arabica coffee bean prices is not merely a simple figure; it results from the complex interplay of numerous natural, economic, market, and geopolitical factors. This article delves into the analysis of the factors influencing the price of Arabica coffee beans, offering an overview of historical price fluctuations and providing forecasts for future price trends. By thoroughly understanding the drivers behind Arabica price volatility, we can better assess its impact on the coffee industry as a whole and the livelihoods of millions of people involved in the coffee value chain.
Arabica coffee accounts for about 60-70% of global coffee production and is considered the highest-quality coffee. Its price has far-reaching effects for several reasons:
Global Supply Chain: Arabica prices directly affect the income of millions of coffee farmers in developing countries such as Brazil, Colombia, Ethiopia, and Vietnam. Price fluctuations can significantly impact their livelihoods.
Market Benchmarking: Arabica prices are often used as a benchmark for pricing other coffee varieties, including Robusta. Hence, it indirectly influences the entire coffee market.
Impact on Consumers: When Arabica prices rise, roasters and retailers often have to increase the prices of their final products, directly affecting the cost for consumers enjoying their coffee.
Economic Impact: For major coffee-exporting countries, Arabica price volatility can significantly influence GDP and the trade balance.
Product Quality and Diversity: Pricing affects the ability of farmers and producers to invest in quality and innovation, which, in turn, influences the diversity and quality of coffee products in the market.
a) Climate:
b) Soil Conditions:
a) Supply and demand:
b) Production costs:
c) Government policies:
a) Futures trading:
b) Speculation:
c) Consumer trends:

Chart of Price Fluctuations for Robusta and Arabica Coffee Each Year
a) Wars and conflicts:
Conflicts in major coffee-producing countries can disrupt supply chains and drive prices higher.
b) Economic crises:
Global economic downturns can reduce coffee consumption, impacting prices.
c) Trade policies:
Trade agreements or barriers (such as tariffs) can affect the flow of coffee on the international market, influencing prices.
2000-2005: Period of low prices
2006-2011: Period of strong price growth
Supply shortages due to severe droughts in Brazil (2007-2008) and heavy rains in Colombia (2009-2010).
Strong market speculation due to the 2008 financial crisis.
Growth of the specialty coffee industry, increasing demand for high-quality Arabica.

High profits for farmers, but also creates challenges for roasters and retailers in maintaining profit margins
2012-2019: Period of price decline and relative stability
Strong production recovery, particularly in Brazil, thanks to investment in farming technologies and new coffee varieties.
Growth of Vietnam’s coffee industry, primarily Robusta, but also influencing overall supply-demand dynamics.
Depreciation of the Brazilian real against the USD, encouraging exports and lowering global coffee prices.
2020-2023: Period of extreme volatility due to pandemic and climate extremes
2020: The COVID-19 pandemic caused initial price declines due to demand concerns, followed by price increases due to supply chain disruptions.
2021: Severe frost in Brazil (July 2021) destroyed around 20% of the crop, pushing prices to a seven-year high.
2022-2023: Global inflation and ongoing supply chain disruptions continued to cause price volatility.
Impact: Rising costs across the coffee value chain, from farmers to end consumers.
Brazil’s role
Climate change
Consumption demand
Farming technology
Environmental and sustainability policies
Price increase scenario
Price decrease scenario
Stable price scenario
Extreme climate risk
Increasing likelihood of abnormal weather events (e.g., El Niño, La Niña), which could cause unexpected supply shocks, leading to significant price volatility.

Climate change is one of the top issues in the coffee industry as a whole.
Geopolitical risks
Macroeconomic risks
Pandemic risks
Conclusion:
Arabica coffee prices are complex, reflecting interactions among various natural, economic, political, and social factors. As climate change and global challenges intensify, accurately forecasting Arabica coffee price trends has become more difficult than ever. However, by thoroughly understanding the influencing factors and analyzing historical trends, we can make reasonable predictions about the future of Arabica coffee prices.
Arabica coffee is typically more expensive than Robusta for several reasons:
Fluctuations in Arabica coffee prices affect coffee shop prices in various ways:
No, Arabica coffee quality can vary significantly:
Consumers can manage rising Arabica coffee prices by:
Climate change may severely impact the future of Arabica coffee:
These challenges may lead to scarcity and higher prices for Arabica coffee in the future, driving the need for innovation in the global coffee industry.