The main tag of GoldPrice Articles.
You can use the search box below to find what you need.
[wd_asp id=1]
The main tag of GoldPrice Articles.
You can use the search box below to find what you need.
[wd_asp id=1]
Natural gas price provided more of the mixed trading by reaching $2.750 level, keeping the positive stability above the support level at $2.620, as its stability reinforces the chances of activating the bullish trend in the near period.
Stochastic stability above 50 level will increase the chances of gathering positive momentum, to keep our bullish scenario by its rally towards $2.920, then to repeat the pressure at $3.100 barrier.
The expected trading range for today is between $2.700 and $2.920
Trend forecast: Bullish
The GBPJPY pair repeated providing weak sideways trading by its stability near 208.45 level, affected by the continuation of forming an obstacle at 280.10 level against the attempts of resuming the bearish trend, noticing the attempt of stochastic to exit the oversold level, which reinforces the dominance of the sideways range bias in the current trading, with a chance to retest the initial barrier near 210.40.
Achieving the required break and holding below 208.10 level will confirm its readiness to target more negative stations by reaching 206.70 initially, followed by 205.85.
The expected trading range for today is between 208.10 and 209.45
Trend forecast: Fluctuating within the bearish trend
Domestic coffee prices
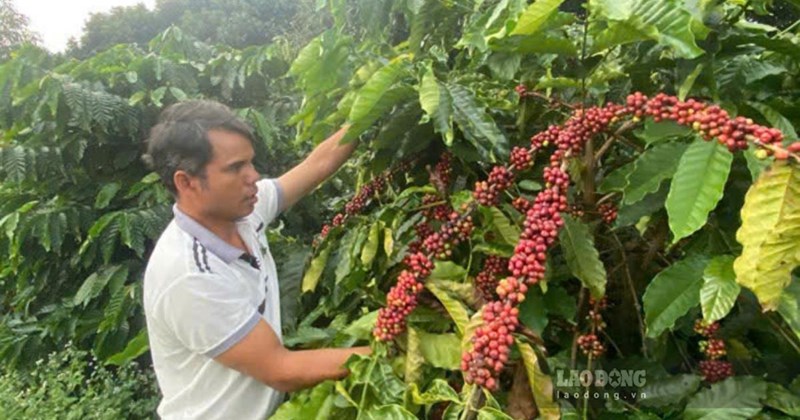
Coffee prices today in the domestic market increased by at least 200 VND/kg. According to giacaphe. com, the average coffee price on September 11 remained at 95,700 VND/kg, anchored in the price range of 95,200-95,800 VND/kg.
In Gia Lai and Dak Lak, coffee prices were recorded at 95,700 VND/kg, an increase of 200 VND/kg.
In Lam Dong, the listed coffee price is at 95,200 VND/kg, an increase of 200 VND/kg.
The old Dak Nong area alone increased by 300 VND/kg, recording a level of 95,800 VND/kg.
The USD/VND exchange rate according to Vietcombank was recorded at 25,710 VND/USD, down 40 VND/USD.
World coffee prices
In the world market, coffee prices increase and decrease interspersed.
According to Barchart, the September 2026 Robusta futures contract today maintained an increase of 14 USD/ton, anchored at the mark of 3,442 USD/ton. In the same direction, the November 2026 term was listed at 3,554 USD/ton, an additional increase of 82 USD/ton. The term from January 2027 to May 2027 witnessed the highest increase of 48 USD/ton, to 3,472 – 3,510 USD/ton.
Meanwhile, the September 2026 Arabica futures contract decreased by 3.9 cents/lb (equivalent to 1.22%), down to the 315.30 cent/lb mark. The December 2026 term has the same decrease, offered to the market at a price of 288.15 cents/lb. Further forwards are anchored in the 274.65 – 279.45 cent/lb range, down from 4.20-4.60 cents/lb.

Assessments and forecasts
Coffee prices fluctuated in opposite directions, with Arabica falling to a 7-week low, while Robusta rose to a 1.5-week high. Arabica coffee prices fell in yesterday’s trading session after the International Coffee Organization (ICO) issued a forecast for record global coffee production and oversupply.
ICO forecasts that global coffee production in the 2025/26 crop year will increase by 4.4% compared to the same period, reaching a record 183.6 million bags, while consumption will decrease by 0.9% to 180.6 million bags. This caused the global coffee market to have a surplus of 3 million bags, marking the first time the market has had oversupply in 5 years.
Brazil’s termination of the coffee harvest is boosting arabica supply and putting pressure on prices.
In addition, higher rainfall than normal in Brazil may promote the flowering process for next year’s coffee crop, thereby becoming a factor putting downward pressure on prices.
Robusta coffee prices are supported by concerns that heavy rain in the Central Highlands of Vietnam, the largest coffee production region in the country, could flood farms and damage the coffee crop.
In Thursday’s session last week, Robusta prices fell to a 3-month low due to signs that coffee supply from Vietnam, the world’s largest Robusta producer, is increasing.
Concerns that the El Nino weather phenomenon may cause damage to the Brazilian coffee crop next year are also factors supporting prices. El Nino may cause rainfall in Brazil to be delayed in September and October, when coffee trees usually bloom, thereby affecting the 2026/27 Brazilian coffee crop.
TradingKey – On September 10 Eastern Time, the three major US stock indices fell for the fourth consecutive trading day. US August PPI showed upstream price pressures continued to rise, while international oil prices surged further, with WTI crude breaking back above $100 a barrel, bolstering expectations for a September Fed rate hike. US Treasury yields continued to climb, putting pressure on tech stocks and high-valuation assets, as market focus shifted to Friday’s upcoming US August CPI data.
At the close, the Dow Jones Industrial Average fell 0.61% to 52,069.22; the S&P 500 Index dropped 0.58% to 7,591.70; and the Nasdaq Composite Index slipped 0.65% to 26,081.72.
In sector and individual stock moves, semiconductor shares came under pressure. Nvidia (NVDA) fell 2.37%, while Micron Technology (MU) dropped 4.9%, ranking among the major tech heavyweights dragging down the S&P 500. Apple (AAPL) bucked the trend to rise 3.56% as investors continued to digest the company’s newly released $1,999 foldable iPhone.
In commodities, oil prices became the day’s most significant market driver. Brent crude (UKOIL) surged 7.43% to settle at $109.30 a barrel; WTI crude (USOIL) rose 7.51% to close at $103.94, reclaiming $100 for the first time since May. Military actions between Iran and the US targeting oil tankers continued to escalate, while Houthi forces took control of Yemen’s Mocha port, further elevating the risk of Red Sea shipping disruptions.
In precious metals, gold (XAUUSD) fell 1.94% to close at $4,316.64. Rising US PPI and oil prices fueled expectations for Fed rate hikes, while a strengthening US dollar and higher Treasury yields added pressure on gold.
In cryptocurrencies, Bitcoin (BTCUSD) remained under pressure, dropping 2.22%. Following the release of US PPI data, Bitcoin briefly slipped below $77,000, having previously traded mainly around $78,000. Oil prices breaking above $100 and rising US Treasury yields kept short-term crypto trading focused primarily on Fed policy expectations rather than industry-specific factors.
U.S. August PPI rose 0.4% month-over-month, rising to 5.4% year-over-year. Data from the U.S. Department of Labor showed that the Producer Price Index for August rose 0.4% month-over-month, in line with market expectations and higher than the revised 0.1% in July; the year-over-year gain accelerated from 4.8% to 5.4%. Among components, energy prices rose 4.2% in a single month, with diesel prices surging 24.1%. Following the release of the data, market expectations for a 25-basis-point rate hike by the Federal Reserve in September rose from around 62% to 70%.
Average U.S. diesel price tops $6 per gallon for the first time in history. GasBuddy data showed that the average national diesel price rose above $6 per gallon for the first time on Thursday. Because diesel is widely used in trucking, logistics, and agriculture, high fuel costs could further pass through to goods and service prices, drawing increased attention to the impact of rising oil prices on U.S. inflation.
Middle East conflict expands further as both WTI and Brent top $100. Iran claimed it had attacked 10 vessels near the Strait of Hormuz, while the U.S. struck five Iranian tankers. Meanwhile, Iran-backed Houthi rebels seized control of Yemen’s Mocha port, extending supply risks from the Strait of Hormuz to the Red Sea. OPEC also lowered its 2026 global oil demand growth forecast to 380,000 barrels per day, but supply disruption risks continue to dominate short-term oil prices.
ECB raises interest rates by another 25 bps, pushing deposit rate to 2.5%. The European Central Bank raised interest rates for the second time this year, primarily to address energy inflation triggered by the war in the Middle East. The ECB expects the average inflation rate in the eurozone to reach 3.0% in 2026 and upgraded its economic growth forecast from 0.8% to 0.9%. Lagarde stated that there remain clear upside risks to the inflation outlook.
Oracle beats earnings expectations, shares up about 4% after hours. Oracle (ORCL) reported a 30% year-over-year increase in first-quarter revenue to $19.3 billion, topping market expectations of $19.14 billion; adjusted EPS came in at $1.92, above the expected $1.74. The company added more than $30 billion in new AI cloud contracts during the quarter, bringing its remaining performance obligations to $664 billion, and raised its fiscal 2027 adjusted EPS forecast to $8.10.
Adobe beats revenue and earnings estimates, but shares fall about 2% after hours. Adobe (ADBE) posted third-quarter revenue of $6.76 billion, beating market estimates of $6.7 billion; adjusted EPS was $6.13, also topping expectations of $6.09. However, the midpoint of the company’s fourth-quarter revenue guidance was approximately $6.825 billion, slightly below market expectations of $6.85 billion, sending its stock down about 1.9% in after-hours trading.
Pentagon reportedly considering $5 billion loan to AI cloud company Fluidstack. The U.S. Department of Defense is discussing providing a loan of approximately $5 billion to Fluidstack through its Office of Strategic Capital, according to The Wall Street Journal. The funds will primarily be used to strengthen the supply chain and manufacturing capabilities for U.S. data center components, rather than directly constructing new AI data centers. The plan reflects that the U.S. government is increasingly viewing AI infrastructure as a strategic industry.
U.S. decision on refined copper tariffs reportedly delayed. Sources said the White House is still evaluating the pros and cons of imposing tariffs on refined copper, partly out of concern that higher copper prices could further push up manufacturing costs. Following the reports, copper prices fell more than 4%, while copper mining stocks such as Freeport-McMoRan plunged in tandem.
The table below lists the ten most actively traded stocks in the market. Supported by massive trading volumes and excellent liquidity, these assets have become key benchmarks for tracking global market dynamics.
This content was translated using AI and reviewed for clarity. It is for informational purposes only.
Domestic coffee prices
Today’s coffee prices in the domestic market mostly remained in the old price range, except for the old Dak Nong area. According to giacaphe. com, the average coffee price on September 10 remained at 95,500 VND/kg, down slightly 100 VND/kg.
In Gia Lai and Dak Lak, coffee prices were recorded at 95,500 VND/kg.
In Lam Dong, the listed coffee price is at 95,000 VND/kg.
The old Dak Nong area alone decreased by 300 VND/kg, recording a level of 95,500 VND/kg.
The USD/VND exchange rate according to Vietcombank is recorded at 25,750 VND/USD.
World coffee prices
In the world market, coffee prices are filled with green color on all terms.
According to Barchart, the September 2026 Robusta futures contract today reversed to increase by 14 USD/ton, anchored at the mark of 3,442 USD/ton. In the opposite direction, the November 2026 futures were listed at 3,472 USD/ton, up 14 USD/ton. The term from January 2027 to May 2027 witnessed the highest increase of 19 USD/ton, to 3,439 – 3,462 USD/ton.
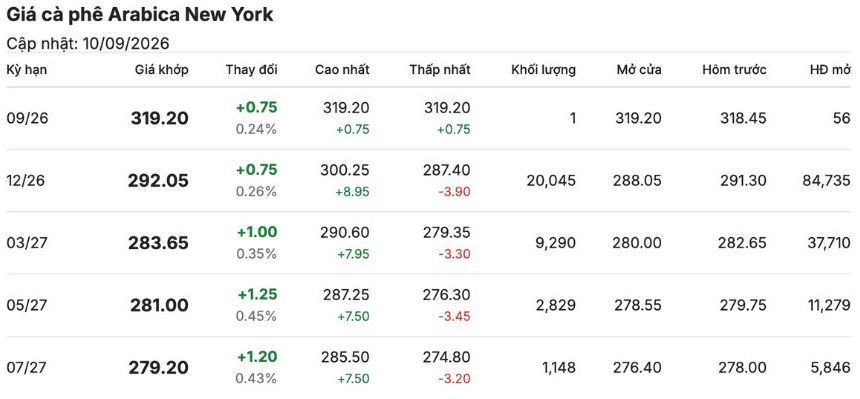
In the same direction, Arabica futures for September 2026 increased slightly by 0.75 cents/lb (equivalent to 0.24%), reaching 319.20 cents/lb. For December 2026, with the same increase, it was offered to the market at a price of 292.05 cents/lb. Further forwards are anchored in the range of 279.2 – 283.65 cents/lb.
Assessments and forecasts
Coffee prices closed the session up, with Robusta reaching a 1-week high. Short-term supply contraction is a factor supporting Arabica coffee prices, as Arabica inventories at ICE fell to a 27-year low, to 218,838 bags on Tuesday.
Robusta coffee prices are also supported by concerns that heavy rain in the Central Highlands of Vietnam, the largest coffee production region in the country, could flood farms and damage the coffee crop.
Coffee exports increased sharply from Vietnam, the world’s largest Robusta producer, which is a factor putting pressure on Robusta prices. Vietnam’s coffee exports in 2025 increased by 17.5% compared to the previous year, to 1.58 million tons. In addition, Vietnam’s coffee production in the 2025/26 crop is forecast to increase by 6% compared to the same period, reaching the highest level in 4 years at 1.76 million tons, equivalent to 29.4 million bags.
The US Department of Agriculture (USDA) forecasts global Arabica production to increase by 12% over the same period, while Robusta production is forecast to decrease by 0.7%. Global end-of-year inventories are forecast to increase by an additional 1.9 million bags, to 26.3 million bags.
HSBC has sharply raised its Brent crude price forecast for 2026, lifting its outlook from $80 to $90 per barrel as the crisis in the Strait of Hormuz drags on with no resolution in sight. The bank’s senior oil analyst, Kim Fustier, said global oil markets are unlikely to find balance again until the middle of 2027, a timeline that points to months of tight supply and elevated prices ahead.
HSBC’s revision marks one of the clearest signals yet that major banks now view the Hormuz disruption as a lasting feature of the oil market rather than a passing shock. The bank’s updated Brent crude price forecast reflects a market where supply constraints are expected to persist well into next year, not just through the current quarter.
The 2026 forecast climbed from $80 to $90 per barrel, but the more striking move came further out. HSBC also raised its 2027 Brent outlook to $85 per barrel, up sharply from a prior $65 estimate. That’s a $20 jump for a year in which, in calmer conditions, analysts might have expected prices to have already normalized. Looking further ahead, HSBC’s assumption for 2028 and beyond sits at $75 per barrel, suggesting the bank sees some cooling off eventually, but not a full return to the sub-$70 environment that prevailed before the crisis began.
Brent crude prices have climbed past $100 per barrel lately amid intensifying shipping attacks in the region, yet HSBC’s updated figures—though lower than current spot prices—reflect the bank’s outlook for where prices will land once the initial panic subsides. That distinction matters: a forecast below the current trading price isn’t a bet on relief so much as a signal that HSBC views today’s premium as partly driven by short-term volatility on top of a genuinely tighter underlying supply picture.
The Strait of Hormuz oil crisis is the reason behind HSBC’s entire recalibration. This narrow waterway between Iran and Oman normally carries roughly a fifth of the world’s daily oil consumption, and its disruption has rewritten supply assumptions across the industry.
Oil flows through the strait have stabilized at around 6 million barrels per day, about 30% of pre-conflict levels, according to HSBC’s analysis. That collapse followed a failed diplomatic push: a US-Iran memorandum of understanding designed to stabilize transit through the strait fell apart in July 2026, removing the market’s main hope for a quick fix. Fustier’s note comes in the direct aftermath of that failure, and it explains why HSBC is no longer treating the disruption as temporary.
Why it matters: a fifth of global oil consumption depends on a waterway that is currently operating at less than a third of its normal throughput. Any further deterioration in the diplomatic relationship between Washington and Tehran could keep that bottleneck in place for far longer than markets initially priced in.
HSBC does still see a path back toward normal, just a slow one. By mid-2027, the bank projects flows will climb to 9.5 million bpd, following a gradual rise to 8 million bpd by the end of 2026. Even under that relatively optimistic trajectory, transit volumes would remain well below historical norms for more than a year, which is exactly why the bank pushed its 2027 forecast up so aggressively.
HSBC’s global oil supply disruption scenario isn’t the only possible outcome, and the bank has laid out what happens if diplomacy keeps failing instead of stabilizing.
In a stalemate scenario, where negotiations keep collapsing and transit volumes stay depressed, Fustier’s analysis points to Brent surging as high as $120 per barrel before moderating sometime in 2027. That figure underscores how sensitive this market remains to political developments in the Gulf: a single failed round of talks, as seen in July 2026, was enough to force a $10 upward revision in the 2026 forecast alone.
Beyond the immediate volatility, HSBC’s broader HSBC oil price outlook assumes the market eventually settles into a new, somewhat higher normal. The bank’s 2028-and-beyond assumption of $75 per barrel implies that even a resolved Hormuz crisis would leave a lasting mark on pricing, since rebuilding shipping confidence and restoring full transit volumes tends to take longer than the initial disruption itself. Until flows return closer to their pre-conflict baseline, oil markets are unlikely to rebalance, and HSBC’s own timeline for that puts the turning point around the middle of 2027.
HSBC raised its 2026 Brent crude price forecast because the crisis in the Strait of Hormuz remains unresolved, causing prolonged disruptions to global oil supply.
Oil flows through the strait have dropped to around 6 million barrels per day, about 30% of the volume seen before the conflict began.
HSBC expects oil flows to gradually recover to 8 million barrels per day by the end of 2026 and 9.5 million barrels per day by mid-2027.
If diplomatic efforts keep failing, HSBC’s analysis suggests Brent crude prices could spike to $120 per barrel before moderating sometime in 2027.
Article produced with the assistance of artificial intelligence and reviewed by the editorial team.
Welcome, my fellow traders! I have prepared a price forecast for US Crude, XAUUSD, and EURUSD using a combination of the margin zones method and technical analysis. Based on the market analysis, I suggest entry signals for intraday traders.
Gold continues to trade in a short-term downtrend.
The article covers the following subjects:
Yesterday, the oil price continued to rise, reaching the Target Zone 2 of 94.49–93.68. Today, the price tried to break through this zone, but bears defended it. If the asset remains below the Target Zone 2, a correction may start.
Should a correction develop, the price may fall to the support zone A of 90.65–90.22. Once this zone is tested, consider long trades, with the first target at 92.61 and the second one around 95.01.
Buy near support A of 90.65–90.22. TakeProfit: 92.61, 95.01. StopLoss: 89.07.
Gold extends its short-term downtrend. The price is trading below resistance B of 4,451–4,436. Earlier this week, the asset reached the first bearish target of 4,367. The second target is at 4,282. Consequently, consider holding short trades or opening new ones today.
A breakout above 4,464 will invalidate the bearish scenario. In that case, the short-term trend will turn bullish, and one may consider long trades, targeting the upper Target Zone of 4,621–4,590.
Hold part of the short trades opened at resistance B of 4,451–4,436. TakeProfit: 4,282. StopLoss: at breakeven.
The euro is attempting to continue its short-term uptrend. The second bullish target is at 1.1711. Therefore, consider holding some of the long trades opened earlier near support B of 1.1585–1.1572.
If the EURUSD pair declines and settles below support B, the trend may turn bearish. In this case, consider short trades the next trading day, with a target in the lower Target Zone of 1.1459–1.1434.
Hold part of the long trades opened at support B of 1.1585–1.1572. TakeProfit: 1.1711. StopLoss: at breakeven.
Would you like to learn more about technical analysis methods and principles? Explore our comprehensive guide.
P.S. Did you like my article? Share it in social networks: it will be the best “thank you” 🙂
Useful links:
The content of this article reflects the author’s opinion and does not necessarily reflect the official position of LiteFinance broker. The material published on this page is provided for informational purposes only and should not be considered as the provision of investment advice for the purposes of Directive 2014/65/EU.
According to copyright law, this article is considered intellectual property, which includes a prohibition on copying and distributing it without consent.
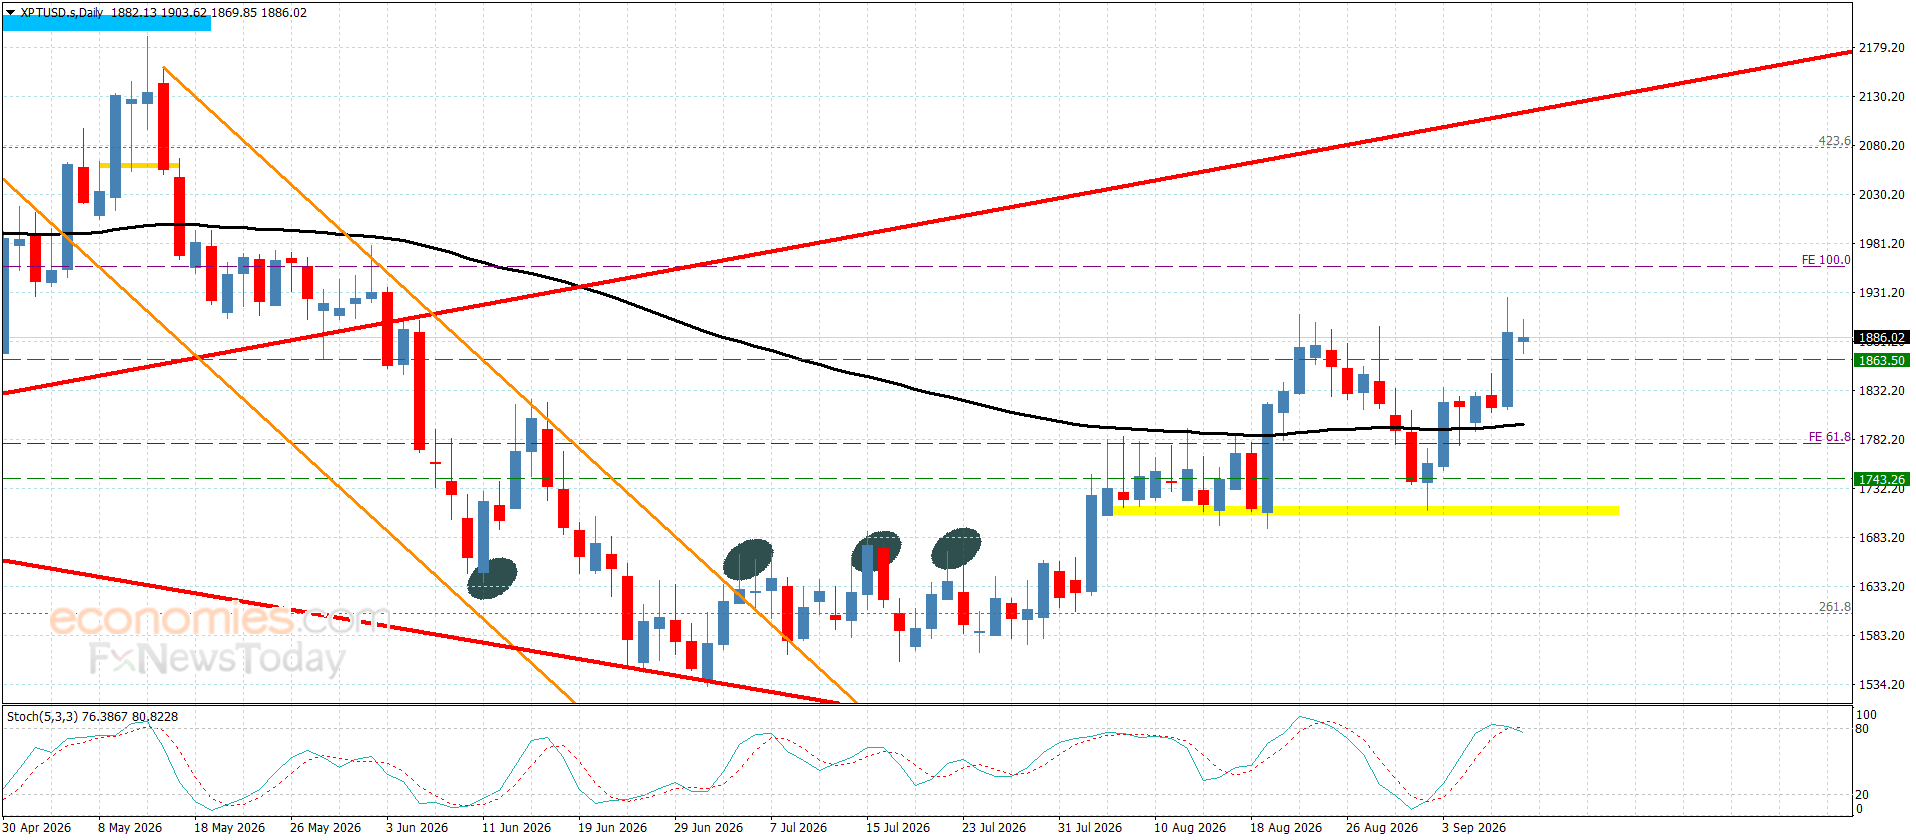
Platinum price succeeded in surpassing $1835.00 level yesterday, reaching the initial target by hitting $1926.00 level, despite the positive factors, we confirm the stability of the trading above $1900.00 to reinforce the chances of resuming the bullish trend and targeting new positive targets by reaching $1958.00 initially, followed by $2060.00, which represents the next main target in the medium trading.
While the price failure to settle above $1900.00 might force it to activate the corrective attempts, to expect reaching the 55-level moving average near $1790.00.
The expected trading range for today is between $1850.00 and $1958.00
Trend forecast: Bullish
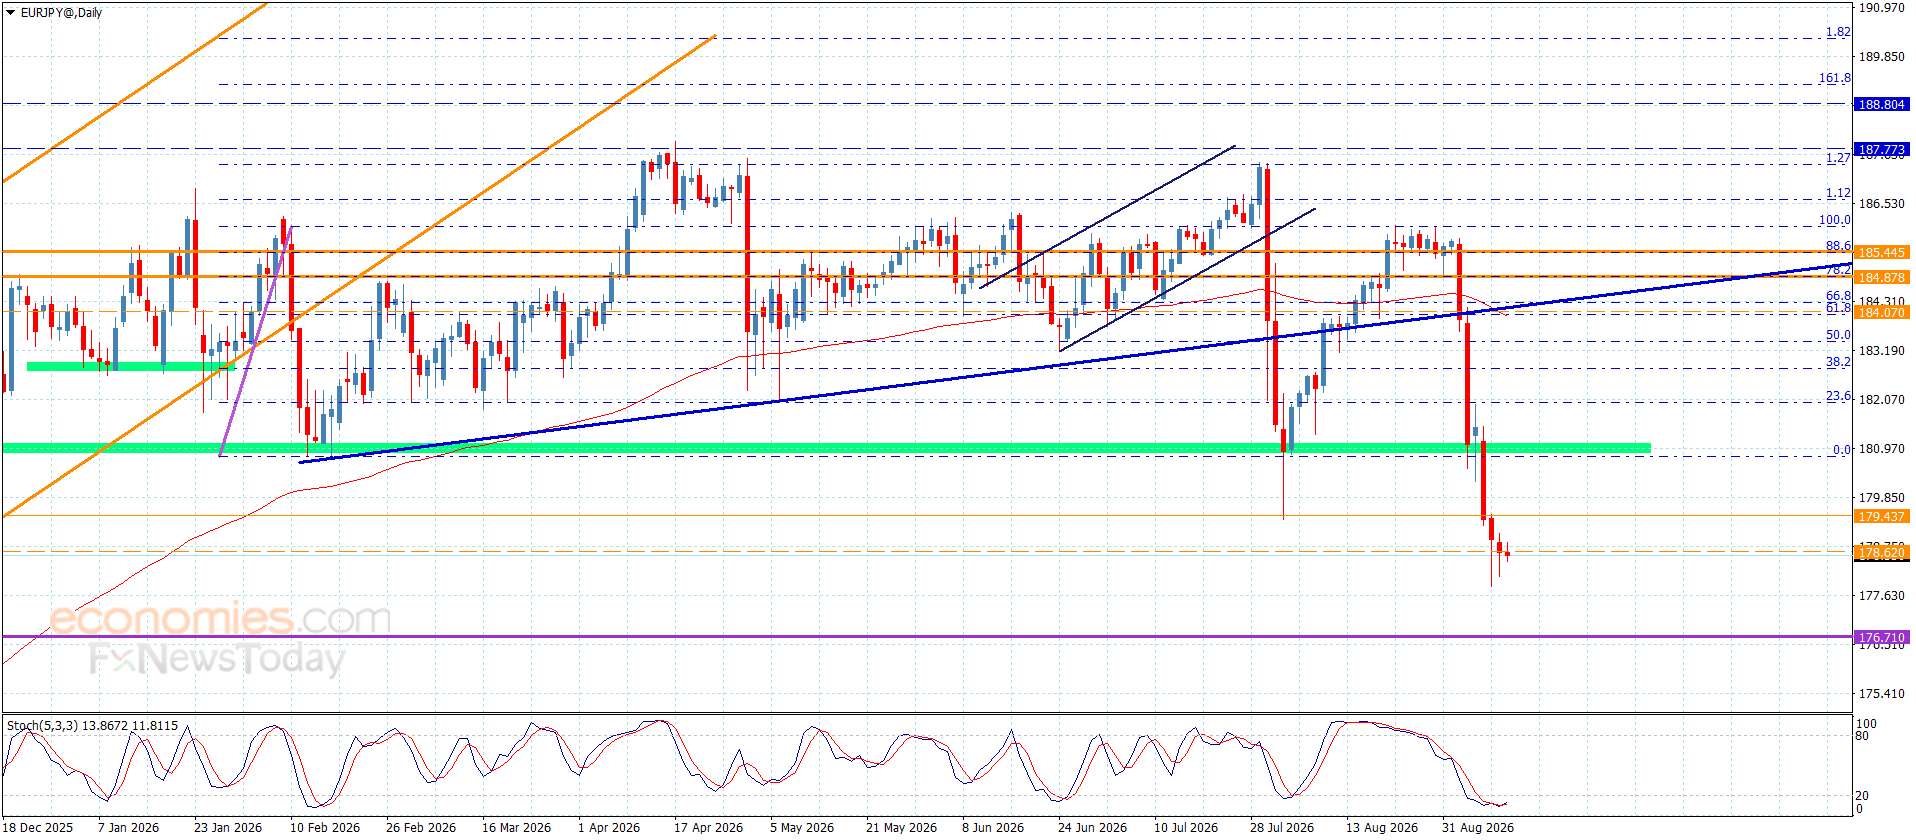
Despite the weakness of the last trading of EURJPY pair’s price and forming weak sideways fluctuation by its stability near 178.50, it will not affect the main bearish scenario due to its stability below 180.80 barrier.
Providing negative momentum continuously by the main indicators will increase the chances of attacking 177.80 barrier, as surpassing it will open the way for reaching extra negative stations that are represented by 177.35 and 176.70 level.
The expected trading range for today is between 177.35 and 179.40
Trend forecast: Bearish
Brent crude futures rose $2.15, or 2.2%, to $100.07 a barrel by 0721 GMT, while U.S. West Texas Intermediate crude was up $1.70, or 1.83%, at $94.73 a barrel.
Brent has risen by a quarter since early last month as hopes fade for a permanent resolution to the six-month-old conflict between the U.S. and Iran.
U.S. Secretary of State Marco Rubio said Washington would continue targeting Iranian oil tankers in response to attempted attacks on U.S. warships. “Iran continues to try to hit U.S. naval ships, and for every time they do that or try to do that, they’re going to lose tankers,” Rubio told reporters during a visit to Colombia.
U.S. Central Command said on Tuesday that its forces had destroyed five Iranian crude oil carriers on September 8 following attempted missile attacks on a U.S. Navy warship over the previous two days.
Jordan’s air-defence systems intercepted 18 of the 20 ballistic missiles launched from Iranian territory, while the other two fell in unpopulated areas, according to the country’s state news agency, which cited the military. No casualties were reported.
Goldman Sachs has warned that oil prices could reach as high as $120 a barrel if attacks on shipping in the Middle East intensify, with the renewed hostilities raising concerns about disruptions to crude supplies.Daan Struyven, co-head of global commodities research at Goldman Sachs, said in an interview with Bloomberg that recent developments indicated that the risk of wider and more severe shipping disruptions had become an important concern.
Struyven said Goldman Sachs sees “meaningful upside to crude oil prices”, while also suggesting that investors position for higher natural gas and refined product prices. He said the supply shocks in gas and fuels are larger than those in the crude market.
The duration of the disruption will be critical for the oil market. JPMorgan estimates that every additional month of disruption could add around $7 to $8 a barrel to Brent prices. If the disruption lasts three months, the bank expects average monthly Brent prices to reach around $114 a barrel.
Citi has raised its average Brent crude price forecast for the third quarter to $86 a barrel from $80, pointing to a longer-than-expected timeline for the reopening of the Strait of Hormuz.
ANZ analysts have also increased their short-term Brent forecast to $95 a barrel and warned that prices could rise further if the Middle East conflict escalates. They said a prolonged standoff involving calibrated military action by the U.S. and Iran appeared to be the most likely scenario, potentially delaying the return of full Middle East supply.
(Disclaimer: Recommendations, suggestions, views and opinions given by the experts are their own. These do not represent the views of The Economic Times)