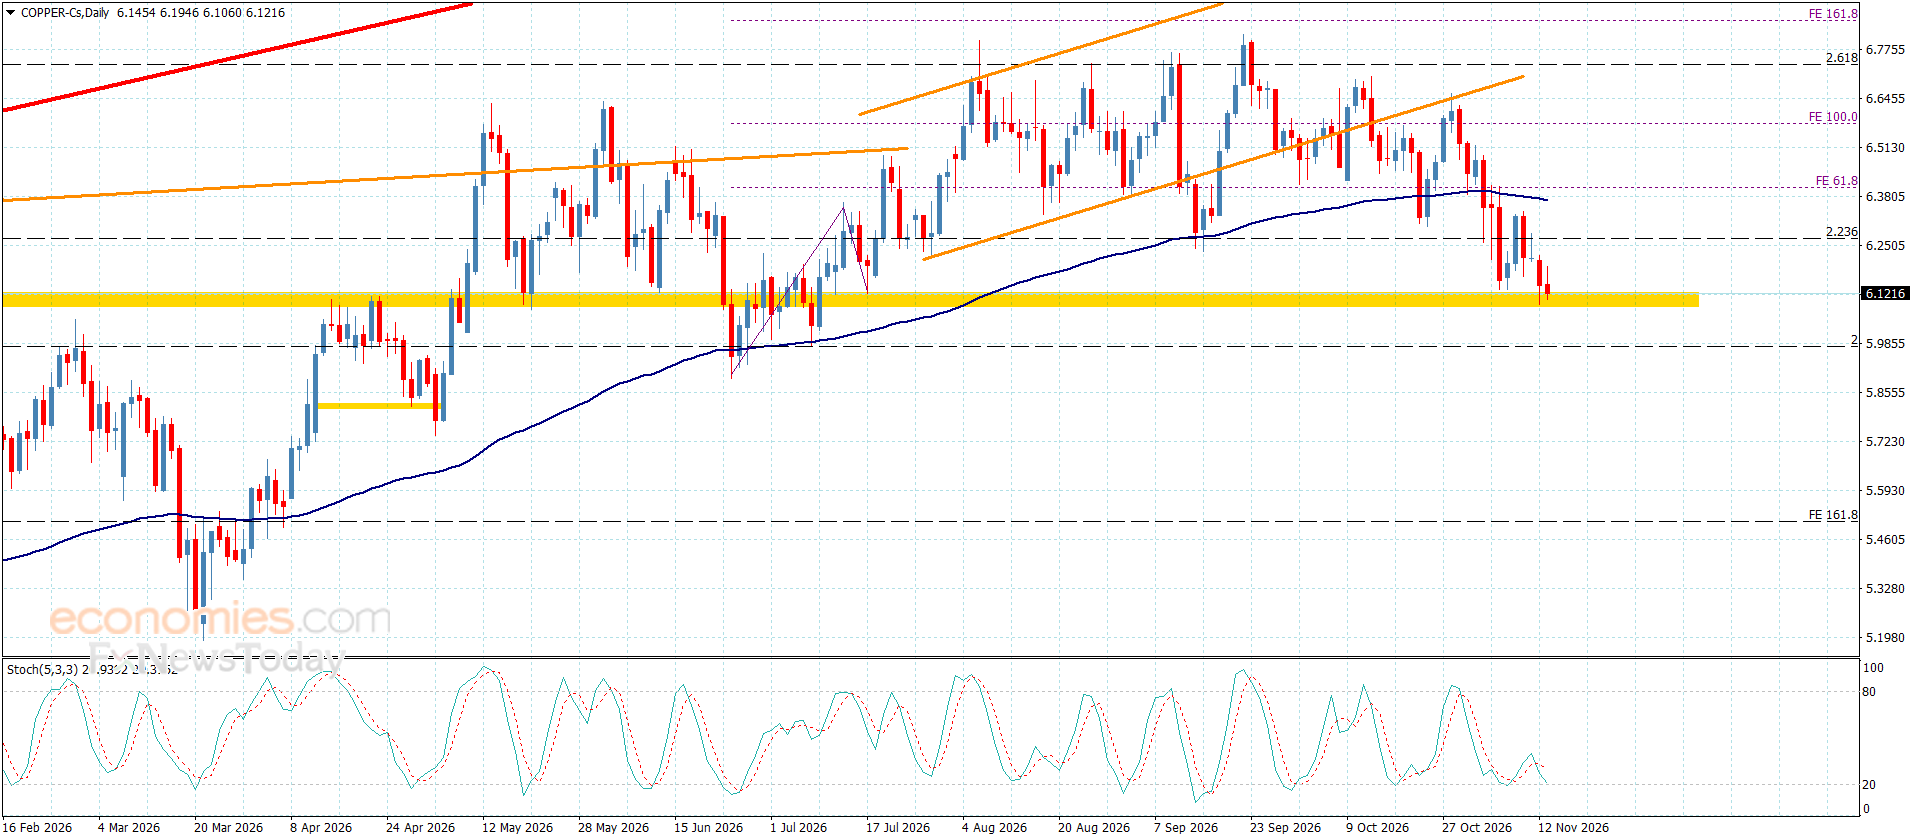
Copper prices have come under strong pressure at the $6.1000 support level, increasing the likelihood of the required break in the near term. The overall bearish outlook remains intact as long as prices hold below the $6.6100 resistance level, while $6.4200 continues to act as an additional barrier in recent trading.
The alignment of the main indicators in signaling negative momentum also leads us to expect a break below the current support, paving the way for further bearish targets starting at $5.9000 and $5.7700.
The expected trading range for today is between $5.9000 and $6.2800.
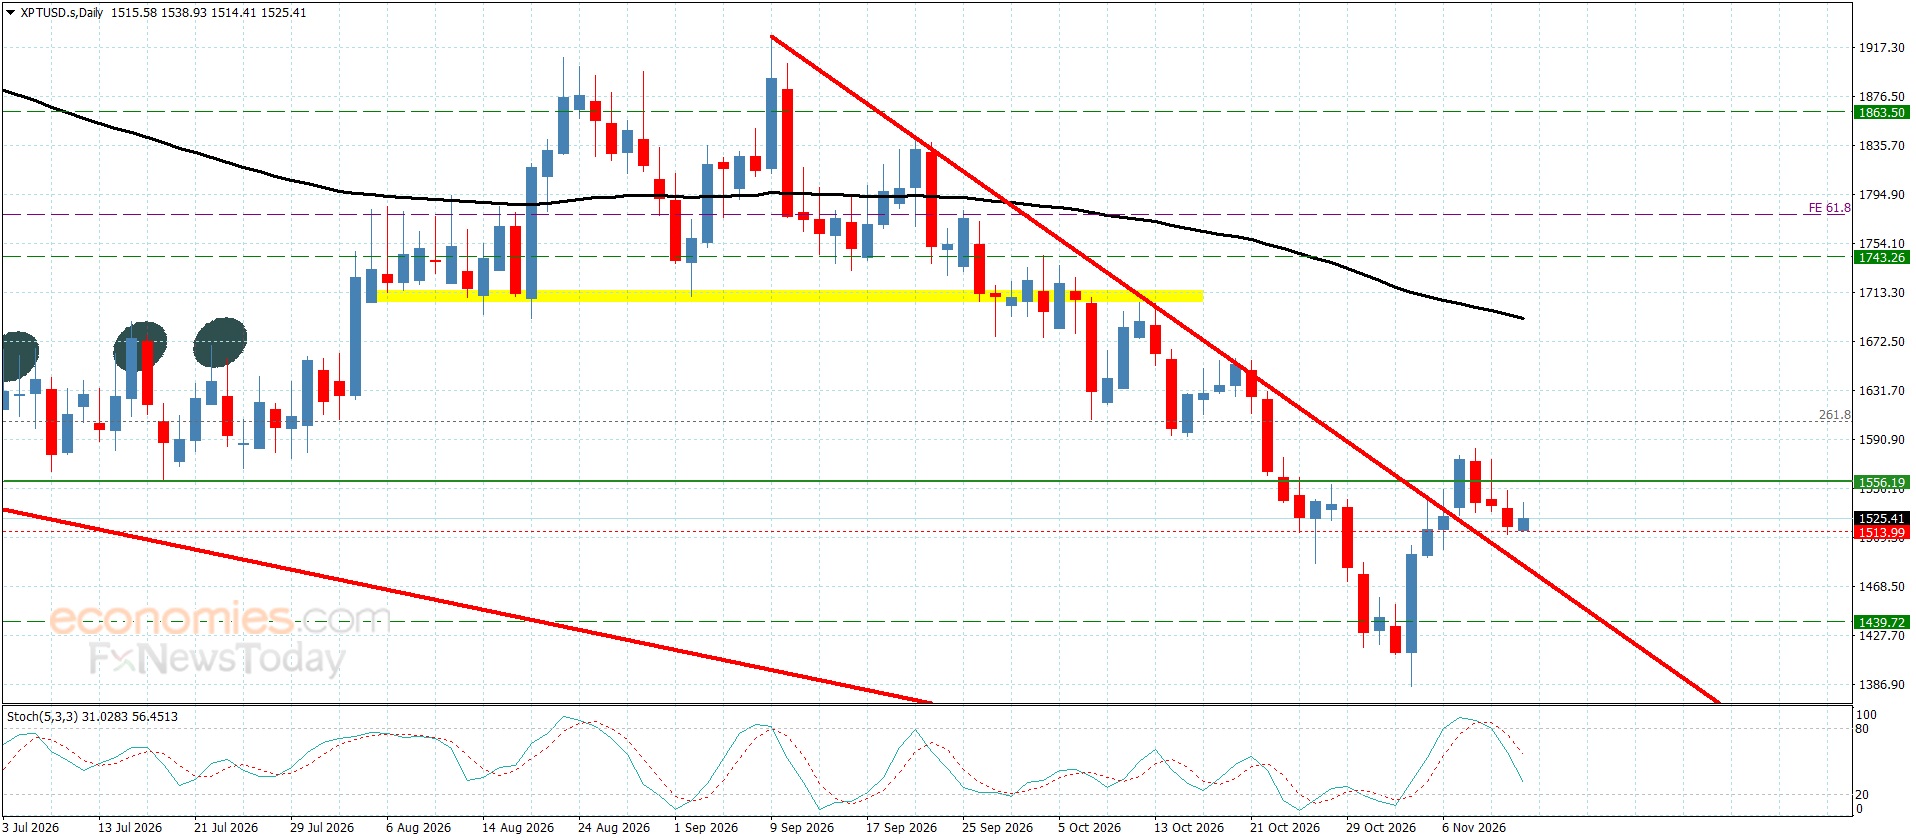
Platinum prices have come under renewed negative pressure as stochastic slipped below the 50 level, prompting the price to retest the additional support level once again, with trading currently fluctuating near $1515.00.
Holding above the $1510.00 support level could give the price an opportunity to renew its bullish attempts, gradually advancing toward $1560.00 and $1580.00. However, a break below support followed by a negative close would activate the bearish trend, exposing the price to further losses, initially targeting $1480.00 and $1440.00.
The expected trading range for today is between $1510.00 and $1580.00.
According to the latest IndexBox report on the global Flavored Syrups market, the market enters 2026 with broader demand fundamentals, more disciplined procurement behavior, and a more regionally diversified supply architecture.
The global flavored syrups market is entering a phase of sustained expansion, with the forecast period 2026-2035 expected to deliver a compound annual growth rate of 5.2%, lifting the market index to 166 by 2035 (2025=100). This growth is underpinned by the resilience of out-of-home consumption, particularly the global proliferation of coffee shop chains and specialty beverage outlets that rely on flavored syrups for product differentiation. Simultaneously, the retail channel is being reshaped by the sugar-free and reduced-sugar segment, as health-conscious consumers seek lower-calorie indulgence without compromising on taste.
The market’s product scope spans fruit, chocolate, caramel, vanilla, herbal, coffee, and premium Monin-type syrups, serving applications from beverage manufacturing and dairy to bakery, foodservice, and household use. While North America and Europe remain mature, high-value markets, Asia-Pacific is emerging as the primary volume engine, driven by urbanization, rising disposable incomes, and the rapid adoption of Western-style café culture. However, the industry faces headwinds from raw material price volatility, stringent labeling regulations, and intensifying competition from private label and low-cost alternatives.
This report provides a data-driven view of these dynamics, offering stakeholders a transparent analytical framework to navigate the market’s evolution through 2035.
The baseline scenario for the flavored syrups market projects a 5.2% CAGR from 2026 to 2035, with global consumption value expanding steadily as demand diversifies across established and emerging regions. This outlook assumes a continuation of current macroeconomic trends, including moderate global GDP growth, stable urbanization rates, and a gradual recovery in foodservice spending. The primary growth engine is the beverage industry, particularly the coffee and specialty drinks segment, where flavored syrups are essential for menu innovation and customization.
The foodservice channel is expected to recover fully from recent disruptions, with café chains and independent outlets driving volume demand for premium and sugar-free syrups. In the retail sector, the shift toward at-home coffee preparation and cocktail mixing supports household consumption, although growth is tempered by private label competition. Regionally, Asia-Pacific is forecast to outpace other regions, contributing an increasing share of global demand as café culture expands in China, India, and Southeast Asia. North America and Europe will remain significant but mature, with growth driven by product premiumization and clean-label reformulations.
The market index is projected to reach 166 by 2035, reflecting a 66% increase over the 2025 baseline. Key uncertainties include raw material supply shocks, regulatory changes affecting sugar labeling, and the pace of economic recovery in key markets.
Demand Drivers and Constraints
Primary Demand Drivers
Rapid expansion of global coffee shop culture and specialty beverage outlets, driving demand for flavored syrups in customized drinks
Rising consumer preference for sugar-free and reduced-calorie syrups, supported by health and wellness trends
Growth in the foodservice sector, including cafes, restaurants, and bars, as out-of-home consumption rebounds
Product innovation and premiumization, with new flavor profiles and clean-label formulations attracting consumers
Urbanization and rising disposable incomes in Asia-Pacific, fueling the adoption of Western-style food and beverage habits
Expansion of e-commerce and direct-to-consumer channels, improving access to specialty and artisanal syrups
Potential Growth Constraints
Volatility in raw material prices, particularly sugar and flavor compounds, impacting production costs
Stringent regulatory and labeling requirements for sugar content and artificial ingredients in key markets
Intensifying competition from private label and low-cost syrup alternatives, pressuring margins
Shifting consumer preferences toward natural sweeteners and alternative flavoring methods
Economic uncertainties and inflationary pressures affecting discretionary spending in foodservice
Demand Structure by End-Use Industry
Beverage Industry (estimated share: 32%)
The beverage industry remains the largest end-use sector for flavored syrups, accounting for approximately 32% of global demand in 2025. This segment is driven by the proliferation of coffee chains, specialty tea shops, and the ready-to-drink beverage market. Flavored syrups are used to create signature drinks, enhance seasonal menus, and offer customization options to consumers. The trend toward health-conscious consumption is reshaping the segment, with sugar-free and natural syrups gaining traction. Major beverage companies are reformulating products to reduce sugar content, creating opportunities for syrup manufacturers that offer clean-label and reduced-calorie solutions.
Through 2035, the segment is expected to grow at a moderate pace, supported by innovation in flavor profiles and the expansion of coffee culture in emerging markets. Demand-side indicators include the number of coffee shops, per capita beverage consumption, and the share of sugar-free products in portfolios. Current trend: Growing demand for flavored syrups in coffee, tea, and carbonated beverages, with a shift toward sugar-free variants.
Major trends: Proliferation of coffee shop chains and specialty beverage outlets, Rising demand for sugar-free and reduced-calorie syrups, Innovation in seasonal and limited-edition flavors, and Expansion of ready-to-drink flavored beverages.
Representative participants: Starbucks Corporation, The Coca-Cola Company, PepsiCo, Inc, Dunkin’ Brands Group, and Keurig Dr Pepper.
Dairy and Ice Cream (estimated share: 18%)
The dairy and ice cream sector represents a significant outlet for flavored syrups, particularly in the form of toppings, variegates, and flavorings for ice cream, yogurt, and flavored milk. In 2025, this segment accounted for around 18% of global flavored syrup demand. The trend is toward premium and natural ingredients, as consumers seek indulgent yet clean-label products. Manufacturers are responding with syrups that use real fruit, natural colors, and no artificial preservatives. The ice cream category, in particular, benefits from flavor innovation, with syrups used to create ripples, swirls, and coatings.
Through 2035, growth will be supported by the expansion of the dairy industry in emerging markets and the rising popularity of frozen desserts. Key demand indicators include ice cream production volumes, per capita dairy consumption, and the share of premium products in the dairy aisle. Current trend: Steady growth driven by flavored milk, ice cream toppings, and frozen desserts, with increasing demand for natural and premium syrups.
Major trends: Premiumization of ice cream and frozen desserts, Clean-label and natural ingredient formulations, Growth in flavored yogurt and dairy beverages, and Expansion of dairy consumption in emerging markets.
Representative participants: Nestlé S.A, Unilever, Danone S.A, General Mills, Inc, and Blue Bell Creameries.
Bakery and Confectionery (estimated share: 15%)
Flavored syrups play a vital role in the bakery and confectionery sector, used in glazes, fillings, icings, and as flavorings for cakes, pastries, and candies. This segment accounted for approximately 15% of global demand in 2025. The trend is toward artisanal and premium products, with consumers willing to pay more for unique flavors and high-quality ingredients. Bakery chains and confectionery manufacturers are increasingly using flavored syrups to differentiate their offerings, particularly in the dessert and chocolate categories. The rise of home baking during and after the pandemic has also supported retail demand for flavored syrups.
Through 2035, growth will be driven by innovation in flavor profiles, the expansion of bakery chains, and the increasing use of natural and organic syrups. Demand indicators include bakery production volumes, confectionery sales, and the number of artisanal bakeries. Current trend: Moderate growth, with flavored syrups used for glazes, fillings, and confectionery coatings, driven by artisanal and premium bakery trends.
Major trends: Artisanal and premium bakery products, Innovation in flavor profiles for confectionery, Home baking trend supporting retail sales, and Clean-label and natural ingredient demand.
Representative participants: Mondelez International, The Hershey Company, Barry Callebaut, Grupo Bimbo, and Flowers Foods.
Foodservice and Cafes (estimated share: 25%)
The foodservice and cafes sector is the most dynamic channel for flavored syrups, accounting for about 25% of global demand in 2025. This segment is driven by the global coffee shop boom, where flavored syrups are essential for menu customization and signature drinks. Cafes use syrups to create seasonal beverages, cater to consumer preferences for sugar-free options, and differentiate their offerings. The cocktail culture also contributes to demand, with flavored syrups used in mixology. The recovery of the foodservice sector post-pandemic has been robust, and further growth is expected through 2035, particularly in Asia-Pacific where café culture is expanding rapidly.
Key demand indicators include the number of coffee shops, foodservice revenue, and the penetration of sugar-free syrups in menus. Current trend: Strong growth, driven by the expansion of café chains, independent coffee shops, and the use of flavored syrups in customized beverages and cocktails.
Major trends: Global coffee shop expansion, especially in Asia-Pacific, Customization and personalization of beverages, Growth in cocktail and mixology culture, and Sugar-free and natural syrup options on menus.
Representative participants: Starbucks Corporation, Dunkin’ Brands Group, Costa Coffee, Tim Hortons, and Luckin Coffee.
Household Consumption (estimated share: 10%)
Household consumption of flavored syrups, though smaller in volume compared to foodservice, is a growing segment, representing around 10% of global demand in 2025. This segment is driven by the rise of at-home coffee preparation, home baking, and cocktail making, trends that accelerated during the pandemic and have persisted. Consumers are increasingly purchasing flavored syrups from retail channels, including supermarkets, specialty stores, and e-commerce, to recreate café-style beverages at home. The trend is toward premium and sugar-free options, with brands offering barista-style syrups for home use.
Through 2035, growth will be supported by the expansion of e-commerce, product innovation, and the increasing popularity of home entertaining. Demand indicators include retail sales of coffee syrups, e-commerce penetration, and the number of households with coffee machines. Current trend: Steady growth, supported by at-home coffee preparation, home baking, and cocktail making, with a shift toward premium and sugar-free retail products.
Major trends: At-home coffee and cocktail preparation, E-commerce growth for specialty syrups, Premium and sugar-free retail products, and Home baking and entertaining trends.
Interactive table based on the Store Companies dataset for this report.
#
Company
Headquarters
Focus
Scale
Note
1
Monin
Bourg-la-Reine, France
Premium cocktail & coffee syrups
Global
Market leader in premium segment
2
Tate & Lyle
London, UK
Sweeteners & food ingredients
Global
Major industrial supplier
3
Kerry Group
Tralee, Ireland
Taste & nutrition ingredients
Global
Broad flavor solutions portfolio
4
The Hershey Company
Hershey, Pennsylvania, USA
Chocolate & syrup brands
Global
Owner of Hershey’s syrup brand
5
Torani
San Leandro, California, USA
Coffee & beverage syrups
Major
Key player in foodservice
6
Nestlé
Vevey, Switzerland
Food & beverages
Global
Owns Nesquik syrup brand
7
1883 Maison Routin
Chabeuil, France
Premium gourmet syrups
International
High-end flavor specialist
8
DaVinci Gourmet
Seattle, Washington, USA
Coffee & beverage syrups
Major
Significant foodservice presence
9
The J.M. Smucker Company
Orrville, Ohio, USA
Food & beverage brands
Major
Owner of Smucker’s breakfast syrups
10
Giffard
Avrillé, France
Liqueurs & fruit syrups
International
Premium French syrup maker
11
Amoretti
Oxnard, California, USA
Gourmet syrups & ingredients
International
Craft & culinary focus
12
Wild Flavors (ADM)
Erlanger, Kentucky, USA
Flavor systems & extracts
Global
Part of ADM
13
Fuerst Day Lawson
London, UK
Food ingredients & syrups
International
Importer and distributor
14
R. Torre & Company
San Francisco, California, USA
Flavor syrups & sauces
National
Known for Orgeat & cocktail syrups
15
Sensient Technologies
Milwaukee, Wisconsin, USA
Colors, flavors & fragrances
Global
Industrial flavor supplier
16
B&G Foods
Parsippany, New Jersey, USA
Packaged & branded foods
Major
Owner of Maple Grove Farms
17
Toschi Vignola
Vignola, Italy
Fruit syrups & ingredients
International
Italian fruit syrup specialist
18
Mantova Manufacturing
Mantova, Italy
Fruit syrups & purees
International
European industrial supplier
19
Fabbri 1905
Bologna, Italy
Syrups, pastes & toppings
International
Known for fruit syrups
20
Sonoma Syrup Co.
Sonoma, California, USA
Craft cocktail syrups
National
Premium craft segment
Regional Dynamics
Asia-Pacific (estimated share: 30%)
Asia-Pacific is the fastest-growing region, driven by urbanization, rising disposable incomes, and the rapid expansion of coffee shop chains in China, India, and Southeast Asia. Demand for flavored syrups is supported by the adoption of Western-style beverages and the growth of the foodservice sector. Direction: Growing.
North America (estimated share: 28%)
North America remains the largest market for flavored syrups, supported by a well-established coffee culture and high per capita consumption. Growth is driven by premiumization, sugar-free formulations, and the expansion of specialty beverage outlets, though the market is relatively mature. Direction: Mature but growing.
Europe (estimated share: 22%)
Europe is a mature market with a strong café culture and demand for premium and natural syrups. Growth is supported by product innovation, clean-label trends, and the expansion of foodservice chains, particularly in Western and Southern Europe. Direction: Stable growth.
Latin America (estimated share: 12%)
Latin America is experiencing moderate growth, driven by urbanization and the expansion of coffee shops and foodservice outlets. Brazil and Mexico are key markets, with increasing demand for flavored syrups in beverages and dairy products. Direction: Moderate growth.
Middle East & Africa (estimated share: 8%)
The Middle East & Africa region is an emerging market for flavored syrups, with growth supported by urbanization, a young population, and the expansion of café culture in Gulf countries and South Africa. Demand is expected to accelerate through 2035. Direction: Emerging.
Market Outlook (2026-2035)
In the baseline scenario, IndexBox estimates a 5.2% compound annual growth rate for the global flavored syrups market over 2026-2035, bringing the market index to roughly 166 by 2035 (2025=100).
Note: indexed curves are used to compare medium-term scenario trajectories when full absolute volumes are not publicly disclosed.
For full methodological details and benchmark tables, see the latest IndexBox Flavored Syrups market report.
The prices for imports have increased to 24.8% from the previous year. The cost of imports may influence inflation as businesses pass costs to consumers. These conditions suggest that BoJ may increase interest rates in December.
Japan will release the GDP data on 16 November and inflation data for October on 20 November. The market expects annualized growth of 0.3% which is down from 1.4% in Q2. The expectations for core inflation are 2.3% which is up from 2.1% in September. These expectations also support the rate hike in December. If the GDP data suggest slowdown and inflation is softer, it would give the BOJ room to wait. If inflation is hotter than expected, it will increase the expectation of rate hikes in 2027.
Inflation in the US is also high which is keeping pressure on the Fed to raise interest rates. The chart below shows that consumer prices increased by 0.35% in October while core prices increased by 0.3%.
According to the latest IndexBox report on the global Caffeine Free Cold Brew Coffee market, the market enters 2026 with broader demand fundamentals, more disciplined procurement behavior, and a more regionally diversified supply architecture.
The global caffeine free cold brew coffee market represents a premium, benefit-led niche within ready-to-drink (RTD) coffee and functional beverages, defined by the intersection of cold brew’s smooth, low-acidity sensory appeal and the deliberate avoidance of caffeine’s physiological effects. Unlike traditional coffee demand, which is anchored in energy and ritual, this category is propelled by health and wellness trends, particularly ingredient consciousness, sleep hygiene, and stimulant management.
The market exhibits a two-tier structure: a premium, brand-driven segment emphasizing organic, clean-label claims and artisanal positioning, and a value-oriented, private-label segment focused on accessibility. Route-to-market is bifurcated, with premium brands relying on natural/specialty channels and DTC, while mainstream penetration depends on chilled and ambient shelf space in mass grocery, convenience, and club. Supply chain complexity is above average, requiring dedicated decaffeination and cold-brewing infrastructure. Geographic development is uneven, concentrated in advanced, wellness-oriented economies with established cold brew cultures.
Long-term expansion hinges on moving beyond a caffeine-free avoidance claim to a proactive functional relaxation or evening occasion platform, alongside format innovation in concentrates and home systems. The forecast period 2026-2035 anticipates continued premiumization and channel diversification as consumer demand for functional, stimulant-free beverages accelerates.
The baseline scenario for the caffeine free cold brew coffee market through 2035 envisions steady expansion, underpinned by sustained consumer interest in health and wellness, particularly sleep hygiene and stimulant management. The market is expected to grow at a CAGR of 7.2% from 2026 to 2035, reaching a market index of 185 (2025=100). This growth is supported by the category’s premium positioning, which insulates it somewhat from broad economic downturns, though price sensitivity remains a factor in value-tier segments. The two-tier structure will persist, with premium brands driving innovation and margin, while private label expands access and volume.
Route-to-market evolution will see increased penetration in mainstream retail as chilled distribution improves, alongside growth in e-commerce and DTC channels. Supply chain investments in dedicated decaffeination and cold-brewing capacity will lower barriers for new entrants and support scale. Geographically, North America and Europe will remain the largest markets, but Asia-Pacific is expected to witness the fastest growth as cold brew culture spreads and wellness trends gain traction. Key risks include intense competition from other functional beverages, regulatory changes affecting health claims, and volatility in coffee bean prices.
Overall, the outlook is positive, with the category poised to benefit from shifting consumer preferences toward stimulant-free, relaxation-oriented beverages.
Demand Drivers and Constraints
Primary Demand Drivers
Rising consumer focus on sleep hygiene and stimulant avoidance, driving demand for evening-appropriate coffee alternatives.
Health and wellness trends emphasizing ingredient consciousness and clean-label claims, supporting premium price points.
Expansion of cold brew culture and consumer familiarity with cold coffee formats, lowering adoption barriers.
Growth in functional beverage platforms, with caffeine free cold brew positioned as a relaxation and wellness drink.
Improved chilled distribution and e-commerce capabilities, enhancing product availability and trial.
Innovation in decaffeination methods (e.g., Swiss Water Process) and format diversification (concentrates, pods).
Potential Growth Constraints
High price premium relative to regular coffee and other beverages, limiting mass-market appeal in price-sensitive regions.
Supply chain complexity and higher production costs due to dedicated decaffeination and cold-brewing infrastructure.
Competition from other functional beverages (e.g., herbal teas, adaptogen drinks) for the same need states.
Low consumer awareness and underdeveloped chilled distribution in many emerging markets.
Potential regulatory scrutiny over health claims and labeling, which could impact marketing and positioning.
The RTD segment dominates the caffeine free cold brew coffee market, accounting for the largest share of volume and value. Demand is fueled by consumers seeking convenient, on-the-go options that align with health and wellness goals, particularly sleep hygiene and stimulant avoidance. The segment benefits from the broader RTD coffee boom, but differentiates through its caffeine-free positioning, appealing to evening and relaxation occasions. Key demand-side indicators include the expansion of chilled distribution in retail, the rise of e-commerce and DTC channels, and increasing shelf space in natural and specialty stores.
Through 2035, innovation in packaging (e.g., single-serve cans, larger multi-serve bottles) and clean-label claims will drive premiumization. However, competition from other functional RTD beverages and private-label offerings will pressure margins. The segment’s growth is also supported by the entry of major CPG players, which brings scale and marketing investment, further legitimizing the category. Current trend: Growing at a robust pace, driven by convenience and premiumization..
Major trends: Premiumization with organic and clean-label claims, Expansion of chilled distribution and e-commerce, Innovation in packaging formats (cans, multi-serve), Entry of major CPG companies through acquisitions or launches, and Growing demand for functional relaxation beverages.
Representative participants: Starbucks Corporation, Nestlé S.A, The Coca-Cola Company, PepsiCo, Inc, and Keurig Dr Pepper Inc.
Concentrates and Home Brewing (estimated share: 25%)
The concentrates and home brewing segment includes liquid concentrates, powders, and pods for home cold brew systems. Demand is driven by consumers who prefer to prepare caffeine free cold brew at home for cost savings, customization, and sustainability reasons. This segment appeals to hobbyists and health-conscious consumers who value control over ingredients and strength. Key demand-side indicators include the penetration of home cold brew systems, the growth of e-commerce for specialty concentrates, and the expansion of subscription models. Through 2035, innovation in pod formats compatible with popular home brewing machines and the introduction of shelf-stable concentrates will drive growth.
However, the segment faces competition from RTD options and traditional home brewing methods. The trend toward premiumization is also evident, with organic and single-origin concentrates gaining traction. Major companies are investing in this space through partnerships and product launches, recognizing the potential for recurring revenue and brand loyalty. Current trend: Steady growth, supported by home consumption and customization trends..
Major trends: Growth of home cold brew systems and pod compatibility, Subscription and DTC models for concentrates, Demand for organic and single-origin products, Sustainability-driven packaging innovations, and Partnerships with home appliance brands.
Representative participants: JAB Holding Company, Lavazza Professional, Illycaffè S.p.A, High Brew Coffee, and Chameleon Cold-Brew.
Foodservice and Hospitality (estimated share: 15%)
The foodservice and hospitality segment encompasses cafes, restaurants, hotels, and other venues that serve caffeine free cold brew coffee on-premise or for takeaway. Demand is driven by consumers seeking evening-friendly coffee options and the general trend of cafes expanding their beverage menus to cater to diverse dietary preferences. Key demand-side indicators include the number of specialty coffee shops, menu innovation, and the willingness of operators to stock niche products. Through 2035, growth will be supported by the rise of experiential coffee culture and the integration of functional beverages into foodservice.
However, the segment faces challenges such as limited shelf space, staff training needs, and the perception of caffeine free cold brew as a niche product. Operators are increasingly partnering with premium brands to offer differentiated options, and the segment is expected to benefit from the overall premiumization of coffee shop menus. The trend toward health and wellness also encourages foodservice operators to highlight caffeine-free and low-acidity attributes. Current trend: Moderate growth, as cafes and restaurants expand caffeine-free options..
Major trends: Menu diversification in specialty coffee shops, Partnerships with premium caffeine free cold brew brands, Growing demand for evening-friendly coffee options, Integration of functional beverages into foodservice, and Focus on low-acidity and clean-label claims.
Representative participants: Starbucks Corporation, La Colombe Coffee Roasters, Stumptown Coffee Roasters, Illycaffè S.p.A, and Lavazza Professional.
The retail segment includes grocery stores, convenience stores, mass merchandisers, and club stores that sell packaged caffeine free cold brew coffee for at-home consumption. Demand is driven by increasing availability and consumer awareness, as well as the expansion of private-label offerings that make the category more accessible. Key demand-side indicators include the number of stock-keeping units (SKUs), shelf space allocation, and promotional activity. Through 2035, growth will be supported by the entry of mainstream CPG brands and the expansion of chilled distribution networks. However, the segment faces intense competition for shelf space and price pressure from private label.
Retailers are increasingly leveraging caffeine free cold brew as a premium offering to differentiate their assortments, and the category benefits from the overall growth of cold brew in retail. The trend toward health and wellness also drives demand for clean-label and organic options in retail channels. Current trend: Expanding shelf presence, driven by private label and mainstream adoption..
Major trends: Expansion of private-label offerings, Increased shelf space in chilled sections, Promotional activity and price competition, Growth of club and mass merchandiser channels, and Rising consumer awareness and trial.
Representative participants: Nestlé S.A, The Coca-Cola Company, PepsiCo, Inc, Keurig Dr Pepper Inc, and JAB Holding Company.
Online and DTC (estimated share: 5%)
The online and direct-to-consumer (DTC) segment includes e-commerce platforms, brand websites, and subscription services that sell caffeine free cold brew coffee directly to consumers. Demand is driven by convenience, the ability to access niche products, and the growing popularity of subscription models for regular deliveries. Key demand-side indicators include online penetration of beverage sales, subscription growth rates, and digital marketing effectiveness. Through 2035, this segment is expected to grow rapidly, supported by improved logistics for chilled and ambient products, and the expansion of DTC brands that cultivate loyal followings.
However, challenges include high customer acquisition costs, complex cold-chain logistics, and competition from established retail channels. Brands are increasingly using online channels for product launches and consumer education, leveraging data to personalize offerings. The segment is also benefiting from the overall shift toward e-commerce in consumer goods, particularly among younger, digitally native consumers. Current trend: Fastest-growing segment, albeit from a small base, driven by subscription and convenience..
Major trends: Growth of subscription-based DTC models, Improved cold-chain logistics for online delivery, Personalization and data-driven marketing, Expansion of online marketplaces for specialty beverages, and Rising consumer comfort with purchasing beverages online.
Representative participants: High Brew Coffee, Chameleon Cold-Brew, Stumptown Coffee Roasters, La Colombe Coffee Roasters, and Starbucks Corporation.
Key Market Participants
Interactive table based on the Store Companies dataset for this report.
#
Company
Headquarters
Focus
Scale
Note
1
Starbucks Corporation
Seattle, Washington, USA
Retail, CPG, ready-to-drink
Global
Major brand with decaf cold brew options
2
Nestlé S.A.
Vevey, Switzerland
CPG, brands (Nescafé, Starbucks license)
Global
Portfolio includes decaf/processed caffeine-free coffee
3
The J.M. Smucker Company
Orrville, Ohio, USA
CPG, coffee brands
National (US)
Owns Café Bustelo, Folgers with decaf offerings
4
Keurig Dr Pepper Inc.
Burlington, Massachusetts, USA
Beverage manufacturing & distribution
National (US)
Produces and distributes decaf cold brew brands
5
Chameleon Cold-Brew
Austin, Texas, USA
Cold brew concentrate & RTD
National (US)
Offers organic decaf cold brew concentrate
6
La Colombe Coffee Roasters
Philadelphia, Pennsylvania, USA
Roaster, café chain, RTD
National (US)
Produces decaf cold brew cans and draft
7
High Brew Coffee
Austin, Texas, USA
RTD cold brew coffee
National (US)
Has a double espresso decaf cold brew product
8
Wandering Bear Coffee Co.
New York, New York, USA
Cold brew on tap, boxed
National (US)
Offers straight-up decaf cold brew
9
Califia Farms
Los Angeles, California, USA
Plant-based beverages & cold brew
National (US)
Produces dairy-free decaf cold brew options
10
Slingshot Coffee Co.
Raleigh, North Carolina, USA
Cold brew concentrate
Regional (US)
Offers a decaf cold brew concentrate
11
Mount Hagen
Kirchheim, Germany
Instant & freeze-dried coffee
Global
Offers organic decaf instant, used for cold brew
12
Clevr Blends
Santa Barbara, California, USA
Superfood latte mixes
National (US)
Offers caffeine-free coffee-alternative cold brew
13
Super Coffee
New York, New York, USA
Functional RTD coffee
National (US)
Includes decaf options in product line
14
Bizzy Coffee
Minneapolis, Minnesota, USA
Cold brew concentrate
National (US)
Offers organic decaf cold brew concentrate
15
Caveman Coffee Co.
Las Vegas, Nevada, USA
Coffee roaster, RTD
National (US)
Produces a decaf cold brew product
16
Laird Superfood
Sisters, Oregon, USA
Functional creamers & beverages
National (US)
Offers caffeine-free coffee alternatives
17
Teeccino
Santa Barbara, California, USA
Herbal coffee alternatives
National (US)
Caffeine-free brews mimicking coffee
18
RISE Brewing Co.
New York, New York, USA
Oat milk-based RTD cold brew
National (US)
Has introduced decaf oat milk cold brew
19
Colectivo Coffee Roasters
Milwaukee, Wisconsin, USA
Roaster, café chain
Regional (US)
Produces decaf cold brew for retail
Regional Dynamics
North America (estimated share: 40%)
North America dominates the caffeine free cold brew coffee market, driven by strong health and wellness trends, high disposable income, and a mature cold brew culture. The U.S. is the largest contributor, with premium brands and private label expanding shelf space. Growth will be supported by innovation in functional claims and channel diversification, though market maturity may temper the pace. Direction: Leading market, with high consumer awareness and established cold brew culture..
Europe (estimated share: 25%)
Europe represents a significant market, with growth concentrated in Western and Northern countries where wellness trends and specialty coffee culture are strong. The UK, Germany, and Scandinavia are key markets. Challenges include fragmented distribution and competition from traditional coffee. However, rising interest in functional beverages and clean-label products supports the outlook. Direction: Steady growth, with increasing adoption in Western and Northern Europe..
Asia-Pacific (estimated share: 20%)
Asia-Pacific is expected to be the fastest-growing region, albeit from a smaller base. Urbanization, rising disposable incomes, and the spread of coffee culture in countries like China, Japan, and South Korea drive demand. However, low awareness and underdeveloped chilled distribution remain barriers. The region offers significant white-space opportunities for premium and functional products. Direction: Fastest-growing region, driven by urbanization and changing consumer preferences..
Latin America (estimated share: 10%)
Latin America shows promise, particularly in Brazil and Mexico, where coffee consumption is high. However, economic volatility and price sensitivity limit the adoption of premium caffeine free cold brew. Growth will depend on affordability and the development of local supply chains. The region’s strong coffee tradition may also pose a challenge to the category’s positioning. Direction: Emerging market with potential, but constrained by economic volatility..
Middle East & Africa (estimated share: 5%)
The Middle East & Africa region is a nascent market for caffeine free cold brew coffee, with demand concentrated in affluent urban centers in the UAE, Saudi Arabia, and South Africa. Growth is constrained by low awareness, limited distribution, and cultural preferences for traditional beverages. However, increasing health consciousness and the expansion of modern retail could drive future demand. Direction: Nascent market, with growth potential in affluent urban centers..
Market Outlook (2026-2035)
In the baseline scenario, IndexBox estimates a 7.2% compound annual growth rate for the global caffeine free cold brew coffee market over 2026-2035, bringing the market index to roughly 185 by 2035 (2025=100).
Note: indexed curves are used to compare medium-term scenario trajectories when full absolute volumes are not publicly disclosed.
According to the latest IndexBox report on the global Coffee Packaging market, the market enters 2026 with broader demand fundamentals, more disciplined procurement behavior, and a more regionally diversified supply architecture.
The global coffee packaging market is a critical and dynamic segment within the broader food and beverage supply chain, directly influenced by evolving consumption patterns, stringent regulatory requirements, and shifting sustainability imperatives. As of the 2026 analysis period, the market is characterized by a complex interplay between the robust demand for roasted coffee, which reached 10.5 million tons, and the innovative packaging solutions required to preserve product quality, ensure safety, and communicate brand value across diverse retail and distribution channels.
The transition towards more sophisticated, environmentally responsible packaging formats is no longer a niche trend but a central strategic consideration for producers, converters, and brand owners alike, shaping investment and R&D priorities across the industry. This report provides a comprehensive, data-driven assessment of the market’s structure, from raw material supply and production capacities to end-use demand and international trade flows. It identifies the key macroeconomic, consumer, and regulatory forces that will dictate market evolution through the forecast horizon to 2035.
The analysis underscores that competitive advantage will increasingly hinge on a company’s ability to navigate the dual challenges of performance and sustainability, adapt to regional logistical nuances, and manage cost volatility within the supply chain. The insights contained herein are designed to equip senior executives and strategists with the foundational intelligence necessary for informed decision-making in a market where packaging is integral to product integrity and commercial success.
The baseline scenario for the world coffee packaging market through 2035 anticipates steady expansion, supported by the fundamental need to protect and preserve roasted coffee, which reached 10.5 million tons in the 2026 analysis period. Demand is projected to accelerate as coffee consumption grows in emerging markets and premiumization drives higher-value packaging formats. The market index is forecast to reach 142 by 2035 (2025=100), equivalent to a CAGR of 3.6% over the 2026-2035 period. Growth will be underpinned by the rising share of single-serve capsules and pods, which require specialized barrier packaging, as well as the expansion of specialty and gourmet coffee retail.
Sustainability pressures will reshape material choices, with recyclable mono-material pouches and paper-based formats gaining share, although cost and performance trade-offs will slow full substitution. Regionally, Asia-Pacific is expected to contribute the largest incremental demand, while Europe and North America remain key for premium and sustainable packaging innovation. Supply-side factors, including resin price volatility and aluminum availability, pose risks, but converters are investing in capacity and technology to meet barrier and sustainability requirements.
Overall, the outlook is positive, with packaging increasingly viewed as a strategic enabler of brand differentiation and product freshness.
Demand Drivers and Constraints
Primary Demand Drivers
Rising global coffee consumption and roasted coffee volumes, which reached 10.5 million tons, directly increase the need for primary packaging to preserve freshness and enable distribution.
Proliferation of single-serve coffee capsules and pods, which require specialized barrier packaging and drive demand for composite and plastic formats.
Premiumization and specialty coffee growth, as brand owners seek high-barrier, aesthetically appealing packaging to communicate quality and origin.
Expansion of e-commerce and food service channels, necessitating packaging that ensures product integrity during shipping and convenient preparation.
Sustainability mandates and consumer preference for recyclable, compostable, or paper-based packaging, prompting converters to innovate and brand owners to adopt eco-friendly formats.
Urbanization and busy lifestyles in emerging markets, boosting demand for convenient single-serve and ready-to-drink coffee packaging.
Potential Growth Constraints
Volatility in raw material prices, particularly resins and aluminum, which pressures margins and may delay packaging conversions.
Technical challenges and higher costs associated with developing recyclable or compostable packaging that matches the barrier performance of conventional multi-material structures.
Fragmented regulatory landscape for packaging waste and recycling across regions, creating compliance complexity and uncertainty for global brand owners.
Competition from alternative packaging formats and bulk distribution models that reduce packaging intensity per unit of coffee consumed.
Demand Structure by End-Use Industry
Whole Bean Coffee (estimated share: 28%)
Whole bean coffee packaging is experiencing robust demand as consumers increasingly prefer freshly roasted beans for home brewing. The segment is characterized by the widespread use of one-way degassing valve bags and stand-up pouches that allow carbon dioxide to escape while preventing oxygen ingress, thereby preserving aroma and flavor. Through 2035, the shift toward specialty and single-origin coffees will support higher-value packaging with premium finishes, resealable features, and smaller pack sizes for trial and gifting. Demand-side indicators include the number of specialty coffee shops, home brewing equipment sales, and e-commerce penetration for fresh coffee.
Sustainability will be a key differentiator, with brands adopting recyclable mono-material valve bags and paper-based solutions. The segment is expected to grow in line with overall coffee consumption, but with a rising share of value-added packaging. Current trend: Growing demand for fresh whole bean coffee, especially in specialty and premium segments, drives adoption of valve bags and high-barrier pouches..
Major trends: Increasing use of recyclable mono-material valve bags, Growth of small-format and single-origin packs, Integration of QR codes for traceability and brewing guidance, and Premiumization with matte finishes and tactile effects.
Representative participants: Amcor plc, Mondi Group, Goglio S.p.A, Constantia Flexibles, and Sealed Air Corporation.
Ground Coffee (estimated share: 22%)
Ground coffee packaging remains a significant segment, driven by its widespread use in households and food service establishments. The primary packaging formats include vacuum-sealed bricks, which offer excellent barrier properties and extended shelf life, and resealable pouches for convenience. As consumers seek freshness and convenience, there is a gradual shift toward smaller pack sizes and single-serve sachets, particularly in emerging markets. Through 2035, the segment will be influenced by the growth of private label and value-tier products, which are cost-sensitive and often use standard flexible packaging. Demand-side indicators include retail sales of ground coffee, food service outlet growth, and private label penetration.
Sustainability pressures will encourage the adoption of paper-based and recyclable flexible packaging, although cost remains a barrier in price-sensitive markets. Current trend: Steady demand for ground coffee in retail and food service, with a shift toward vacuum-sealed bricks and resealable pouches for convenience..
Major trends: Adoption of recyclable flexible packaging in developed markets, Growth of single-serve sachets in emerging economies, Increased use of high-barrier metallized films for extended shelf life, and Rise of private label ground coffee packaging.
Representative participants: Amcor plc, Berry Global Group, Sonoco Products Company, Huhtamaki Oyj, and Novolex.
Instant Coffee (estimated share: 18%)
Instant coffee packaging is a mature but resilient segment, particularly in emerging markets where affordability and convenience drive consumption. The segment is dominated by glass jars and flexible refill pouches, with a growing emphasis on lightweighting and cost reduction. Through 2035, demand will be supported by urbanization and busy lifestyles, especially in Asia-Pacific and Latin America. However, the segment faces competition from single-serve and ready-to-drink formats. Demand-side indicators include instant coffee retail volumes, household penetration, and income levels. Sustainability trends are prompting brands to offer refill pouches and explore recyclable packaging, but glass remains preferred for premium instant coffee.
The segment is expected to grow modestly, with flexible packaging gaining share due to cost and convenience advantages. Current trend: Instant coffee packaging demand is supported by affordability and convenience, with glass jars and flexible refill pouches dominating..
Major trends: Shift from glass jars to flexible refill pouches, Lightweighting of glass containers, Growth of premium instant coffee in recyclable packaging, and Expansion of instant coffee sachets in emerging markets.
Coffee pods and capsules represent the fastest-growing end-use segment for coffee packaging, fueled by consumer demand for convenience, consistency, and premium coffee experiences. Packaging for this segment includes plastic and aluminum capsules, as well as compostable and recyclable alternatives. The segment is characterized by high barrier requirements to protect coffee from oxygen and moisture, and by significant investment in proprietary systems. Through 2035, growth will be driven by the expansion of single-serve coffee machines in households and offices, particularly in North America and Europe, and by rising adoption in Asia-Pacific.
Demand-side indicators include machine sales, capsule consumption per capita, and the development of sustainable capsule solutions. The segment faces sustainability challenges, with brands increasingly offering recyclable or compostable capsules to address environmental concerns. Current trend: Rapid growth in single-serve pods and capsules, driven by convenience and premiumization, requiring specialized barrier packaging..
Major trends: Development of recyclable and compostable capsules, Growth of private label capsules compatible with major systems, Premiumization with specialty and single-origin capsules, and Expansion of capsule offerings in emerging markets.
Representative participants: Amcor plc, Sealed Air Corporation, Constantia Flexibles, Goglio S.p.A, and Berry Global Group.
Ready-to-Drink Coffee (estimated share: 12%)
Ready-to-drink (RTD) coffee packaging is a dynamic segment driven by changing consumer lifestyles and the growing popularity of cold brew and iced coffee. Packaging formats include aluminum cans, PET bottles, and cartons, with a focus on convenience, portability, and shelf appeal. Through 2035, the segment is expected to grow rapidly, particularly in North America and Asia-Pacific, as consumers seek convenient caffeine options. Demand-side indicators include RTD coffee sales, new product launches, and consumption occasions. Sustainability is a key trend, with brands adopting recyclable aluminum cans and PET bottles, and exploring paper-based cartons.
The segment requires packaging that maintains product stability and taste over shelf life, often involving aseptic processing and barrier materials. Current trend: Rising demand for ready-to-drink coffee in cans, bottles, and cartons, supported by convenience and on-the-go consumption..
Major trends: Growth of aluminum cans for premium RTD coffee, Adoption of recyclable PET bottles, Expansion of cold brew and nitro coffee packaging, and Use of aseptic cartons for shelf-stable RTD coffee.
Representative participants: Ball Corporation, Crown Holdings, Amcor plc, Tetra Pak, and SIG Combibloc.
Key Market Participants
Interactive table based on the Store Companies dataset for this report.
#
Company
Headquarters
Focus
Scale
Note
1
Amcor plc
Zurich, Switzerland
Flexible & rigid packaging solutions
Global
Leading supplier of coffee bags & pouches
2
Mondi Group
Vienna, Austria
Sustainable paper & flexible packaging
Global
Major in barrier papers and pouches
3
Sonoco Products Company
Hartsville, SC, USA
Rigid paperboard & flexible packaging
Global
Key in composite cans and sustainable options
4
ProAmpac
Cincinnati, OH, USA
Flexible packaging & pouches
Global
Innovative stand-up pouch solutions
5
WestRock Company
Atlanta, GA, USA
Paperboard, folding cartons
Global
Major supplier of boxed coffee packaging
6
Sealed Air Corporation
Charlotte, NC, USA
Cryovac barrier packaging
Global
Specializes in fresh coffee preservation
7
Huhtamaki
Espoo, Finland
Molded fiber & flexible packaging
Global
Known for compostable coffee cups/lids
8
Goglio S.p.A.
Milan, Italy
Coffee pouches & valve technology
Global
Specialist in premium coffee packaging
9
Winpak Ltd.
Winnipeg, Canada
High-barrier packaging films & lidding
Global
Focus on extended shelf-life solutions
10
Smurfit Kappa
Dublin, Ireland
Paper-based packaging
Global
Major in corrugated and bag-in-box
11
DS Smith
London, UK
Sustainable corrugated & cartons
Global
Strong in retail-ready coffee packaging
12
Constantia Flexibles
Vienna, Austria
Flexible laminates & pouches
Global
Specializes in high-barrier laminates
13
Glenroy, Inc.
Menomonee Falls, WI, USA
Flexible stand-up pouches
Regional
Key player in US custom pouch market
14
PAC Machinery
Union City, CA, USA
Packaging equipment & bags
Global
Supplies bagging machines and rollstock
15
Bemis (now part of Amcor)
Neenah, WI, USA
Flexible packaging films
Global
Legacy player in coffee film structures
16
Coveris Holdings S.A.
Vienna, Austria
Flexible films & pouches
Global
Provides printed barrier solutions
17
TricorBraun
St. Louis, MO, USA
Rigid containers & bottles
Global
Distributor of jars, tins for coffee
18
Berry Global Inc.
Evansville, IN, USA
Flexible films & nonwovens
Global
Produces films for bag liners
19
Körber AG
Hamburg, Germany
Packaging machinery & software
Global
Key supplier of filling/sealing lines
20
PBFY Flexible Packaging
Salt Lake City, UT, USA
Custom flexible pouches
Regional
Growing player for specialty coffee
21
Novolex
Hartsville, SC, USA
Bags, pouches, & liners
North America
Broad portfolio of bag solutions
22
Uflex Ltd
Noida, India
Flexible packaging films
Global
Major emerging market supplier
23
Kraft Heinz (Packaging Division)
Chicago, IL, USA
Internal packaging for Maxwell House
Global
Large captive packaging user
24
Airlite Plastics
Omaha, NE, USA
Rigid plastic containers
Regional
Supplier of coffee canisters
25
Polykar
Montreal, Canada
Sustainable flexible films
Regional
Focus on compostable/ recyclable films
Regional Dynamics
Asia-Pacific (estimated share: 32%)
Largest and fastest-growing region, driven by rising coffee consumption in China, India, and Southeast Asia, expanding middle class, and urbanization. Packaging demand is shifting toward convenient single-serve and flexible formats, with increasing local production. Direction: Growing.
North America (estimated share: 24%)
Mature market with high per capita coffee consumption and strong demand for single-serve capsules and premium packaging. Sustainability regulations and consumer preferences are driving adoption of recyclable and compostable packaging solutions. Direction: Mature with innovation.
Europe (estimated share: 26%)
Europe remains a key market with a strong coffee culture and high demand for specialty and sustainable packaging. Stringent packaging waste regulations are accelerating the shift to recyclable mono-materials and paper-based formats, influencing global packaging design. Direction: Steady growth.
Latin America (estimated share: 10%)
Latin America is a major coffee producer and consumer, with growing demand for instant coffee and single-serve packaging. Economic volatility and price sensitivity favor cost-effective flexible packaging, while sustainability trends are gradually gaining traction. Direction: Moderate growth.
Middle East & Africa (estimated share: 8%)
The region is an emerging market with increasing coffee consumption, particularly in the Middle East. Demand is concentrated in instant coffee and food service, with packaging preferences for affordable flexible formats. Growth potential exists as coffee culture develops. Direction: Emerging.
Market Outlook (2026-2035)
In the baseline scenario, IndexBox estimates a 3.6% compound annual growth rate for the global coffee packaging market over 2026-2035, bringing the market index to roughly 142 by 2035 (2025=100).
Note: indexed curves are used to compare medium-term scenario trajectories when full absolute volumes are not publicly disclosed.
For full methodological details and benchmark tables, see the latest IndexBox Coffee Packaging market report.
After several volatile sessions, the global oil market entered the week with WTI and Brent prices slightly higher than their previous benchmarks.
Meanwhile, domestic fuel prices continued to be adjusted downwards from the afternoon of November 12th, bringing E5 RON 92-II gasoline down to below 19,400 VND/liter in Zone 1.
Recent developments in the international market are being closely watched ahead of the next fuel price adjustment, scheduled for November 19th.
Illustration.
World oil prices today, November 14, 2026: WTI and Brent both edged up.
According to reference data from November 14th, WTI crude oil prices were recorded at $88.92 per barrel, an increase of $0.22 per barrel compared to $88.70 per barrel on November 13th. In percentage terms, this represents an increase of approximately 0.25%.
At the same reference time, Brent crude oil rose from $95.95 per barrel to $96.13 per barrel, an increase of $0.18 per barrel, or approximately 0.19%.
Comparison table of world crude oil prices on November 14, 2026:
Type of oil
November 13th
November 14th
Change
WTI oil
88.70
88.92
+0.22
Brent crude oil
95.95
96.13
+0.18
Unit: USD/barrel. Prices are based on the two provided reference points, not the closing price of the trading session.
Notably, the increases for both types of oil were relatively small compared to the sharp fluctuations in previous sessions. WTI oil continued to fluctuate around $89 per barrel, while Brent remained above $96 per barrel as of the latest update.
In terms of price range, WTI oil on November 14th was recorded in the range of $87.81–$89.64 per barrel, compared to approximately $85.21–$89.14 per barrel on November 13th. The lowest price within the new range was $2.60 per barrel higher than the previous day’s data.
Meanwhile, the Brent crude oil price range on November 14th was $95.07–$97.13 per barrel, wider than the approximately $95.71–$96.07 per barrel range of November 13th.
Comparison table of oil price ranges:
Type of oil
November 13th
November 14th
WTI
85.21 – 89.14
87.81 – 89.64
Brent
95.71 – 96.07
95.07 – 97.13
Unit: USD/barrel.
Although WTI and Brent prices edged higher towards the aforementioned benchmarks, the overall trend in the global oil market still does not indicate a sustainable recovery.
According to international trading results on November 13th, both types of oil closed the week down approximately 2.5%. The prospect of increased supply and signs of weakening fuel demand in the US continued to impact the market.
This suggests that the short-term upward volatility is not yet sufficient to determine whether oil prices have reversed course after a sharp decline. The market still needs more signals from production, consumption, and energy supply and demand forecasts next week.
For Vietnam, crude oil price fluctuations are important reference information, but domestic retail gasoline and diesel prices do not change immediately with each trading session. The price of refined petroleum products on the international market during the pricing period is one of the important bases for price regulation.
Domestic fuel prices today, November 14, 2026: Maintaining the decrease from November 12.
In Vietnam, retail gasoline and diesel prices on November 14th will continue to apply the Petrolimex price list effective from 3 PM on November 12th, 2026.
In the most recent price adjustment, all petroleum products were reduced. E5 RON 92-II gasoline in Zone 1 decreased by 1,500 VND/liter, from 20,890 VND/liter to 19,390 VND/liter.
E10 RON 95-III gasoline decreased by 1,310 VND/liter, to 19,840 VND/liter, while E10 RON 95-V decreased by 810 VND/liter, to 21,840 VND/liter.
The oil group also recorded significant decreases. Diesel DO 0.05S-II decreased by 1,870 VND/liter, to 26,820 VND/liter in Zone 1. Kerosene 2-K decreased by 2,200 VND/liter, to 26,400 VND/liter.
Petrolimex fuel price list today, November 14, 2026:
Product
Region 1
Region 2
E10 RON 95-V gasoline
21,840
22,270
E10 RON 95-III gasoline
19,840
20,230
E5 RON 92-II gasoline
19,390
19,770
DO oil 0.001SV
28,620
29,190
DO 0.05S-II oil
26,820
27,350
2-K kerosene
26,400
26,920
Unit: VND/liter. Petrolimex price list effective from 3 PM on November 12, 2026.
Compared to the price adjustment on November 5th, retail prices at Petrolimex Region 1 decreased by 810 to 2,200 VND/liter, depending on the product.
Comparison table of Petrolimex prices in Zone 1 between the two adjustment periods:
Item
November 5th
November 12th
Change
E10 RON 95-V
22,650
21,840
-810
E10 RON 95-III
21,150
19,840
-1.310
E5 RON 92-II
20,890
19,390
-1,500
DO 0.001SV
30,090
28,620
-1,470
DO 0.05S-II
28,690
26,820
-1,870
2-K kerosene
28,600
26,400
-2,200
Unit: VND/liter.
The drop in fuel prices helps people save on transportation costs, while also supporting transportation and manufacturing businesses in reducing fuel expenses.
For example, with a single purchase of 40 liters of E5 RON 92-II gasoline in Zone 1, consumers pay 60,000 VND less than before the price adjustment on November 12th.
For DO 0.05S-II diesel fuel, the reduction of 1,870 VND/liter is equivalent to a saving of 187,000 VND for every 100 liters of fuel purchased in Zone 1.
However, selling prices in Zone 2 are still higher than in Zone 1 due to the characteristics of the business area. This price level applies to areas as defined by the company’s price zoning regulations.
Fuel price forecast for November 19, 2026: Will prices rise again?
According to the regular price adjustment schedule every Thursday, the next fuel price adjustment is expected to take place at 3 PM on November 19, 2026.
Following the price drop on November 12th, the global oil market is experiencing mixed fluctuations. Reference data from November 14th shows WTI and Brent prices rising slightly, but considering the entire week, the prices of both types of oil still recorded significant declines.
Therefore, it is not yet possible to confirm whether domestic gasoline and diesel prices will rise again in the next adjustment period.
If international crude oil and refined petroleum product prices continue to recover in the early trading sessions of next week, upward pressure on retail prices may emerge.
Conversely, if world refined product prices remain low or continue to fall, domestic gasoline and diesel prices are likely to remain stable or be further reduced.
Besides fluctuations in product prices, exchange rates, and factors such as taxes, business costs, and regulatory stabilization mechanisms, all of these can affect operational results.
Notably, the increase or decrease in prices of E5 RON 92 gasoline, E10 RON 95 gasoline, and diesel fuel may not necessarily be the same due to differences in supply and demand for each product.
At present, there is insufficient data from the new pricing period to accurately predict the adjustment on November 19th.
For the time being, consumers will continue to purchase gasoline and diesel according to the Petrolimex price list effective from November 12th. The developments in international fuel prices in the coming days will be a key factor in assessing the possibility of changes in domestic retail prices.
2026.11.13 2026.11.13 WTI: Elliott Wave Analysis and Forecast for 13.11.26–20.11.26
Alex Geutahttps://www.litefinance.org/blog/authors/alex-geuta/
The article covers the following subjects:
Major Takeaways
Main scenario: Consider long positions from corrections above 84.25 with a target of 107.00–115.50. A buy signal: the price holds above 84.25. Stop Loss: below 82.75, Take Profit: 107.00–115.50.
Alternative scenario: Breakout and consolidation below 84.25 will allow the asset to continue declining to the levels of 78.30–73.40. A sell signal: the level of 84.25 is broken to the downside. Stop Loss: above 85.75, Take Profit: 78.30–73.40.
Main Scenario
Consider long positions from corrections above 84.25 with a target of 107.00–115.50.
Alternative Scenario
Breakout and consolidation below 84.25 will allow the asset to continue declining to the levels of 78.30–73.40.
Analysis
On the weekly chart, a descending correction has likely finished developing as the second wave of larger degree (2) and an ascending third wave (3) is forming. On the daily time frame, the first wave of smaller degree 1 of (3) has apparently formed, a downward correction has been completed as the second wave 2 of (3), and the third wave 3 of (3) is developing, with wave i of 3 still unfolding as its part. On the H4 time frame, wave (iii) of i has formed, a local correction has been completed as wave (iv) of i, and wave (v) of i has started developing. If the presumption is correct, WTI will continue to rise to 107.00–115.50. The level of 84.25 is critical in this scenario as a breakout below it will enable the asset to continue declining to the levels of 78.30–73.40.
This forecast is based on the Elliott Wave Theory. When developing trading strategies, it is essential to consider fundamental factors, as the market situation can change at any time.
Price chart of USCRUDE in real time mode
The content of this article reflects the author’s opinion and does not necessarily reflect the official position of LiteFinance broker. The material published on this page is provided for informational purposes only and should not be considered as the provision of investment advice for the purposes of Directive 2014/65/EU.
According to copyright law, this article is considered intellectual property, which includes a prohibition on copying and distributing it without consent.
U.S. Dollar Index gains ground as traders focus on Producer Prices data. PPI increased by +0.3% month-over-month in October, compared to analyst forecast of +0.4%. Core PPI grew by +0.3%, in line with analyst estimates.
Currently, U.S. Dollar Index is trying to settle above the resistance at 103.15 – 103.30. In case this attempt is successful, U.S. Dollar Index will head towards the next resistance level, which is located in the 104.60 – 104.75 range. I’d note that RSI is in the overbought territory, so the risks of a pullback are increasing.
2026.11.13 2026.11.13 XAU/USD: Elliott Wave Analysis and Forecast for 13.11.26–20.11.26
Alex Geutahttps://www.litefinance.org/blog/authors/alex-geuta/
The article covers the following subjects:
Major Takeaways
Main scenario: Consider short positions from corrections below the level of 4,145.15 with a target of 3,593.00–3,127.70. A sell signal: the price holds below 4,145.15. Stop Loss: above 4,215.00, Take Profit: 3,593.00–3,127.70.
Alternative scenario: Breakout and consolidation above the level of 4,145.15 will allow the asset to continue rising to the levels of 4,381.26–4,708.00. A buy signal: the level of 4,145.15 is broken to the upside. Stop Loss: below 4,075.00, Take Profit: 4,381.26–4,708.00.
Main Scenario
Consider short positions from corrections below the level of 4,145.15 with a target of 3,593.00–3,127.70.
Alternative Scenario
Breakout and consolidation above the level of 4,145.15 will allow the price to continue rising to the levels of 4,381.26–4,708.00.
Analysis
An ascending third wave of larger degree (3) has likely formed on the weekly chart, and a bearish correction is developing as the fourth wave (4). On the daily time frame, wave A of (4) has apparently formed, and a correction has been completed as wave B of (4). On the H4 time frame, wave C of (4) is developing. Within it, the first wave of smaller degree i of C has formed, a local correction has been completed as the second wave ii of C, and the third wave iii of C is developing. If the presumption is correct, XAU/USD will continue to decline to 3,593.00–3,127.70. The level of 4,145.15 is critical in this scenario as a breakout above it will enable the asset to continue rising to the levels of 4,381.26–4,708.00.
This forecast is based on the Elliott Wave Theory. When developing trading strategies, it is essential to consider fundamental factors, as the market situation can change at any time.
Price chart of XAUUSD in real time mode
The content of this article reflects the author’s opinion and does not necessarily reflect the official position of LiteFinance broker. The material published on this page is provided for informational purposes only and should not be considered as the provision of investment advice for the purposes of Directive 2014/65/EU.
According to copyright law, this article is considered intellectual property, which includes a prohibition on copying and distributing it without consent.