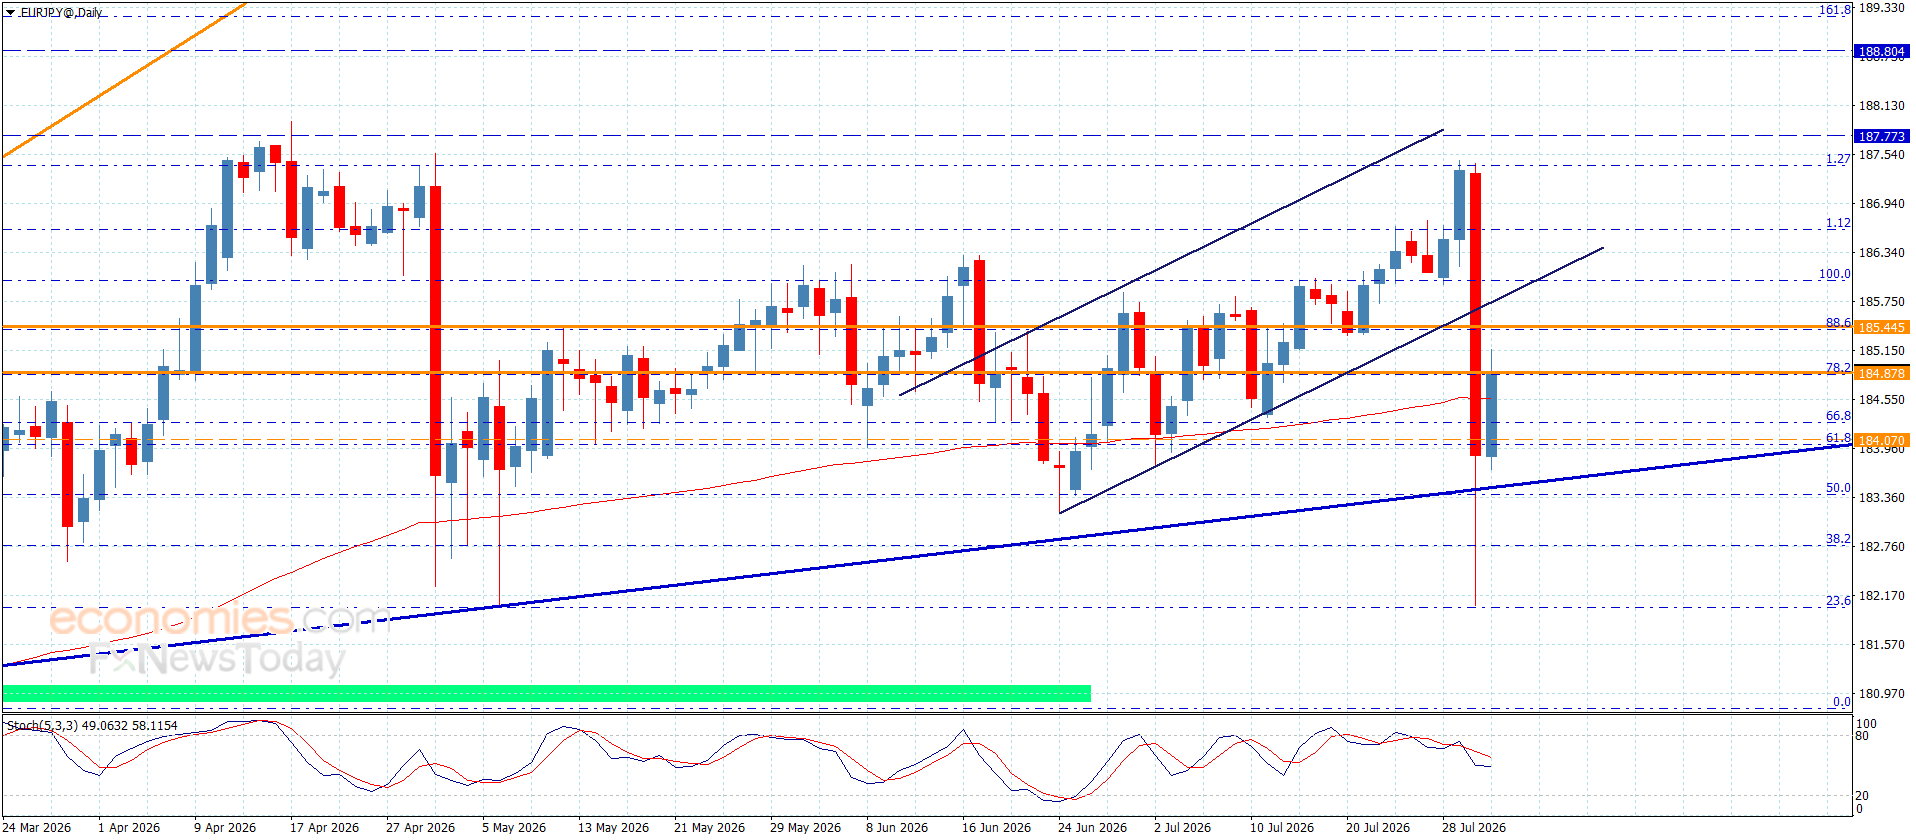
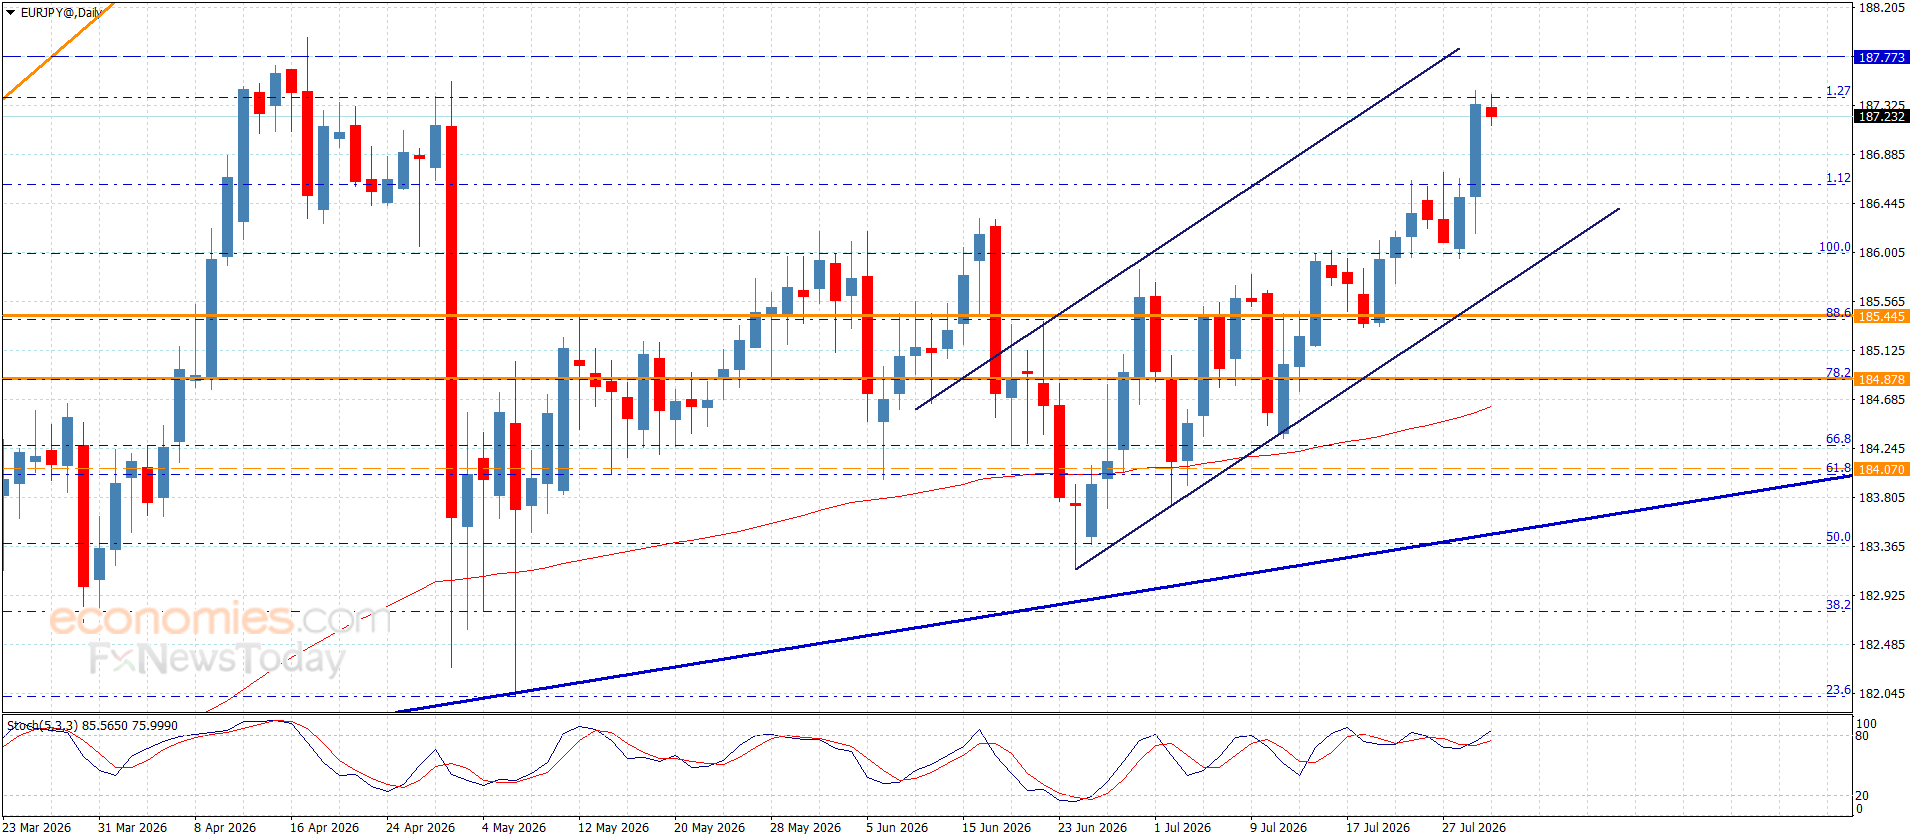
The EURJPY pair maintained its sideways movement below the resistance barrier at 187.40 during yesterday’s trading before reacting to the negative economic data. This led to a sharp bearish move, as the pair slipped below the ascending channel support at 185.65, suffering significant losses and reaching 182.45, before quickly rebounding to stabilize around 184.75.
For now, we will rely on the 185.40 level as an important additional resistance barrier. Repeated stability below this level would confirm the pair’s shift toward the bearish scenario, with the price expected to move lower toward 184.00, followed by an attempt to confirm a break below the support level at 183.95.
The expected trading range for today is between 184.00 and 185.30
MUFG expects USD/JPY to move back below 160 over time, with suspected intervention and faster Bank of Japan rate hikes increasing the risks for Dollar buyers.
The Japanese Yen rallied sharply on Thursday, with USD/JPY falling from close to 164 to below 158 before recovering above 160 in Asian trading.
The move came amid widespread speculation that Japanese authorities had intervened in the currency market ahead of the Bank of Japan meeting. Intervention was not officially confirmed, although reports also suggested that the US had conducted a rate check on USD/JPY.
US Treasury Secretary Scott Bessent added to the pressure by describing the Yen as “very undervalued”, while Japan’s top currency official Atsushi Mimura acknowledged concerns over the recent weakness without commenting directly on intervention.
MUFG said the scale of the move was similar to previous episodes of official action.
“The scale of the USD/JPY move is quite similar to past Yen selling interventions including in 2024, but may have a bit more to go based on historical experience of perhaps more than a 5% move,” the bank said.
USD/JPY fell by more than five Yen during Thursday’s session before recovering part of the decline.
MUFG remains cautious on the pair heading into the weekend, particularly with speculative positioning still heavily tilted against the Yen.
“With JPY net shorts still elevated close to all-time highs, authorities may be looking to flush out these positions,” the bank said.
It added that traders were likely to become “more cautious on the near-term bets on JPY given the balance of risks.”
That said, MUFG does not believe intervention alone will be enough to produce a lasting reversal.
“Ultimately it boils down to fundamentals over the medium term,” the bank said. “For USD/JPY to achieve a more durable retracement lower, it would require real interest rates to rise more substantially, and for market concerns around fiscal sustainability to be addressed.”
MUFG expects the Bank of Japan to leave rates unchanged at its latest meeting, although dissenting votes in favour of a hike could strengthen expectations of earlier tightening.
The bank’s global and Japan teams forecast BOJ rate increases in September 2026 and January 2027, a faster path than markets currently price.
“This in part underpins our view for USD/JPY to move lower below the 160 levels over time,” MUFG said.
Governor Kazuo Ueda’s guidance will now be closely watched for any indication that policymakers are becoming more willing to accelerate the pace of tightening.
Image: The US Dollar to Yen year-to-date historical chart
USD/JPY remains well above its January levels despite the latest sharp reversal.
Exchange Rates UK Research
Our currency coverage draws on live market data, official economic releases and published bank research.
The USD/JPY pair is seen building on the previous day’s late recovery from sub-158.00 levels, or the lowest since May 14, and gaining positive traction during the Asian session on Friday. Spot prices climb back above the 160.50 level amid the emergence of some US Dollar (USD) buying and some repositioning trade ahead of the highly anticipated Bank of Japan (BoJ) rate decision.
From a technical perspective, strength beyond the 160.00 psychological mark and the 38.2% Fibonacci retracement level of the sharp corrective pullback from a four-decade peak backs the case for further intraday gains. However, the 14-period Relative Strength Index (RSI) near 31 and a negative Moving Average Convergence Divergence (MACD) reading around -0.43 suggest lingering downside pressure.
Hence, any further move up is more likely to confront stiff resistance near a dense Fibonacci band led by the 50.0% retracement at 160.99 and further capped by the 61.8% and 78.6% retracements at 161.69 and 162.69, respectively. Bulls would need to clear the said barriers to ease immediate pressure and pave the way for a rise back towards the cycle high region at 163.97.
On the downside, initial support is seen at the 38.2% Fibonacci retracement at 160.28, ahead of the 23.6% level at 159.41 and the structural swing low zone at 158.00. A convincing break and acceptance below the handle will be seen as a fresh trigger for bearish traders and pave the way for an extension of the suspected intervention-led corrective decline.
(The technical analysis of this story was written with the help of an AI tool. Know more.)
USD/JPY 4-hour chart
Japanese Yen Price This week
The table below shows the percentage change of Japanese Yen (JPY) against listed major currencies this week. Japanese Yen was the strongest against the US Dollar.
USD
EUR
GBP
JPY
CAD
AUD
NZD
CHF
USD
-1.01%
-0.86%
-1.85%
-0.51%
-0.33%
-1.02%
-1.15%
EUR
1.01%
0.14%
-0.83%
0.52%
0.70%
-0.01%
-0.14%
GBP
0.86%
-0.14%
-1.06%
0.39%
0.56%
-0.15%
-0.28%
JPY
1.85%
0.83%
1.06%
1.33%
1.52%
0.81%
0.59%
CAD
0.51%
-0.52%
-0.39%
-1.33%
0.15%
-0.51%
-0.65%
AUD
0.33%
-0.70%
-0.56%
-1.52%
-0.15%
-0.70%
-0.84%
NZD
1.02%
0.00%
0.15%
-0.81%
0.51%
0.70%
-0.14%
CHF
1.15%
0.14%
0.28%
-0.59%
0.65%
0.84%
0.14%
The heat map shows percentage changes of major currencies against each other. The base currency is picked from the left column, while the quote currency is picked from the top row. For example, if you pick the Japanese Yen from the left column and move along the horizontal line to the US Dollar, the percentage change displayed in the box will represent JPY (base)/USD (quote).
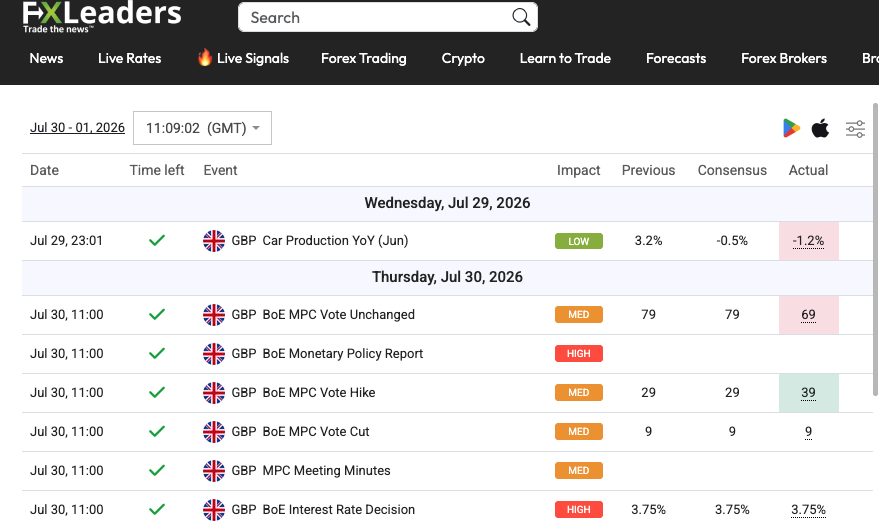
MUFG warned that Sterling needed stronger September BoE hike conviction to advance, but Thursday’s guidance left markets with little reason to bring tightening forward.
The Euro to Pound exchange rate (EUR/GBP) traded around 0.8574 on Thursday afternoon after the Bank of England held interest rates at 3.75%, with Sterling failing to draw lasting support from a surprisingly hawkish 6–3 vote.
Huw Pill, Megan Greene and Catherine Mann backed an immediate increase, but the guidance suggested most policymakers remain prepared to wait for clearer evidence that higher energy costs are feeding into persistent domestic inflation.
EUR/GBP initially moved lower before rebounding above 0.8585, then settled back near 0.8574. The pair remained around 0.4% lower for July but was well above its mid-month low near 0.8467.
MUFG had argued before the announcement that the unchanged rate itself would not determine Sterling’s direction. With “nothing priced for today”, the bank said markets would focus instead on “the vote, the communication in the statement, the minutes and the updated forecasts”.
That proved accurate. The three dissenting votes looked supportive for the Pound at first glance, yet the wider message did not materially increase confidence that a September hike was coming.
MUFG had set a clear test for Sterling: “For market rates to move higher and the pound to advance in response to today’s meeting we will need to see increased conviction on a September rate hike.”
The decision did little to meet that threshold.
The Monetary Policy Committee acknowledged that inflation risks remain skewed higher, particularly because of energy prices and the uncertain geopolitical backdrop. However, it also pointed to “clear signs of underlying disinflation” and limited evidence so far of stronger second-round effects.
That combination leaves the Bank concerned, but not yet ready to act.
MUFG had warned that if the inflation forecasts showed prices returning to target over time, “the take-away is likely to be that there is time to assess the inflation risks”.
In that scenario, the bank said “pricing for a September rate hike could ease back somewhat, taking the pound lower”. Thursday’s Sterling reaction was consistent with that interpretation.
Image: EUR/GBP intraday price chart showing the post-BoE rise above 0.8585 and subsequent retreat
The intraday move captured the market’s changing reading of the announcement. EUR/GBP initially fell as traders reacted to the three votes for higher rates, but the decline quickly reversed once the guidance was absorbed.
The pair’s jump above 0.8585 suggested the vote count was not enough to convince investors that the next increase had moved materially closer. Its later retreat showed that the decision was not decisively dovish either.
Energy prices remain the strongest argument for keeping a hike in play.
MUFG said the backdrop had become “difficult with crude oil and natural gas prices rebounding significantly”, while a prolonged increase in energy costs “could certainly force the BoE to act, even in circumstances of mixed labour market conditions”.
That risk prevents markets from abandoning tightening expectations altogether. It also helps explain why Sterling’s losses were contained rather than severe.
Image: EUR/GBP year-to-date chart showing the July recovery from below 0.8470 towards 0.8575
The wider price history shows EUR/GBP recovering sharply after Sterling’s strongest run of the year.
The pair fell below 0.8470 in July before rebounding by more than a cent. Thursday’s decision has not broken that recovery, and the cross is again approaching levels that repeatedly contained declines during May and June.
The implication is straightforward: EUR/GBP does not require a major improvement in the Euro outlook to move higher. A modest reduction in expected UK rate support may be enough.
Near-Term EUR/GBP Forecast: September BoE Expectations Remain the Deciding Factor
MUFG expected Sterling to remain “well supported at these levels” only on the assumption that “pricing for a September rate hike holds up”.
After Thursday’s announcement, that assumption looks less secure.
The 6–3 vote keeps tightening risk alive, but the guidance suggests the majority is comfortable waiting. Unless energy prices rise sharply or incoming inflation data deteriorate, September may prove too early for another move.
A further decline in September hike expectations could send EUR/GBP back above 0.8590 and towards July’s high near 0.8619.
Pound Sterling would regain firmer support if markets conclude that the three dissenters represent the beginning of a broader hawkish shift. That would require stronger inflation evidence or clearer concern from the MPC’s swing voters.
The vote looked hawkish. The message was more patient. For EUR/GBP, that leaves the recovery from July’s lows intact.
Register now to be able to add articles to your reading list.
” aria-hidden=”true”>
The British pound rose against the US dollar on Thursday after the Bank of England decided to keep its base rate unchanged at 3.75%. This decision was in line with the markets and showcases the central bank’s carefulness regarding inflation. The soft dollar helped GBP in staying supported with USD above the important levels of technical pressure. This came after the Fed kept the rates unchanged a day before.
The BoE believes, and the forecasts suggest, that inflation will experience a significant dip. The high prices of energy, due to the geopolitical unrest in the Middle East, will increase inflation again. There is now a combination of inflation, and an economy and labor market in a state of recession. The BoE now faces the problem of inflation vs recession.
The Bank of England’s MPC voted to keep the rate at 3.75% for the fifth meeting in a row.
This decision was on the back of the Bank’s Monetary Policy Report that has shown a significant dip in inflation. The UK consumer price index shows inflation rates of 2.6% in June, however, energy is expected to become more expensive and push inflation higher in the second half of 2026. The MPC believes that the current rate will ensure that the inflationary pressures, if any, will be temporary.
Officials noted that a more restrictive monetary policy weakens household spending and business investment. A more flexible labor market will likely prevent higher energy prices from producing broad-based wage and price inflation.
Market Thoughts on Further Comment from Governor Bailey
Market participants are focusing on the MPC vote split, along with upcoming inflation and growth forecasts, as the monetary policy forecast is already in the price following the rate decision. Andrew Bailey’s comments will also be watched for policy direction.
The market will assess whether the decision makers are keeping the door open for additional tightening if inflation persists, especially if geopolitically-driven energy price spikes also come into play.
Increased concern about inflation from the BoE would likely support the pound. The opposite would likely be true if a more dovish, growth-concerned approach is pursued.
The pound also strengthened after the Federal Reserve chose to keep the target policy rate between 3.50 and 3.75. While three Federal Reserve policy makers were in favor of tightening, Fed Chair Kevin Warsh did not signal an imminent decision to tighten, which caused a September rate increase to be taken off the table, decreasing Treasury yields and strengthening the pound along with other major currencies.
The focus will be on the upcoming U.S. economic releases, especially the PCE deflator and second quarter GDP, as these may impact forecasts of U.S. monetary policy more than others.
Diverging Economic Views
UK inflation appears to be under control, but UK economic prospects remain weak. UK consumers and businesses remain under the pressure of high energy costs. This, paired with a slacking labor market and tightening financial conditions, suggests further weakness in UK economic prospects.
In contrast, the US economy is performing better with greater productivity and investment. This tilt in the economic balance is USD supportive in the medium term as the dollar has weakened recently on the back of FOMC comments.
With both central banks on hold, the main drivers of the GBP/USD rate will be divergence in economic data, inflation and central bank communications.
GBP/USD Technical Analysis: Key Support Bullish
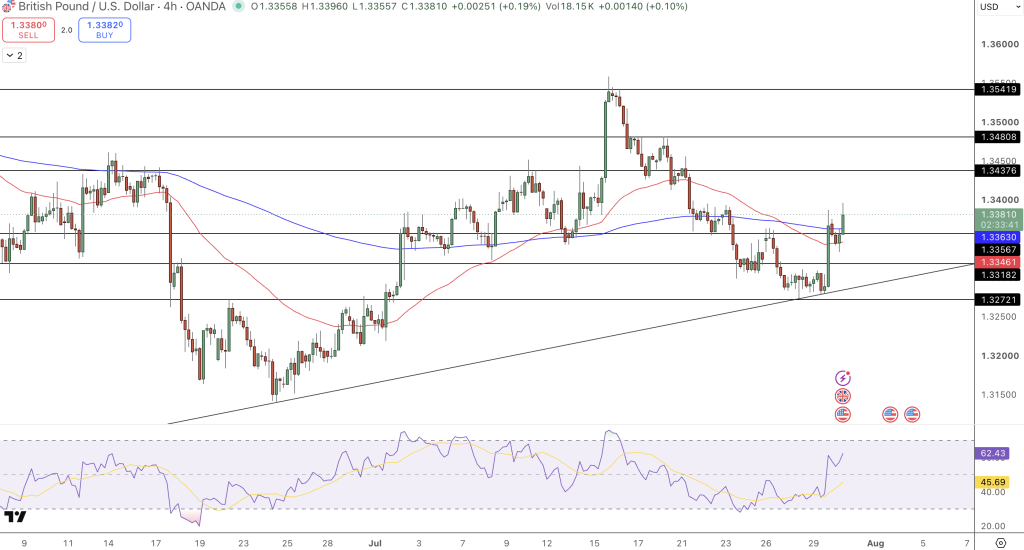
GBP/USD is continuing its upward trend after testing and successfully bouncing off of the rising trendline at 1.3272, with buyers breaking the 50-period EMA at 1.3346, and the 200-period EMA at 1.3363. Renewed buying momentum was confirmed by a bullish engulfing candle, and the pattern of higher lows was maintained.
GBP/USD Price Chart – Source: Tradingview
The next resistance level is at 1.3383, where prior price action has resulted in a pause. A break and close above this level will open price action to the 1.3438, 1.3481 and the July peak at near 1.3542.
Momentum indicators are bullish, with the RSI at approximately 62, indicating bullish momentum. The 50 and 200 period EMAs are converging and if price momentum continues, a bullish crossover of the EMAs is likely.
Resistance: 1.3383, 1.3438, 1.3481, 1.3542
Support: 1.3363, 1.3318, 1.3272
GBP/USD Outlook
The decision by the Bank of England (BOE) to keep rates on hold was largely expected. Therefore, the market was second guessing the BOE’s future inflation assessment and monetary policy signaling. The BOE stated that inflation was on a downward trend; however, they highlighted that the situation may be reversed by higher energy prices in the second half of the year.
GBP/USD is technically in a good position while trading above the 1.3346 – 1.3363 EMA support range. A break above 1.3383 would add to the bullish momentum with 1.3481 in the line of sight. A break below 1.3318 would indicate a loss of bullish momentum, and would likely target the ascending trendline support, which is at 1.3272.
Arslan Ali Butt
Lead Markets Analyst – Multi-Asset (FX, Commodities, Crypto)
Arslan Ali Butt serves as the Lead Commodities and Indices Analyst, bringing a wealth of expertise to the field. With an MBA in Behavioral Finance and active progress towards a Ph.D., Arslan possesses a deep understanding of market dynamics.
His professional journey includes a significant role as a senior analyst at a leading brokerage firm, complementing his extensive experience as a market analyst and day trader. Adept in educating others, Arslan has a commendable track record as an instructor and public speaker.
His incisive analyses, particularly within the realms of cryptocurrency and forex markets, are showcased across esteemed financial publications such as ForexCrunch, InsideBitcoins, and EconomyWatch, solidifying his reputation in the financial community.
The US dollar initially was a bit weak on Wednesday but has since bounced a bit as we are waiting for the interest rate decision coming out of the Federal Reserve.
USD/JPY
The US dollar fell early against the Japanese Yen during the trading session on Wednesday as the market continues to see a lot of noisy behavior. Ultimately, this is a market that I think a lot of people will look at through the prism of the interest rate differential, and that of course has been paying traders quite nicely.
Now the question, of course, is whether or not the Federal Reserve interest rate decision later in the day is going to be a headline event or not. There’s about a 40% chance of an interest rate hike according to the FedWatch tool, and that means that a significant number of traders, one way or the other, are going to be surprised. That should make for a nice volatile move.
Interest Rate Differential Continues to Drive Long-Term Trend
Ultimately, the interest rate differential between the United States dollar and the Japanese Yen remains wide, and that allows traders to take advantage of getting paid at the end of every day. In fact, that’s what I’ve done for the last several months. I’ve been a buyer of this pair, and I’ve added every time it dipped.
I don’t have any concerns about shorting, quite frankly. This interest rate differential will continue to pay traders over the longer term, even if the Federal Reserve does not hike and the Bank of Japan raises. Yes, that could cause a little bit of short-term volatility, but at the end of the day, the trend is well entrenched. We are trading at levels not seen since the 1980s, and there’s a reason for that.
I look at the 50-day EMA and the 162-yen level as support at the moment. I do not have a target per se but based on the rounding bottom that just broke out of a 40-year pattern, the measured move is 224 yen. That would take some time, obviously.
Christopher Lewis is a technical analyst and market commentator at DailyForex with more than two decades of trading experience in Forex and other leveraged markets. Based in Columbus, Ohio, he specializes in chart-based analysis of major currency pairs, stock indices, commodities, and energy markets, focusing on clear support and resistance levels, trend structure, and risk management. Christopher produces daily written and video analysis for traders who rely on technical setups to navigate volatile market conditions
As seen on:Pairs Of Aces Podcast,The Trader Guy, FXEmpire
The Federal Open Market Committee approved the following statement for release by a 9 3 vote: The Committee decided to maintain the target range for the federal funds rate at 3-1/2 to 3-3/4 percent, in support of the Federal Reserve’s dual mandate. The Committee is continuing its policy of maintaining ample reserves in the banking system. Economic activity is expanding at a solid pace despite elevated uncertainty that owes, in part, to the conflict in the Middle East. Productivity growth and capital investment are strong. Job gains have kept pace with the workforce, and the unemployment rate has changed little. Inflation remains elevated relative to the Committee’s 2 percent goal, in part reflecting supply shocks that have driven price increases in certain sectors, including energy. The Committee will deliver price stability. Voting against the monetary policy action were Beth M. Hammack, Neel Kashkari, and Lorie K. Logan, who preferred to raise the target range for the federal funds rate by 1/4 percentage point at this meeting. *fed: Hammack, Kashkari And Logan Dissent In Favor Of Rate Hike Fomc Statement Compare Fed: Economic activity is expandng at solid pace despite elevated uncertainty. Fed: FOMC is continuing policy of maintaining ample reserves in the banking system.
The EURJPY pair succeeded in resuming the bullish trend by surpassing the barrier at 186.65, opening the way for reaching the extra positive stations to notice recording some previously suggested targets by reaching 187.45 level.
The stability of the trading within the bullish channel’s levels and providing positive momentum by the main indicators makes us expect reaching 187.80, surpassing it will open the way for recording new historical gains that might begin at 188.25 and 188.80.
The expected trading range for today is between 186.65 and 187.80
The Pound to US Dollar (GBP/USD) exchange rate remained close to a three-week low on Tuesday as another bout of weakness in technology shares dampened market sentiment.
At the time of writing, GBP/USD was trading at around $1.3228, slightly down from Tuesday’s opening levels.
The US Dollar (USD) retained a firm footing on Tuesday as investors continued to seek the safety of the ‘Greenback’ amid a prolonged selloff in global technology stocks.
The latest wave of risk aversion was driven by heavy losses across semiconductor and artificial intelligence-related companies, with investors becoming increasingly concerned about the scale of borrowing undertaken to finance AI infrastructure projects.
At the same time, growing competition from Chinese chip manufacturers added to pressure in global equity markets.
Even so, broader gains for the US Dollar remained limited as the improving geopolitical backdrop in the Middle East helped temper demand for traditional safe-haven assets.
The Pound (GBP) traded without a clear direction on Tuesday as the lack of significant UK economic data left investors with little fresh incentive to reposition.
Save on Your GBP/USD Transfer
Get better rates and lower fees on your next international money transfer.
Compare TorFX with top UK banks in seconds and see how much you could save.
Sterling also remained anchored by caution ahead of Thursday’s Bank of England (BoE) policy announcement.
Markets overwhelmingly expect policymakers to leave interest rates unchanged at 3.75%, meaning the accompanying guidance is likely to determine the Pound’s next move.
Should the BoE refrain from hinting that further policy tightening remains a possibility later this year, Sterling could struggle to attract meaningful support.
Near-Term GBP/USD Forecast: Fed Decision to Drive Midweek Trade
Attention will shift to the Federal Reserve on Wednesday as the US central bank announces its latest interest rate decision.
Although the Fed is expected to leave borrowing costs unchanged, investors will closely scrutinise the accompanying statement for clues on the future path of monetary policy.
While Chair Kevin Warsh has moved away from providing explicit forward guidance, markets will still be looking for signals that policymakers remain open to another interest rate increase in September.
Until then, the Pound to US Dollar (GBP/USD) exchange rate may remain trapped within a narrow range as traders await the outcome of both the Federal Reserve and Bank of England meetings.
Like this piece? Please share with your friends and colleagues:
International Money Transfer? Ask our resident FX expert a money transfer question or try John’s new, free, no-obligation personal service! ,where he helps every step of the way,
ensuring you get the best exchange rates on your currency requirements.
Economists say the Dollar-Yen could extend higher unless the BoJ signals faster rate hikes, with its three-month forecast at 159 now requiring several factors to align.
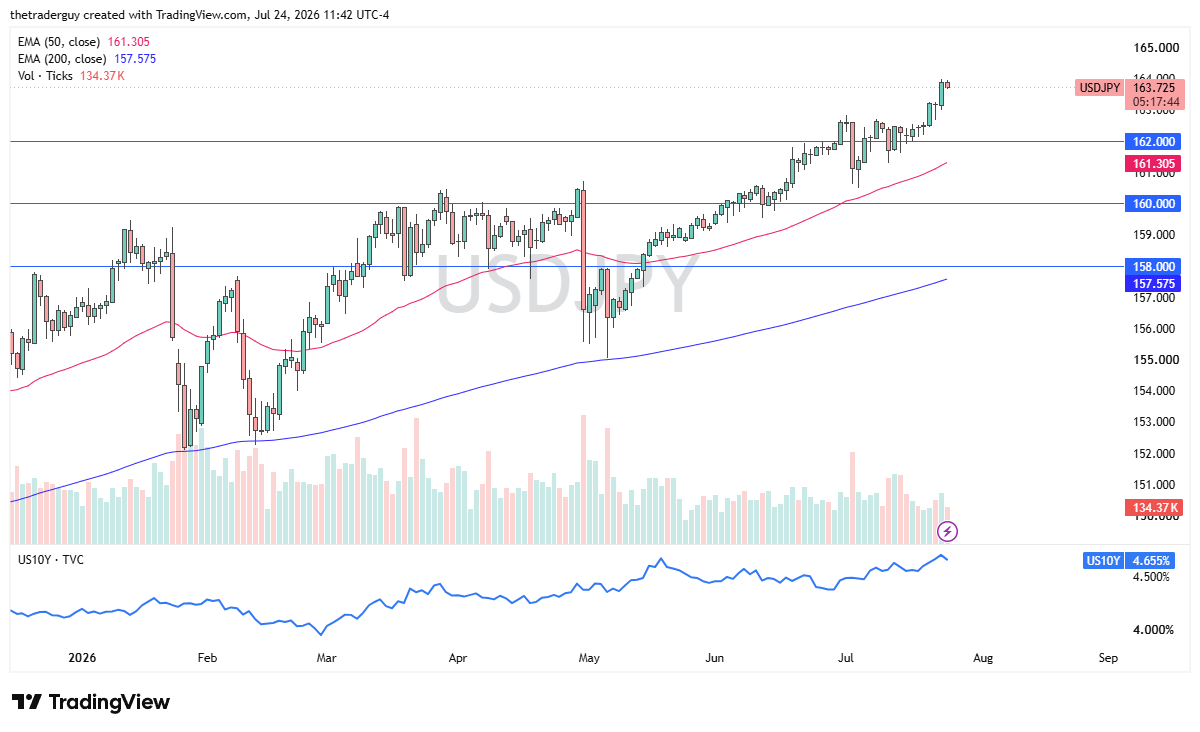
The US Dollar traded close to 163.84 against the Japanese Yen on Wednesday, holding near its highest level of 2026 as markets awaited policy decisions from both the Federal Reserve and Bank of Japan.
USD/JPY has gained around 4.5% since the end of December and approximately 0.8% in July alone. The pair has also risen in five of the past six months, leaving the Yen under sustained pressure.
Rabobank says Friday’s BoJ meeting will come with one advantage: policymakers will already know the outcome of the Fed decision.
That matters because the bank believes the FOMC “may have more impact on the USD/JPY exchange rate than” the BoJ’s own announcement.
A surprise Fed hike would likely deliver another powerful Dollar boost. Rabobank does not expect that outcome, however, and says unchanged US rates could instead trigger “a little profit-taking on long USD positions”.
The Yen’s bigger test comes a day later.
Rabobank argues that recent BoJ comments may have been “specifically aimed at preparing markets for hawkish signals” from Friday’s meeting. Without them, the risk is straightforward: “an absence of hawkish signals from the BoJ this week could open the door for further upside pressure on USD/JPY”.
Image: USD/JPY year-to-date chart showing the climb from January lows near 152 towards 164
USD/JPY’s path this year helps explain why Rabobank thinks the BoJ cannot afford an ambiguous message. The pair has not simply spiked towards 164; it has rebuilt its advance in stages since May, repeatedly recovering from shallow setbacks.
That persistence is the uncomfortable part for Tokyo. Verbal warnings and earlier Ministry of Finance intervention have slowed the move at times, but neither has changed its direction for long. The chart therefore supports Rabobank’s view that intervention alone may be “too costly” when the underlying force is an appreciating US Dollar.
Rabobank notes that the MoF has not bought Yen in the open market since spending JPY11.73 trillion between late April and late May.
One explanation is cost. The bank says officials may simply consider it “too costly to push against an appreciating USD”, particularly while US rate expectations remain firm.
There are signs that Japanese policy support has had some impact. Although USD/JPY has climbed sharply, the Yen is still the fourth-best-performing G10 currency over the past three months because the Dollar has strengthened even more broadly.
Rabobank says this suggests “both the MoF’s intervention and the hawkish signals from the BoJ have had some impact in supporting the JPY”.
Near-Term USD/JPY Forecast: A Move Back to 159 Needs a Hawkish BoJ and Softer Fed Expectations
Rabobank maintains a three-month USD/JPY forecast of 159, but admits that target “currently looks optimistic”.
A faster BoJ tightening cycle would help. The bank says an October rate increase, rather than waiting until December, could provide the Yen with support.
Japan’s inflation backdrop gives policymakers room to sound firmer. The BoJ has said an underlying price measure remains well above its 2% target, while wage negotiations have delivered another strong result.
Even that may not be enough on its own.
Rabobank says a move to 159 would likely require “various factors to come together”: greater reassurance over Japan’s fiscal outlook, a clearly hawkish BoJ and a decline in fears of further Fed tightening.
The final ingredient may prove decisive. As the bank puts it, “how far the JPY can recover versus the USD, if at all, is likely to be determined” by the Fed Chair’s message.