The main category of All News Articles.
You can use the search box below to find what you need.
[wd_asp id=1]
The main category of All News Articles.
You can use the search box below to find what you need.
[wd_asp id=1]
EUR/USD is losing ground as traders worry about hawkish Fed and focus on rising oil markets. Oil prices gained 2% amid no signs of additional progress in U.S. – Iran talks.
Currently, EUR/USD is trying to settle below the support level at 1.1110 – 1.1125. In case this attempt is successful, EUR/USD will move towards the next support, which is located in the 1.1015 – 1.1030 range. RSI has recently moved into oversold territory, but there is enough room to gain additional downside momentum in case the right catalysts emerge.
Gold (XAUUSD) fell -0.54% today and traded near $4,117 per ounce ahead of U.S. inflation data.
Markets are now betting on 84% odds of a December rate hike. This follows October payrolls of 165,000 jobs, which were well above expectations, with unemployment at 4.1% and hourly earnings up +0.4%.
This matters because higher rates lift real yields, which also adds pressure on gold since it pays no interest. Meanwhile, the 10-year yield is near 4.88% and the 2-year yield is near 4.56%, which shows that the bond market is backing the hike case.
Hike odds were near 75% to 79% a week ago. However, Richmond Fed President Tom Barkin said the Fed should move “with care” and he has no base case for December, which means a soft CPI could cut these odds quickly.
Brent is near $92, which is down about -22% from its late-October peak above $117. Trump said further strikes on Iran are highly unlikely if a strong agreement is reached. The conflict is eight months old, and crude flows have nearly returned to pre-war levels. This shows that inflation pressure from energy could ease, which may limit how far the Fed needs to go. At the same time, falling oil could ease the safe-haven demand tied to the conflict. This means gold is now trading more on rates and inflation than on geopolitical fear.
On the other hand, Democrats won both chambers of Congress, which brought attention back to U.S. debt above $40 T. The FY2026 deficit was about $1.99 T, which represents 6.2% of GDP. Now this shows that debasement worries are supporting gold, which moved from about $3,900 to a high near $4,145 after the results.
October CPI is due today at 8:30 a.m. Eastern. Headline CPI is expected at +0.3% month over month and core CPI at +0.2%, which is below September’s core reading of +0.3%. Only the index level and monthly change will be reported because of last year’s government shutdown, which means there is no yearly figure to compare. However, September headline CPI was still 3.7% year over year.
On the other hand, traders now treat the release as an ordinary event, not a second shock. A softer reading could support a move toward $4,200, while a hotter one could lift hike odds further and drag gold below $4,000.
On the technical levels, $4,088 is the major support level for now and the second support level is at $4,051. On the upside, $4,147 is the initial resistance level. Any close above $4,130 could keep a move toward the initial resistance level. However, any close below $4,088 could drag the prices towards $4,051.
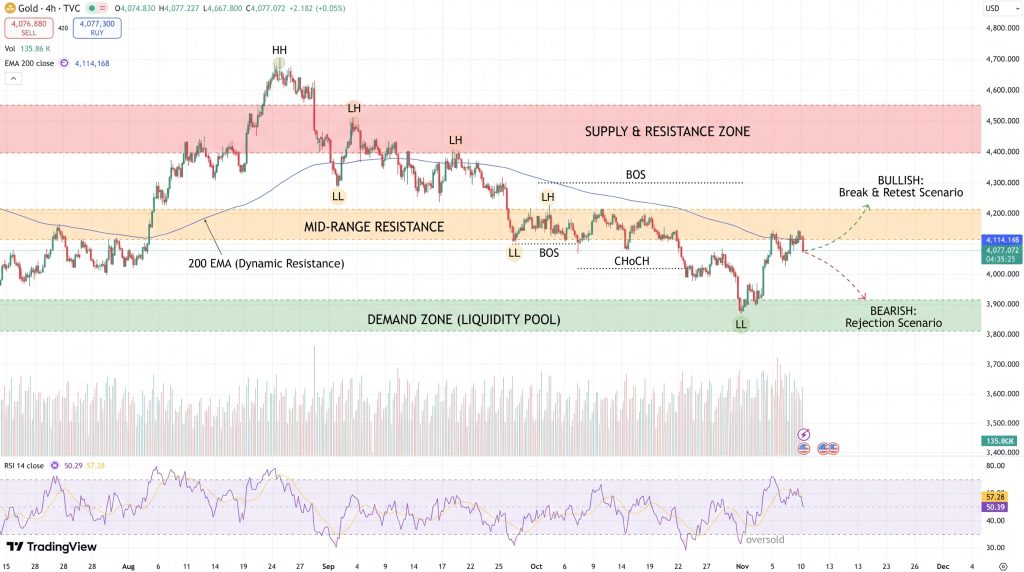
Meanwhile, smaller moving averages pattern also shows that short-term momentum is improving. For now, investors will be watching today’s CPI release, U.S. producer inflation due on Friday, and the December Fed meeting.
Gold is facing pressure from rising expectations of a December Fed rate hike. Higher interest rates lift real yields, making non-yielding gold less attractive to investors.
Gold has initial support at $4,088, followed by $4,051. On the upside, $4,147 is the initial resistance, while a close above $4,130 could support a move toward that level.
Gold is facing pressure from rising Fed rate hike expectations ahead of the October CPI release. However, concerns about U.S. debt and continued demand for gold could provide support. Investors will also watch oil prices and geopolitical developments. For now, $4,088 is the major support level, while $4,147 remains the initial resistance to watch.

Arslan Ali Butt
Lead Markets Analyst – Multi-Asset (FX, Commodities, Crypto)
Arslan Ali Butt serves as the Lead Commodities and Indices Analyst, bringing a wealth of expertise to the field. With an MBA in Behavioral Finance and active progress towards a Ph.D., Arslan possesses a deep understanding of market dynamics.
His professional journey includes a significant role as a senior analyst at a leading brokerage firm, complementing his extensive experience as a market analyst and day trader. Adept in educating others, Arslan has a commendable track record as an instructor and public speaker.
His incisive analyses, particularly within the realms of cryptocurrency and forex markets, are showcased across esteemed financial publications such as ForexCrunch, InsideBitcoins, and EconomyWatch, solidifying his reputation in the financial community.
EUR/USD traded at 1.1100 at 17:31 CET on Wednesday, down 0.0056 or 0.50% on the day. It fell as low as 1.1091 and hit an early high of 1.1175. The pair had closed Tuesday at 1.1172. The European Central Bank’s 15:00 UTC reference rate fixed the euro at 1.1127, down 0.78% from the previous fixing. During the U.S. morning the pair fell below 1.11 for the first time since May 2025, down 0.56% on the day. At the same time the U.S. Dollar Index rose 0.6% to 102.86, its highest since October 14.
The 2026 range shows how far the euro has fallen. EUR/USD peaked at 1.2067 this year, and today’s low of 1.1091 is 976 pips, or 8.1%, below that high. The pair averaged 1.1568 from January to October, so it now trades 4.0% below its 2026 average. The previous yearly low was 1.1120 in late October. On October 29, just before the ECB decision, the pair traded at 1.1131 near those lows. Today’s break below 1.1120 sets a new 2026 low. The November high is 1.1274, only 8 sessions old.
The driver is the gap between the two central banks. Tuesday’s U.S. consumer price index rose 0.4% for the month, and core rose 0.3%. Futures now price a December Fed hike at 100%, including an 11.8% chance of 50 basis points. The ECB held its deposit rate at 2.50% on October 29 and signaled a December hike that markets price at 65%, not 100%. When the Fed is expected to raise rates faster and further than the ECB, money moves toward the dollar, and EUR/USD falls.
Europe’s own problems make it worse. Eurozone inflation hit 4.0% in October, the highest since September 2023, while third-quarter growth was 0.4%. French 10-year yields have topped 5%, and the spread over German Bunds reached its widest since the eurozone debt crisis. ECB President Christine Lagarde will leave on February 7, 2027, nine months early. Each of these adds a risk premium to the euro while the dollar benefits from rate repricing.
Other currencies tell the same story. GBP/USD fixed at 1.3307, down 0.86%. USD/CHF jumped 1.12% to 0.8299, and USD/JPY rose 0.67% to 159.23. Every major currency is weaker against the dollar today. The euro’s 0.78% drop at the fixing is in line with sterling’s fall, which points to broad dollar strength rather than a euro-specific shock. That matters for the forecast: when the dollar’s rally fades, the euro should recover, as long as European risks do not widen in the meantime.
The October U.S. consumer price index rose 0.4%, above the 0.3% forecast. Core CPI rose 0.3% against a 0.2% forecast, the third monthly beat in a row. Shelter accounted for more than 30% of the increase, and headline inflation slowed from September’s 0.6%. The Bureau of Labor Statistics published no annual rate for October because of gaps from the 2025 shutdown. September’s annual rate was 3.7%.
The dollar’s rally reflects the Fed’s response. The federal funds rate is 3.75% to 4.00% after the September hike, the first since July 2023. At the October 28 FOMC meeting the Fed held rates in a 10-2 vote, with Governor Lisa Cook and Cleveland Fed President Beth Hammack voting for a hike. Futures now price a December hike at 100%: 88.2% for a quarter point and 11.8% for a half point. Traders expect three more hikes in the cycle, up from two last week.
Fed officials are leaning hawkish. Governor Christopher Waller said a 50-basis-point move should be considered if core CPI came in near 0.3%, and it did. Governor Michelle Bowman said inflation is broadening and more hikes may be needed. Richmond Fed President Tom Barkin preferred to wait. The half-point possibility is what pushed the dollar to its high since October 14, because a 50-basis-point Fed move would widen the gap with the ECB in a single meeting.
U.S. Treasury yields rose sharply. On Tuesday the 2-year jumped 17 basis points, its biggest one-day rise since April 2025. The 10-year rose 15 basis points to 5.015%, and the 30-year reached 5.37%. Today the 10-year is quoted at 4.998%, with cash Treasuries closed for Veterans Day. A 10-year above 5% draws money from euro investors looking for yield. That buying of dollars adds to the pressure on EUR/USD.
The calendar keeps the Fed in control of the dollar. U.S. October producer prices come out Friday, November 13, at 8:30 a.m. ET. The Fed meets December 8–9 and releases new projections. November CPI comes out December 10. The ECB decides on December 17, eight days after the Fed. The Fed moves first, and any surprise from it sets EUR/USD’s level going into the ECB meeting. If the Fed delivers 50 basis points with a higher path for 2027, the ECB would need a hawkish surprise of its own to keep EUR/USD from falling further.
The ECB kept rates unchanged on October 29. The deposit rate stayed at 2.50%, the main refinancing rate at 2.65% and the marginal lending rate at 2.90%. The hold followed two 25-basis-point hikes earlier in 2026. The latest, in September, was unanimous, and Lagarde called it a “no brainer.” The Governing Council discussed another hike in October and chose to wait for more data before December.
Lagarde’s message was clearly hawkish. She said that unless major developments change the outlook, “the direction of travel is clear.” Markets priced a 13% chance of a hike in October and 65% for December after the meeting. ECB policymaker Fabio Panetta said more hikes may be needed to stop inflation, and Bundesbank President Joachim Nagel has publicly backed a December move. Several forecasts expect a final 25-basis-point hike to a peak of 2.75% in December, with rates held there through 2027.
For EUR/USD, the comparison between the two central banks matters most. The Fed’s range of 3.75%–4.00% has a midpoint of 3.875%, 137.5 basis points above the ECB’s 2.50% deposit rate. If both banks hike 25 basis points in December, the gap stays at 137.5 basis points. If the Fed hikes 50 and the ECB 25, it widens to 162.5. If the Fed hikes and the ECB holds, it widens to 162.5 as well. Every realistic December outcome keeps the gap at 137.5 basis points or wider, and none narrows it.
The difference in pricing explains today’s move. Markets price a December Fed hike at 100% and an ECB hike at 65%. They also expect three more Fed hikes against one more from the ECB. The euro is losing because the market believes the Fed will hike more often and go further. A full reversal would require the ECB to signal more than one more hike, or the Fed to signal fewer.
The ECB’s own calendar is crowded. Its decision on December 17 comes with new staff forecasts. Final October eurozone inflation comes out November 18. Policymakers including Isabel Schnabel, Luis de Guindos and Philip Lane speak in the coming days. Lane has said higher borrowing costs could cool demand and reduce the need for more tightening. If his view gains ground, a December ECB hike would look like the last one, and the euro would lose further.
Eurozone inflation rose to 4.0% in October from 3.8% in September, according to Eurostat’s flash estimate. That matched expectations and is the highest since September 2023. Prices rose 0.4% for the month. A year earlier, inflation was just 2.1%. The rate has climbed for four straight months: 1.9% in February, 2.5% in March, 3.2% in August and 3.8% in September.
Energy is driving the jump. Energy prices rose 20.8% from a year earlier in October, reflecting the Iran war and disruptions in the Strait of Hormuz. Core inflation, which excludes energy, food, alcohol and tobacco, held at 2.5%, unchanged and in line with forecasts. Monthly core inflation rose 0.3%, up from 0.2% in September. Inflation excluding energy stayed at 2.3%. The rise is concentrated in energy rather than spreading across the economy.
That shapes ECB policy and the euro. If eurozone core inflation were rising like U.S. core, the ECB would have to match the Fed’s pace. With core steady at 2.5%, the ECB can argue that energy-driven inflation will fade, and that justifies a slower pace of hikes. A slower ECB means a wider rate gap with the Fed and a weaker EUR/USD. The euro area’s relatively contained core inflation is negative for the currency.
Inflation varies widely by country. Belgium’s rate climbed to 5.2% from 4.5%, Spain’s eased to 4.9% from 5.0%, and the Netherlands rose to 3.3% from 3.0%. Germany’s preliminary October CPI was 2.8% against a 3.0% forecast, down from 3.3% in September. Core inflation in Germany fell to 2.1% from 2.4%. Softer German data gives ECB doves more room and adds to the case for a single, final hike in December.
The final October data comes out November 18 and will feed into the ECB’s December forecasts. An upward revision to core would raise the odds of a December ECB hike from 65% and support the euro. Confirmation of 2.5% would keep the gap with the Fed in place. Oil is the other wild card. Brent at $92.70 keeps headline inflation high. A settlement that reopens the Strait of Hormuz would cut eurozone inflation faster than U.S. inflation, because Europe imports more of its energy. That would ease pressure on the ECB to hike.
The eurozone economy grew 0.4% in the third quarter, beating the 0.2% forecast, according to Eurostat’s preliminary flash estimate. Growth was 0.6% in the second quarter. Compared with a year earlier, GDP rose 1.3%, up from 1.2%. The wider EU grew 0.5% for the quarter and 1.5% for the year. Growth held up despite the energy shock from the Iran war.
The country breakdown shows a split economy. France’s GDP fell 0.1% for the quarter and 0.1% from a year earlier. Italy was flat at 0.0%, after 0.2% in the second quarter. Germany grew 0.2%, and its annual growth of 1.2% was the highest since the third quarter of 2022. Spain grew 0.6%, matched by Estonia and the Netherlands. Ireland’s 5.5% jump was the largest and distorts the total. Lithuania fell 1.0%.
Eurozone growth is good enough to justify a December ECB hike but not strong enough to pull ahead of the U.S. German investment is falling, and German exports have slowed sharply after a strong first half. Weaker exports hurt the euro, since they reduce demand for the currency from foreign buyers of European goods. Germany’s GfK consumer sentiment index sits at -30.8 for November, close to its weakest levels, a sign that households are cutting back as energy prices rise.
France is the biggest weak spot. Its economy is shrinking while its bond yields hit 24-year highs. That combination raises doubts about its finances. A contracting economy collects less tax, which widens the deficit and pushes yields higher. For the euro, France is a source of risk premium that has nothing to do with ECB rates. When that risk flares up, EUR/USD can fall even without any change in rate expectations.
Eurostat publishes its second estimate of third-quarter GDP on November 13, with more detail on spending and employment. Further revisions follow on December 7 and January 19, 2027. A revision down to 0.2% would cut the odds of a December ECB hike and weaken the euro. A confirmation at 0.4% supports the ECB’s case to hike. Growth data matters less for the euro right now than U.S. inflation or French yields, but it affects how confident the ECB is in its next move.
French government bonds are the euro’s main domestic risk. On October 22, France’s 10-year yield rose to 5.05%, its highest since July 2002. The spread over German 10-year Bunds widened to 160 basis points, the widest since the eurozone sovereign debt crisis. Another estimate put the spread as high as 174 basis points that day. In early October the spread passed 150 basis points, and France’s debt office announced plans to borrow a record €340 billion next year.
The pressure has built over several months. France’s 10-year yield rose 1.4 percentage points in three months. The quarter ending in September was the worst quarter for French government debt since 1987. The yield is up 162 basis points over 12 months. France’s fiscal watchdog called the government’s budget assumptions “optimistic.” Social unrest and an upcoming presidential election in spring 2027 add political risk. At a press conference, Lagarde said French problems do not meet the threshold for the ECB to step in with its bond-buying backstop.
Lagarde’s departure is tied to France. She will leave on February 7, 2027, nine months before her term ends in October 2027. She said she wanted to speak more freely about politics, and reports said she could no longer stay neutral on the situation in France. Leaving early lets European leaders choose her successor before the French election. For markets it adds uncertainty: a new ECB president takes over in the middle of a hiking cycle and a French fiscal standoff.
This matters for the euro in two ways. A wide French spread signals a risk of the euro area splitting along debt lines, which pushes investors out of euros in general. It also limits the ECB. Every hike raises France’s borrowing costs and could widen the spread further. If French yields rise sharply, the ECB may hold back on hikes, which would widen the gap with the Fed. A calm French market lets the ECB tighten. A stressed French market holds it back.
The spread is now an important gauge for the euro. A narrowing of the OAT-Bund spread toward 120 basis points would ease the risk premium and support a euro rebound toward 1.1290. A widening back above 160 basis points would add downside risk. The French budget debate, credit-rating reviews and any ECB statements about its bond-buying backstop are all events that can move EUR/USD.
The U.S. Dollar Index rose 0.6% during the day to 102.86, its highest since October 14. It closed Tuesday at 101.70 after a 0.27% decline, then jumped 30 points in a short burst to 101.97 before extending gains. EUR/USD makes up 57.6% of the Dollar Index, so a weak euro accounts for most of the index’s move. Today’s rally is broad, though, and spread across all major currencies.
The other dollar pairs confirm it. USD/JPY rose 0.67% to 159.23 at the fixing, close to the 160 level where Japanese authorities have stepped in before. USD/CHF jumped 1.12% to 0.8299, the biggest move among the majors, as the Swiss franc lost its usual safe-haven support to rising U.S. yields. GBP/USD fell 0.86% to 1.3307. The euro’s 0.78% drop at the fixing was in the middle of the pack, which shows it is not being singled out.
That matters for the forecast. If the euro were falling more than other currencies, the cause would be European, through France, Lagarde or the ECB, and harder to reverse. If it is falling in line, the cause is the dollar and U.S. rates. That kind of move can reverse quickly when U.S. data softens or when the Fed signals that one more hike is enough. Today’s evidence points to dollar strength, which leaves room for a rebound.
The yen is the wild card. Japanese policy rates are at their highest in 31 years. USD/JPY near 160 raises the chance of intervention or a hawkish Bank of Japan surprise. A sharp yen rally would pull the Dollar Index down and lift EUR/USD, even without any European news. EUR/JPY near 176.7 at today’s rates (1.1127 times 159.23) shows the euro holding up better against the yen than against the dollar.
The dollar’s rally depends on U.S. yields. Cash Treasuries are closed today, so futures and currencies are carrying the price moves. When the bond market reopens Thursday, a 10-year yield above 5.015% would push the Dollar Index toward 103.50 and EUR/USD toward 1.1050. A 10-year below 4.90% would bring the Dollar Index back to 102.00 and EUR/USD back to 1.1175. Thursday’s bond reopening is the next key event for the pair.
Energy hits the eurozone harder than the U.S. December WTI crude traded at $88.18, up 2.49%, and Brent rose 1.32% to $92.70. That followed an Iranian army statement that a tanker struck a mine and caught fire in the Strait of Hormuz. On Tuesday, WTI fell to $86.04, its lowest since August 31, after the U.S. held off on strikes. Earlier in November, Brent fell 9% in one session on hopes for diplomacy.
The eurozone imports most of its oil and gas, while the U.S. is a net energy exporter. When oil rises, Europe’s trade balance worsens: more euros are sold to buy dollar-priced energy, which weighs on the euro. U.S. exporters earn more, which supports the dollar. Higher oil also lifts eurozone headline inflation through energy, now up 20.8%, more directly than it lifts U.S. core inflation. That pushes the ECB toward hikes it would rather not make in a slowing economy.
That tension shows up in growth expectations. Lagarde has said risks to inflation lean higher and risks to growth lean lower. Higher energy prices push the ECB toward tightening into weakness, with France shrinking, Italy flat and German exports slowing. Markets know an ECB hiking into weak growth can only go so far. So even when energy pushes eurozone inflation higher, the euro often falls, because markets doubt the ECB can keep hiking.
An Iran deal would help the euro most. A settlement that reopens the Strait of Hormuz would lower oil prices, improve Europe’s trade balance, ease energy inflation and reduce the pressure on the ECB. Lower oil would also ease U.S. inflation and might soften the Fed’s path. The net effect would favor the euro, because Europe is more exposed to energy. On Monday, when oil fell on comments from President Trump, the dollar weakened across the board.
Escalation would do the reverse. Brent above $100 would push EUR/USD toward 1.1050 and possibly 1.1000, because the trade effect and weaker growth outlook would outweigh any boost to ECB hike pricing. For the forecast, oil is a factor that pushes the euro in the same direction as Fed pricing. Lower oil and fewer expected Fed hikes together would mean the fastest path back to 1.1290.
Money is flowing toward higher yields. The U.S. 10-year yields 4.998%, and the 30-year yields 5.37%. In Europe, Germany’s 10-year Bund is far below those levels, and France’s is above 5% only because of its fiscal problems. A euro investor can earn more in U.S. Treasuries than in German Bunds, with the dollar’s added appeal while the Fed keeps hiking.
The gap in short-term rates matters even more for currency traders. The U.S. 2-year jumped 17 basis points on Tuesday on Fed repricing. Euro short-term rates did not move nearly as much, because the ECB’s path is flatter. A wider 2-year gap makes it more profitable to hold dollars, earning the U.S. rate, against euros, earning the lower euro rate. That rewards traders who are short EUR/USD and penalizes those who are long, which keeps steady pressure on the pair.
Money is also moving within the euro area. Investors leaving French bonds can buy German Bunds or U.S. Treasuries. Money moving into Bunds stays in euros and does not hurt the currency. Money moving into Treasuries leaves the euro. With U.S. 10-year yields near 5%, more of that money is going across the Atlantic. That outflow adds to the selling of euros.
Gold flows show the same pattern. North American gold funds lost $512 million in October, while European funds took in $1.8 billion. European investors are buying gold as protection against Middle East risk and government debt worries, and those purchases are priced in dollars. Some of that hedging means selling euros. Europe’s demand for safe assets is going partly into dollar-priced assets, which adds to dollar demand.
The trend in rate spreads favors the dollar until the Fed’s hiking pace slows. The key indicator is the gap between U.S. and German 2-year yields. If it starts to narrow, with the Fed signaling a pause or the ECB signaling more than one hike, EUR/USD will rise. If it widens, the pair falls. Tuesday’s 17-basis-point jump in the U.S. 2-year widened the gap and explains the move from 1.1172 to 1.1091.
EUR/USD has dropped sharply from levels above 1.1700, according to technical assessments. It now sits just above its main long-term support. One trend score puts the pair at 30 out of 100, showing heavy short-term damage, with price below a series of falling moving averages. The 20-day average sits near 1.1214, the 50-day near 1.1332 and the 200-day near 1.1540. The pair trades below all three, and the 20-day is below the 50-day, which confirms the downtrend.
Momentum is weak but not extreme. The daily relative strength index reads 47.9 on the fixing table, neutral rather than oversold. The pair has slid gradually rather than collapsed, so sellers have not exhausted themselves. That leaves room for a further drop before a reliable bottom forms, and it argues against buying aggressively at 1.1100.
The year’s lows define the structure. The 2026 low before today was 1.1120, and today’s break to 1.1091 sets a new one. Near-term support sits between 1.1088 and 1.1126, with 1.1104 as the next short-term target and 1.1111 as a base level. A daily close below 1.1088 would expose 1.1050 and then 1.1000, a round number last tested in spring 2025.
Resistance comes in layers. The first is 1.1175, today’s high and close to Tuesday’s 1.1172 close. Next is the 20-day average at 1.1214, then the 1.1227 to 1.1290 band. The November high at 1.1274 sits inside that band. A daily close above 1.1290 would be the first sign that the decline from 1.17 is over, and it would put the 50-day average at 1.1332 in play.
The positioning picture is negative but not crowded. The decline has been steady rather than panicked, so the market has not loaded up on short euro positions that could unwind sharply. That limits the chance of a sudden short squeeze and suggests any recovery will be slow. A sharp rebound would most likely come from a Fed surprise, such as a softer December statement, or from an Iran settlement that cuts oil prices.
The schedule over the next five weeks will decide where EUR/USD goes. U.S. cash Treasuries reopen Thursday after Veterans Day, and weekly jobless claims come out at 8:30 a.m. ET. Eurostat’s second third-quarter GDP estimate follows on Friday at 11:00 CET. U.S. producer prices come out the same day at 8:30 a.m. ET. These are the first tests of whether Tuesday’s dollar rally holds.
ECB officials will speak throughout the week. Isabel Schnabel, Luis de Guindos and Philip Lane all have scheduled appearances, and Lagarde attends the Eurogroup meeting. Schnabel has generally favored tighter policy, and Lane has pointed to the risk of hiking into weak demand. The balance of their comments will move ECB December pricing from its current 65%. Comments pointing to more than one hike would support the euro, while signals that December is the last hike would weigh on it.
November 18 brings the final October eurozone inflation data, the last input to the ECB’s December forecasts. Before that, the U.S. calendar has Nvidia earnings on November 17 and Thanksgiving on November 26, which will thin trading. Trading volume tends to fall in the last two weeks of November. That can make moves bigger in both directions, especially around the month-end rebalancing on November 30.
December holds the main events. The Fed meets December 8–9 and releases new projections and a dot plot. U.S. November CPI comes out December 10. The ECB decides on December 17 with new staff forecasts. The order matters: the Fed sets the dollar’s direction first, and the ECB reacts eight days later. A 50-basis-point Fed hike with a higher 2027 path would push EUR/USD toward 1.1000 before the ECB meets. A quarter-point Fed hike with signs of a peak would let the euro rebuild toward 1.1290 before the ECB.
Beyond December, the euro’s outlook depends on Lagarde’s successor, the French election in spring 2027 and how long energy prices stay high. Those are longer-term issues. In the next five weeks, the gap between Fed and ECB rate pricing decides where EUR/USD goes.
EUR/USD’s short-term structure is bearish. The pair broke below 1.1120, the previous 2026 low, and the 1.11 level, the first move below it since May 2025. The session ranged from 1.1091 to 1.1175, a span of 84 pips. Price trades below the 20-day average at 1.1214, the 50-day at 1.1332 and the 200-day at 1.1540. The downtrend from 1.1700 is intact.
The first support zone is 1.1088 to 1.1104, around today’s low. Below it, 1.1050 is the next level, followed by 1.1000. A daily close below 1.1088 would confirm the break and target 1.1050 within days, 50 pips or 0.45% below the current price. A move to 1.1000 would need U.S. yields above 5.05%, Brent above $100 or the French spread back above 160 basis points.
The key pivot is 1.1175, today’s high and close to Tuesday’s 1.1172 close. Getting back above 1.1175 would reverse today’s breakdown and suggest the drop below 1.11 was a false move. Above that, the 20-day average at 1.1214 and the 1.1227 resistance mark the first serious test. The November high at 1.1274 and the top of the resistance band at 1.1290 complete the near-term ceiling.
The upside target is 1.1290, 190 pips or 1.71% above 1.1100. Reaching it would need three things: a softer U.S. data run through Friday’s PPI that eases the 50-basis-point Fed risk; stronger ECB signals that lift December hike odds from 65%; and a steady or narrowing French spread. A daily close above 1.1290 would open the 50-day average at 1.1332, and beyond that the start of the 1.1400 range.
The risk-reward depends on direction. At 1.1100, downside to 1.1050 is 50 pips and upside to 1.1290 is 190 pips. That looks attractive for buyers, but only with confirmation, because the trend is down and momentum is not yet oversold. A close back above 1.1175 is the signal that shifts the odds toward the target. Without it, rallies are likely to be sold below 1.1214.
The bearish case has the advantage today. Futures price a December Fed hike at 100%, with an 11.8% chance of 50 basis points. The ECB is priced at 65% for a hike. Traders expect three more Fed hikes against one more from the ECB. The policy rate gap is 137.5 basis points and every realistic December outcome keeps it there or widens it. The U.S. 10-year yields 4.998%, the 2-year jumped 17 basis points on Tuesday, and the Dollar Index sits at 102.86, its highest since October 14. EUR/USD has broken below 1.11 for the first time since May 2025.
Europe adds its own risks. Inflation is 4.0% and driven by energy, while core holds at 2.5%. That limits how far the ECB will hike. France’s economy shrank 0.1% while its 10-year yield hit 5.05% and its spread over Bunds reached 160 basis points. Lagarde leaves early on February 7, 2027. Brent at $92.70 hurts Europe’s trade balance more than America’s. Each factor supports the dollar or weighs on the euro.
The bullish case is about timing and scope. Today’s move is broad dollar strength across every major currency, not a euro-specific collapse, and moves like that tend to reverse once U.S. rate pricing peaks. Eurozone growth beat forecasts at 0.4%. The ECB is still hiking. An Iran settlement would favor the euro because Europe is more exposed to energy. The pair’s RSI of 47.9 is neutral, and positioning is not crowded on the short side. A softer U.S. PPI on Friday or a Fed that signals one more hike is enough could trigger a sharp short-covering rally.
The near-term range is 1.1050 to 1.1214, with 1.1175 as the dividing line. Below 1.1175 the trend stays down, and a daily close below 1.1088 targets 1.1050 and then 1.1000. Above 1.1175 the breakdown is reversed, and the pair opens toward 1.1214, 1.1274 and the 1.1290 target.
The forecast is bearish in the near term while EUR/USD stays below 1.1175. The upside target is 1.1290, 1.71% above the current price, once 1.1175 is reclaimed. That needs U.S. yields to ease from 5%, ECB hike odds to rise above 65% and the French spread to stay stable. The Fed’s December 9 decision is the main catalyst, and the ECB’s December 17 response decides whether the euro can recover toward its 1.1568 average for 2026.
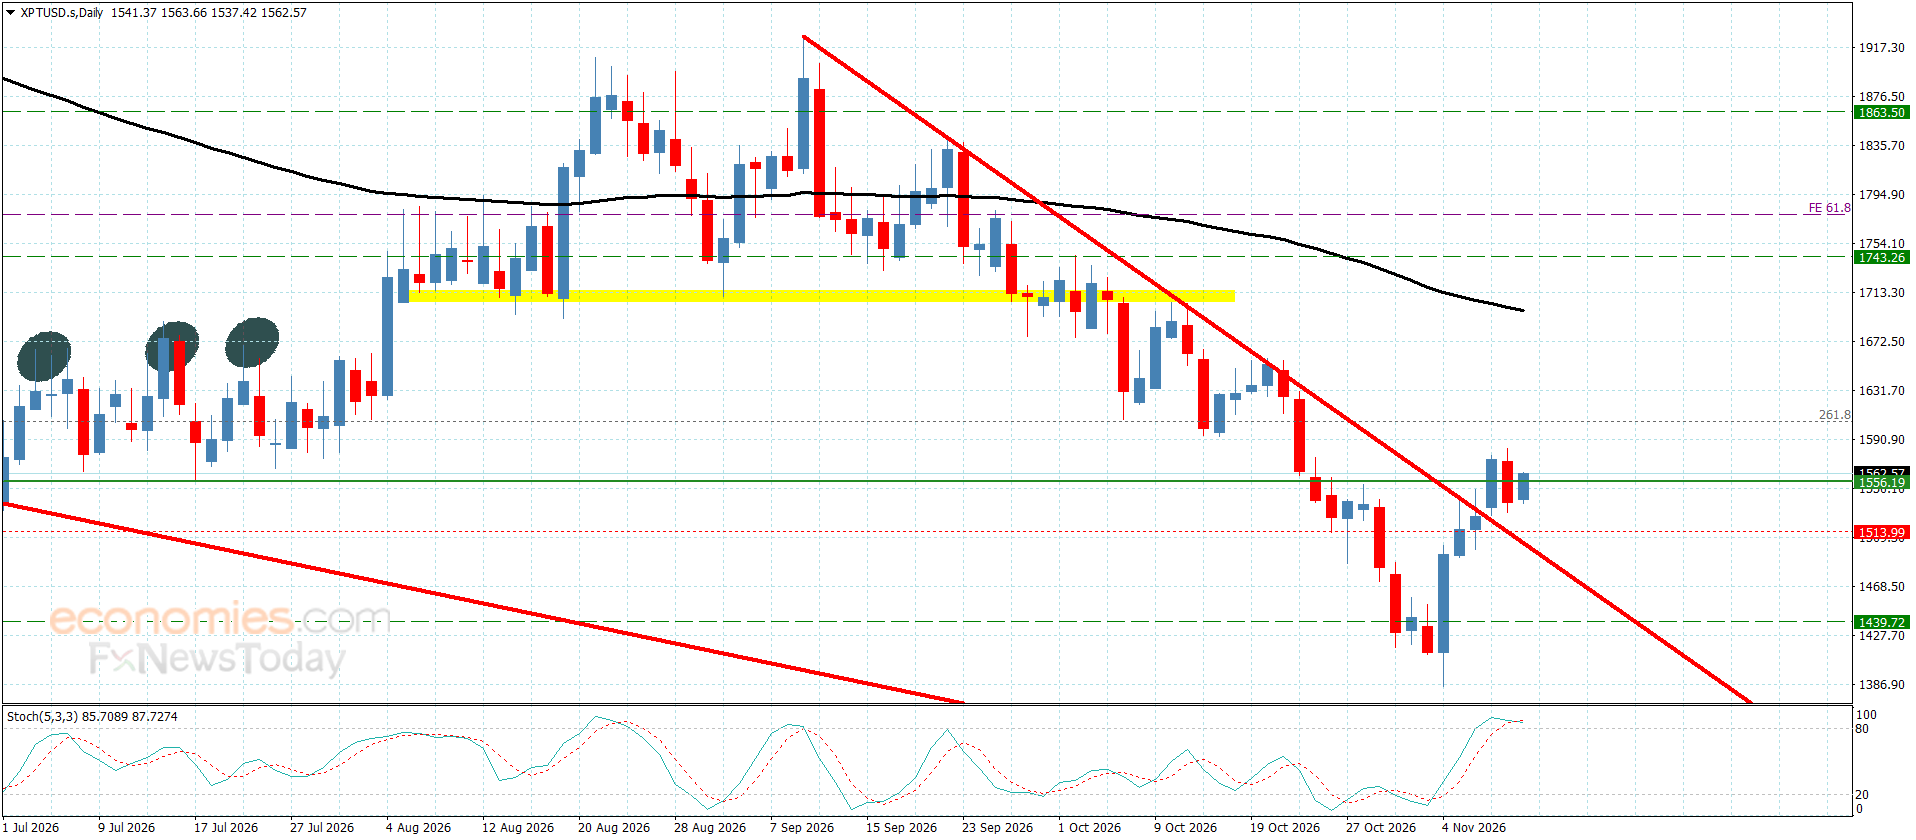
Platinum remains committed to its bullish corrective attempts, supported by its repeated stability above $1515.00. In addition, the Stochastic indicator has reached overbought territory, leading us to expect the price to attempt a test of $1610.00 in the near term. A break above this barrier could extend trading toward the next corrective target near $1580.00.
On the other hand, a decline below $1515.00 followed by a negative close would force the price into strong bearish trading, exposing it to further losses as it moves toward $1440.00 and then renews pressure on the barrier at $1385.00.
The expected trading range for today is between $1520.00 and $1610.00
Trend forecast: Bullish
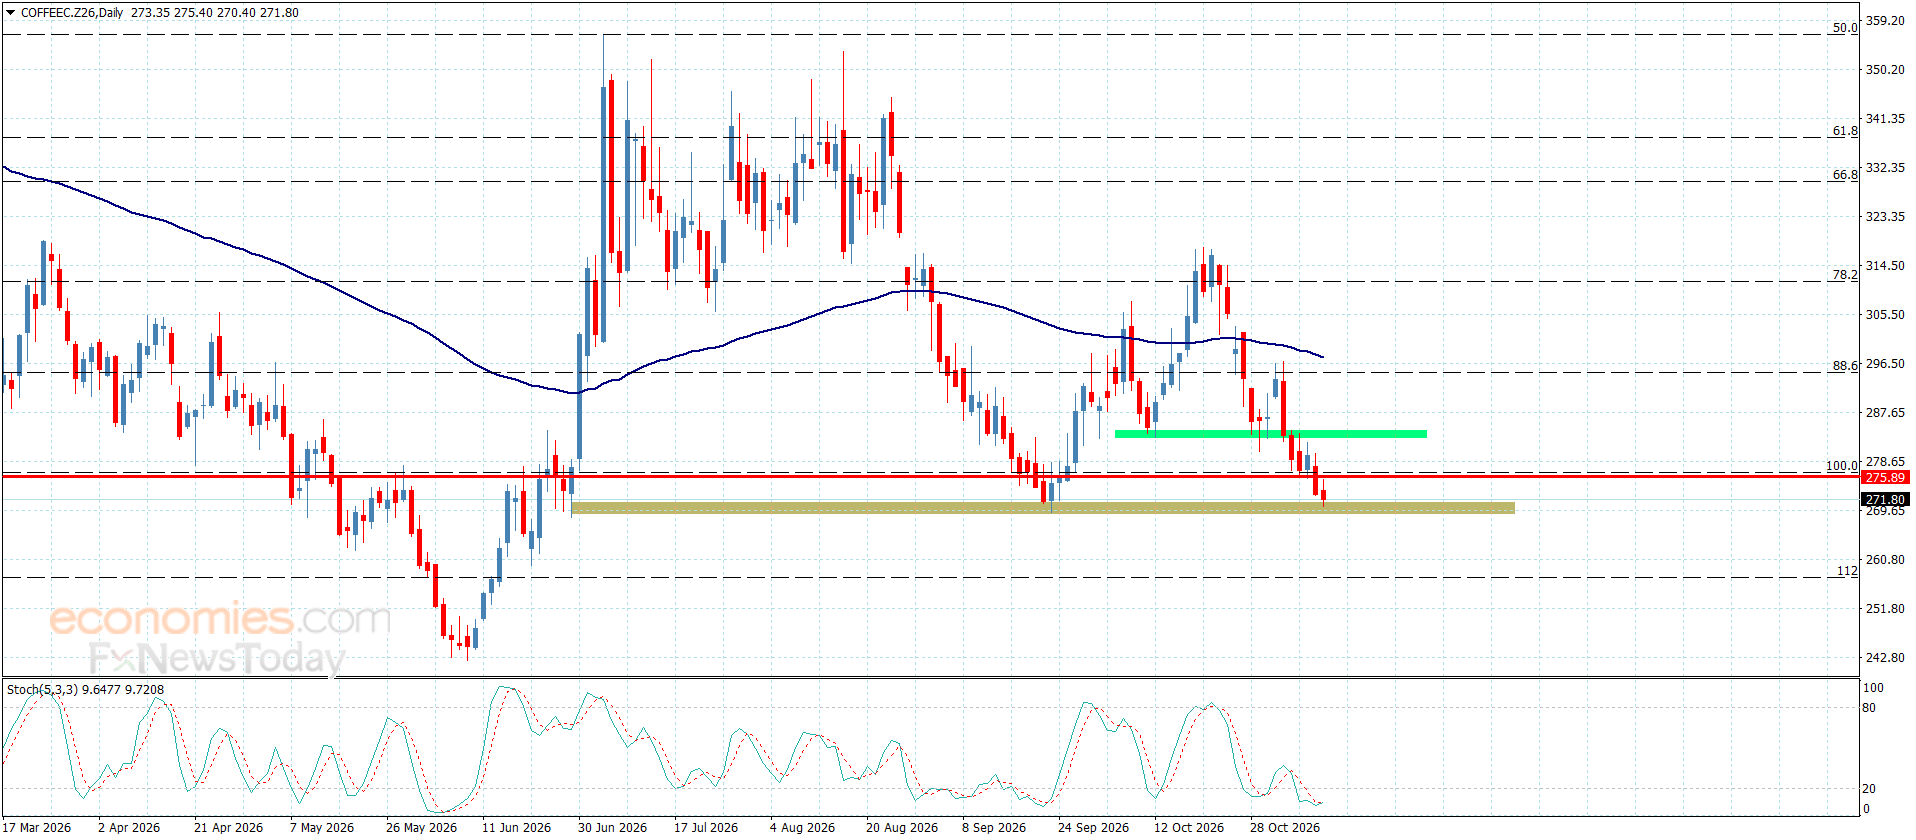
Coffee price surrendered to the negative pressures that come from providing negative momentum by the main indicators, to reach below 282.70 level, to retest the main support at 269.00.
Note that forming a new extra barrier at 283.00 level besides providing negative momentum by the main indicators, these factors make us wait for breaking the current support and providing a negative close below it, to confirm its readiness to target new negative stations by reaching 263.00 and 255.00.
The expected trading range for today is between 263.00 and 278.10
Trend forecast: Bearish
The pair failed to hold above the 212.00 level for long, as the main indicators showed conflicting signals. It is currently trading sideways, fluctuating near 211.90, while maintaining its chances of resuming its bullish corrective attempts, supported by the formation of the first additional support level at 210.40.
We recommend waiting for confirmation of a breakout above 212.00, as this would activate the bullish corrective move, to head toward resistance at 213.50, which represents the key level for confirming the overall direction of upcoming trading.
The expected trading range for today is between 211.35 and 213.00
Trend forecast: Bullish
Brent crude futures rose near $92 per barrel, while US West Texas Intermediate (WTI) crude futures increased to over $86 per barrel on Wednesday morning.
“Iran militarily is effectively over. We are just keeping it the status quo,” Trump said on Monday after meeting with Qatar’s prime minister. The US President added that Iran has been “decapitated” but he is still looking to make sure there is a long-term solution to ensuring that Iran’s nuclear programme is defanged. “The military action doesn’t seem to be a very necessary thing, but we are locked and loaded, ready to go for any reason that changes,” Trump said.
This came a day after Trump said that the US could avoid another round of military action against Iran, only if the latter agreed to what he described as a strong deal. “It depends on whether or not they sign a very strong agreement. The answer is, highly unlikely it’s going to be necessary,” Trump told CNN during a phone interview. He repeated five times that renewed military intervention was unlikely if Iran made tangible progress in discussions over its nuclear programme and the reopening of the Strait of Hormuz.
While Trump’s comments this week boosted hopes for a resolution to the Middle East conflict, many are of the opinion that it may be too early to count on an announcement by someone whose frequent change of stance is only too well known. Meanwhile, the American naval blockade or Iran remains firmly in place. Iranian oil exports are still under as much pressure as any time in the recent past. A new US task force called the Iron Gate is being deployed with a mandate to restrict Iran’s overland trade.
According to recent US Centcom estimates cited by AP, Iran has been stopped from exporting more than $25 billion worth of crude. This means the Iran war is not a simple, straightforward military campaign anymore, but an economic war with high costs for the besieged side, Reuters and AP reported.
Also read | Trump’s Iran war may be ‘militarily’ over, but economic siege still haunts
Goldman Sachs recently raised its oil price forecasts, citing increasing risks to global supplies. The investment bank warned that Brent crude could climb to $140 per barrel in 2027 if oil production across the Gulf region remains significantly below its 2025 average.
The bank raised its December Brent crude forecast to $105 per barrel from $90 earlier. Its forecast for US West Texas Intermediate (WTI) crude was also increased to $94 per barrel from $81.
In an upside scenario, Brent crude could reach $140 per barrel and average around $130 in 2027 if Gulf oil production remains 3.5 million barrels per day below its 2025 average, Reuters reported, citing Goldman Sachs’ projections.
Goldman Sachs expects oil markets to incorporate a higher geopolitical risk premium, given the possibility of disruptions to Middle Eastern supplies, the historical duration of major supply shocks and the challenges involved in securing a lasting diplomatic breakthrough.
JPMorgan analysts also highlighted the uncertainty surrounding the conflict, saying it remained difficult to predict how the war would unfold. At the outset, the bank had expected the US administration to avoid crossing certain economic thresholds. However, seven months into the conflict, several of those thresholds have been breached, while a clear strategy to bring the war to an end has yet to emerge.
Also read |India in a ‘sweet spot’ amid oil volatility and currency dynamics: Kotak Neo’s Anindya Banerjee
Disclaimer: This article has been written by Debaroti Adhikary, who is not a SEBI-registered Research Analyst or an Investment Adviser. Debaroti Adhikary and his/her ‘relative(s)’ (as defined under Section 2(77) of the Companies Act, 2013) do not hold any financial interest in the companies mentioned in this article as of the date of publication. The views/recommendations mentioned in this article, wherever applicable, are those of the respective SEBI-registered Research Analyst/brokerage and have been reproduced/reported with due attribution. They should not be construed as the views or recommendations of The Economic Times Digital or the journalist. Readers are advised to consider the original research report and make their investment decisions based on their own assessment. Brokerage disclaimers here.
The pair maintained its stability above the additional support level at 176.15, making some bullish attempts that pushed it toward 177.25. However, it remains below resistance at 178.10, as the main indicators have continued to show conflicting signals recently.
We emphasize the importance of gathering additional positive momentum to strengthen the pair’s chances of breaking above 178.10, paving the way for further gains toward 178.70 and 179.40. Failure to break above this barrier will force the pair into mixed trading, with the possibility of declining again toward main support at 174.95.
The expected trading range for today is between 167.40 and 178.10
Trend forecast: Bullish
– Written by
James Fuller
STORY LINK British Pound to Euro Forecast: ANZ Cautious as GBP/EUR Tests 20-Month Highs
The Pound to Euro exchange rate (GBP/EUR) held close to 20-month highs around 1.1980 as Sterling continued to attract buyers despite renewed volatility in global equity markets.
However, ING and ANZ warn that the Pound’s rally is becoming stretched, with expectations of further Bank of England rate hikes already heavily priced and increasingly hawkish ECB signals offering the Euro some protection.
After some evidence of vulnerability when equity markets retreated sharply, Sterling has continued to find support on dips with the Pound to Euro (GBP/EUR) exchange rate trading close to 1.1980 and still near 20-month highs.
Investment banks remain generally reluctant to chase the Pound substantially higher at current levels.
ANZ commented; “The cross [EUR/GBP] has fallen to around 0.834, well below its key daily moving averages. The broader trend is lower, but with the BoE and ECB expected to tighten and substantial UK tightening priced in, we would not chase EUR/GBP downside [buy GBP/EUR] from current levels.”
ING is also cautious over further Pound buying at these levels; “EUR/GBP continues to trade sharply below its short-term fair value, by around 2.6-2.8% according to our models. That continues to reflect the euro’s idiosyncratic premium related to French risk, but even accounting for that, the decline in the pair looks a bit too stretched.”
Get better rates and lower fees on your next international money transfer.
Compare TorFX with top UK banks in seconds and see how much you could save.
Bank of England policy will continue to be monitored closely following last week’s increase in Bank Rate to 4.00%.
The debate has now shifted towards whether policymakers will deliver another increase in December or wait until February.
Deputy Governor Clare Lombardelli said on Tuesday that persistent inflation risks are crystallising and that both meetings remain possible opportunities for further tightening, depending on energy prices and incoming inflation and labour-market data.
ING has argued that consensus around another increase will be harder to achieve next time, with some policymakers considering a one-and-done approach.
Governor Andrew Bailey has also signalled caution over the extent of further tightening.
Market pricing for several additional rate increases therefore still looks aggressive to a number of investment banks, limiting the scope for Sterling to benefit purely from another shift in yield expectations.
Commerzbank maintains the view that the next increase is more likely to come in February than December, particularly if Middle East tensions ease and energy prices begin to normalise.
The Euro has also gained a potential source of support from increasingly hawkish ECB commentary.
ECB chief economist Philip Lane said on Tuesday that a December rate increase may be necessary if current economic and inflation conditions persist.
Eurozone inflation reached 4.0% in October, and policymakers remain concerned that the energy shock could generate broader price pressures.
This limits the extent to which widening UK rate expectations can continue to favour Sterling.
The Euro-Zone Sentix investor confidence index edged lower to 2.4 in November from 2.7 previously, but remained above consensus forecasts of 2.1.
Sentix commented; “Whilst the economy in the eurozone remains stagnant, there are at least signs of a slight economic recovery in Germany – albeit in tiny steps.”
Markets are also monitoring the race to replace ECB President Christine Lagarde, who will leave office on February 7.
Former Dutch central bank governor Klaas Knot and former Bank of Spain governor Pablo Hernández de Cos are the two nominated candidates, with EU leaders aiming to settle the appointment in December.
For GBP/EUR, 1.20 remains the immediate resistance area.
A sustained break above this level would strengthen the bullish technical picture, while 1.1900-1.1950 should provide initial support.
For now, Sterling remains underpinned by resilient UK growth and expectations of further BoE tightening, but the combination of stretched valuation and a potentially more hawkish ECB limits the case for aggressively chasing GBP/EUR higher.
International Money Transfer? Ask our resident FX expert a money transfer question or try John’s new, free, no-obligation personal service! ,where he helps every step of the way,
ensuring you get the best exchange rates on your currency requirements.
TAGS: Pound Euro Forecasts
Following a sharp decline earlier in the week, the global oil market is experiencing mixed trends. While WTI crude oil prices have recovered slightly, Brent crude oil continues to fall, returning to around $92 per barrel. In Vietnam, gasoline and diesel prices remain based on the price list published on November 5th, with only one day left until the next scheduled price adjustment.
According to reference data from November 11th, WTI crude oil prices were recorded at $86.44 per barrel, an increase of $0.20 per barrel compared to $86.24 per barrel on November 10th. This increase, equivalent to approximately 0.23%, indicates a slight recovery in WTI oil prices after the previous decline.
Meanwhile, Brent crude fell from $92.33 per barrel to $92 per barrel, a decrease of $0.33 per barrel, or about 0.36%.
Comparison table of world oil prices on November 11, 2026:
| Type of oil | November 10th | November 11th | Change |
|---|---|---|---|
| WTI oil | 86.24 | 86.44 | +0.20 |
| Brent crude oil | 92.33 | 92.00 | -0.33 |
Unit: USD/barrel. The data is based on two reference points, not the closing price of the trading session.
Notably, the WTI price range on November 11th fluctuated from $83.89 to $86.92 per barrel, significantly wider than the $86.15 – $86.65 per barrel range recorded the previous day.
For Brent crude, the benchmark range on November 11th was between $92 and $92.10 per barrel, while on November 10th it fluctuated between $92.12 and $93.12 per barrel.
Crude oil price range table:
| Type of oil | November 10th | November 11th |
|---|---|---|
| WTI | 86.15 – 86.65 | 83.89 – 86.92 |
| Brent | 92:12 – 93:12 | 92.00 – 92.10 |
Unit: USD/barrel.
The above developments indicate that the oil market has not yet formed a clear recovery trend after the sharp decline. Although WTI oil edged up slightly, the increase was still quite modest, while Brent oil remained under downward pressure.
As of the November 11th update, the price difference between the two types of oil was $5.56 per barrel.
In the short term, fluctuations in oil supply and demand, trading activity, and changes in refined fuel prices on the international market will continue to be closely monitored. These are also factors that could impact gasoline and diesel prices in Vietnam in the upcoming price adjustment period.
While the global market is volatile, retail gasoline and diesel prices in Vietnam on November 11th continue to apply the Petrolimex price list effective from 3 PM on November 5th, 2026.
Accordingly, E5 RON 92-II gasoline in Zone 1 is priced at 20,890 VND/liter, while E10 RON 95-III gasoline is listed at 21,150 VND/liter.
Petrolimex fuel price list as of November 11, 2026:
| Product | Region 1 | Region 2 |
|---|---|---|
| E10 RON 95-V gasoline | 22,650 | 23,100 |
| E10 RON 95-III gasoline | 21,150 | 21,570 |
| E5 RON 92-II gasoline | 20,890 | 21,300 |
| DO oil 0.001SV | 30,090 | 30,690 |
| DO 0.05S-II oil | 28,690 | 29,260 |
| 2-K kerosene | 28,600 | 29,170 |
Unit: VND/liter. Petrolimex price list published from 3 PM on November 5, 2026.
In the price adjustment on November 5th, domestic fuel prices were significantly reduced. According to the maximum prices announced by the regulatory agency, E5 RON 92 gasoline decreased by 2,305 VND/liter, E10 RON 95-III gasoline decreased by 2,075 VND/liter, and 0.05S diesel decreased by 180 VND/liter.
Thus, gasoline prices recorded a larger decrease compared to diesel prices in the recent price adjustment period.
With current prices, motorcycle and car users can continue to benefit from the lower gasoline prices. Meanwhile, fuel costs for diesel-powered transportation remain relatively high.
Fuel prices in Zone 2 apply to areas far from ports, main depots, or fuel production facilities as stipulated. The actual price in each area must not exceed the Zone 2 price announced by Petrolimex.
According to the regular price adjustment schedule, domestic gasoline and diesel prices are expected to be adjusted at 3 PM on Thursday, November 12, 2026.
Recent developments in the crude oil market are creating some favorable signals for a potential fuel price reduction. Notably, both WTI and Brent have retreated to significantly lower levels compared to the beginning of the week, although WTI showed a slight recovery as of November 11th.
However, fluctuations in crude oil prices do not necessarily mean that domestic gasoline prices will decrease. Retail prices in Vietnam also depend on the price movements of refined petroleum products on the world market during the pricing period, along with factors such as exchange rates, taxes, business costs, and the price stabilization mechanism as stipulated by regulations.
If international refined petroleum prices continue their downward trend, the price adjustment on November 12th may see further downward pressure on some commodities.
Conversely, if product prices recover or other cost factors increase, the decline may narrow, and some products may even experience different outcomes.
Due to the lack of complete data for the entire pricing period, there is currently insufficient basis to accurately determine the increase or decrease in the prices of individual petroleum products in the next price adjustment period.
For the time being, retail prices at Petrolimex’s system will remain at the levels announced on November 5th. Consumers can continue to monitor the global oil market and wait for the official announcement on gasoline and diesel prices on the afternoon of November 12th.